If you can’t make it to the theatre it’s possible to watch a number of productions from your sofa via streaming services.
There are big-name theatres and companies such as the RSC, as well as productions starring famous names like David Tennant.
During lockdown many theatres offered free shows each week, but these seem to be stopping. However, you can still watch shows via subscription services.
Subscription services & rentals
Hamilton on Disney +
You can watch a recording of the original Hamilton cast on Disney +. It costs £5.99 a month – though there are ways to save. For more discounts visit my streaming service deals page.
You pay what you’d pay if you were going, with the minimum price £10, but you can choose to give up to £65.
For Christmas the production includes A Christmas Carol.
National Theatre at Home
You can either rent individual productions or subscribe to access a range of National Theatre shows and other productions with National Theatre at Home.
It costs £8.32 a month, or £83.32 for a year.
Wind in the Willows at the Palladium
This production with Rufus Hound from 2017 was free, but is now £4.99 to rent.
Marquee TV
This has some theatre but it’s probably best for dance and opera fans. You can get a 30-day free trial. After that it costs £8.99 a month or £89.99 a year – though there’s a £20 discount for your first year.
New shows are premiered every Saturday. Theatre seems to mainly be RSC and an Oscar Wilde season, but there’s a huge amount of dance from the likes of The Royal Ballet and the Bolshoi, with opera from Glyndebourne and others
Digital Theatreis a streaming service that costs £9.99 a month for unlimited viewing, or £7.99 per production.
It includes shows from the likes of the RSC, Old Vic, Donmar, Lyric and Royal Opera House.
Shows includes Funny GIrl with Sheridan Smith, Hamlet with Maxine Peak, Much Ado About Nothing with David Tennant and Into The Woods from Regent’s Park.
There’s also ballet, dance, opera and classical music.
How to get two-for-one, Kids go free and other deals to save money and get you cheap theme park tickets.
I love a good theme park – but ticket prices for UK theme parks such as Alton Towers and Thorpe Park can be more terrifying than the fastest ride, especially for a family. But it’s actually really easy to pay less.
Here are some of the best deals right now to get cheap theme park tickets.
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
Cheap theme park ticket rules
These are the basics that should help you avoid paying full price.
Use a promo code
Every single year there are discount codes, usually offering 50% off or two for the price of one tickets, to all the major theme parks. Smaller parks might have smaller discounts, but there are still savings to be found. We’ve listed below some of the best ones available right now from products you’re likely to buy.
Book in advance
Whether you’re using one of the codes below, or just paying full whack (why?), it makes sense to book in advance as prices are much cheaper. Often, the earlier you book, the better, with online prices on the day often more expensive (though still cheaper than buying on the door). You can sometimes stack a 2-4-1 code with these cheaper prices, meaning you’ll pay even less.
The annual pass trick
You can often pick up a season pass, giving unlimited access to one or multiple Merlin theme parks for the cost of a single ticket. Of course, if you’ve used the other promotions listed on this page you should only have paid 50% of the entry price. But if you are going to go at least twice in a year, then you may as well buy the season pass – even if you don’t go again.
Do check again for any restrictions, for example August weekends and special events are often excluded unless you buy a premium pass.
You can get season passes at locations including:
Alton Towers
Legoland
Thorpe Park
Chessington World of Adventures
Try for cashback
While you likely can’t get cashback with some of the offers below, as they’re often booked via promotional websites, if you’re going directly to get tickets, it could be worth trying Quidco or TopCashback for a little something extra — this is only 1.5%-2% at the time of writing, but that could stack up when you’re booking a whole family. Plus, if you don’t have either of these sites already, you can get a £20 welcome bonus when you sign up.
Latest theme park special offers
You can regularly get deals on promotional packs of anything from cereal to soaps. Many do have exclusions, including weekends in August and sometimes October half term. So do check. We’ve put in links with the exclusions and also the lists of participating theme parks, where possible.
National Rail Days Out: 2 for 1 or 1/3 off tickets
If you catch the train to a theme park, then you can get 2 for 1 or 1/3 off tickets on the National Rail website. You have to pre-book with a lot of the attractions, and it’s worth checking what else you’ll need. It’ll often specify that you’ll need a ticket to a nearby station on the day you’re booking. For example, to book Cadbury World, you’ll need a valid train ticket to Bournville station for each visitor and for the same day as your visit.
This is valid until 31 May 2026, although this is renewed every year.
Attractions include zoos, museums, theme parks, boat trips, galleries and activities.
Merlin is currently offering a slightly different kind of two-for-one ticket. Instead of getting two people in for the price of one, it’s offering tickets to two theme parks for the price of one. So you can get two days out for the family for the price of one.
Tickets cost from £34 if your first trip is to Alton Towers or Legoland, £33 if your first attraction is Thorpe Park or just £32 per person if your first visit is to Chessington. They can be bought on the website of your chosen attraction to go to first – look at the “offers” tab and select “twice the fun” to find them.
Then, once you’ve booked your first visit, you’ll have a barcode on your ticket which you can use to pre-book your second visit at Chessington World of Adventures, Legoland Windsor, Alton Towers or Thorpe Park. The first and second attractions don’t need to be the same.
If you pay for Sky TV, then take a look at the Sky VIP section in your account to get a unique code for £17.50 tickets to Legoland this summer.
Tickets are available throughout the remainder of the season, including Legoland at Christmas, but tickets are expected to sell out fairly quickly. You need to buy them before 31 August 2025. You can book up to six tickets each time.
Buy a promotional box of Kellogg’s cereal or a Snack Pack and get 25% off up to two online advance-priced tickets at 25 participating Merlin attractions, including Thorpe Park, Alton Towers and Chessington World of Adventures.
To get it, scan the QR code from a promotional Kellogg’s pack or go to their website. You’ll need to register or login with a Kellogg’s account and enter the 10 digit KPIN code from the promotional pack. You’ll then get a discount code emailed to you with a link to book.
With Snack Packs, you must bring the promotional pack with you, along with your pre-booked e-ticket and show it at the ticket desk.
Tickets are valid until 30 June 2026. Exclusion dates apply and do check the terms and conditions.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Tesco Clubcard points
If you’re earning points, you can get double value at theme parks, including Alton Towers. Personally, I’d say you’re better off using your points elsewhere, particularly for the Merlin-owned attractions.
That’s because although this promo is in theory the same as the 2-4-1 style offers, the prevalence of the latter means you’re effectively only getting 25% off that lower price. More on Clubcard deals here.
Though the wording is different, it’s essentially the same thing, it’s just the adult ticket is free when you buy another full price adult or kids ticket.
Once again it’s for Merlin attractions, so the main theme parks are Thorpe Park, Chessington and Alton Towers.
Any vouchers you collect will be valid until 30 June 2024. Details here. You’ll need to keep the promotional packaging to share at the venue entrance.
Merlin has launched another sale on its annual passes. These run for a full year from when you buy them, so you’ll be able to get until April 2025 if you get one while the deal is on. The sale is on until 7 April 2024.
This gets you into any Merlin attraction – this includes Thorpe Park, Alton Towers, LEGOLAND, Sealife Centre and the London Eye. The different stages of pass have different perks – for example, the Gold one includes parking (usually £5-£10 each time), and there are restricted days on the Silver and Discovery passes. Some of them also have a sign-up fee if you go for a monthly option.
Remember, you’re unlikely to need to pay full price for entrance thanks to other deals, so you’ll need to weigh up whether the pass will represent good value depending on how often you’ll visit the attractions.
The smart app and card has made big changes to what you get.
Regular readers will know I’ve quite a few current accounts and a few credit cards – all with different benefits. To carry them all with me would just be impractical.
But Curve has allowed me to add almost every single card to a digital wallet and just carry the single Curve card with me instead.
I’ve been using the Curve card since it launched in 2016, and though not perfect, it’s been a staple in my wallet. But from summer 2022 there are new limits being put in place for free users. So is it still worth it?
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
What is Curve?
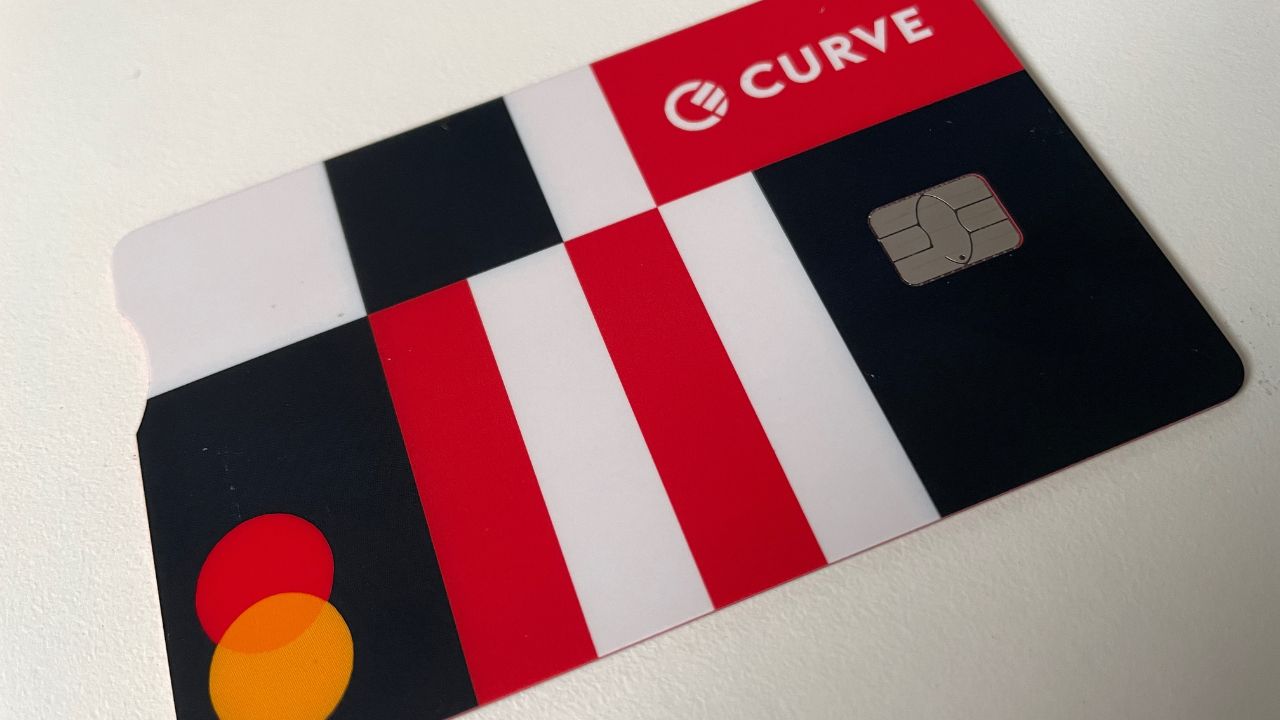
Curve lets you use more than one bank or credit card through a single “smart” debit card that you manage via an app.
In lots of ways it’s similar to using Apple Pay or Google Pay, with the added benefit of a physical card and some cool features such as changing your payment card after purchase, low or fee-free spending overseas and earning cashback.
However you can only add MasterCard or Visa cards to your Curve account. This rules out others such as American Express or Maestro.
You might also get limited access to some features depending on which Curve card you have.
Types of Curve card
There are four options: Curve, Curve X, Curve Black and Curve Metal. Each has a different cost and access to different features.
Curve is free (previously known as Curve Blue)
Curve X is £4.99 a month
Curve Black costs £9.99 a month
Curve Metal costs £14.99 a month or £150 if you pay upfront for a year
Curve features and limits by card
I’ll explain these features and limits in more detail throughout the review.
From July 2022, there will be new limits on the free card. According to Curve, the changes are due to increasing costs and a shift in focus “towards short term profitability”.
Rather than ditch the free option completely, they’ve reduced what it offers and introduced a mid-tier Curve X card.
The big difference between these two cards and the premium cards will be the number of cards you can add. Until now there have been no limits to the number of cards you can add to your Curve card, regardless of the type you have. So you’d be able to get the free option and benefit from this core feature.
Now the free Curve card will only let you add two cards, while Curve X limits you to five cards. Both Black and Metal remain unlimited.
Curve free will also only allow only three uses of the Back In Time feature each month and one smart rule. Curve X will limit you to five smart rules.
I’ll give my full opinion at the end of the review, but this is a huge change and it means the free option is very, very basic.
One year of Curve X for £1.99 a month
Existing free Curve customers will have the option of a 60% discount on Curve X for a year. You’ll pay £1.99 a month rather than the full £4.99. You’ve 30 days to upgrade from when you are notified, which means this offer will end by late July 2022.
Curve card and app features
All in one connected cards
The big sell for Curve, in my view, is the ability to slim down your wallet but still have a physical card to use. However, in reality it never quite meant I could have just one card on me.
As mentioned, you can’t add American Express cards, so I’ve always got that in addition. Plus I always want to have a non-Amex credit card on me for large purchases over £100 at retailers that don’t take Amex (to ensure I get Section 75 protection).
So I generally carry my Curve, Amex and another credit card at all times. It has allowed me to ditch my business debit card and a couple of other debit cards.
However, the new limits on the free and X tier really reduce the ability to maximise this feature. Having just two cards on the free card feels a bit pointless, and blocking business cards on this tier could be a real issue. The slightly higher limit of five cards on X might be enough for some.
If you can manage with these limits, then great. But I think the more you need to carry extra cards or have to add them to your phone’s digital wallet then the less Curve serves a purpose.
The Go Back In Time feature is a great idea, and one I tend to use a lot. If you forget to change the payment card you want to use in the app before buying, you can switch it to a different one within a 30 to 120 day window (depending on the card).
This has been really useful for me when spending money for my business. Rather than claim it back, I can just swap the expenditure over to my business bank account.
I’ve also used it a lot for spending via Chase Bank in order to earn the 1% cashback. This isn’t my main account, so I don’t always have lots of money in there. Go Back in Time has meant I’d pay from my main current account, then switch the transactions to Chase once I’ve topped it up.
But again, the new limits on this feature make it pretty pointless on the free option as you can use it just three times a month.
The paid cards let you do this unlimited times a month, though there are different windows for how far back you can go. You can also only change a payment once.
Anti-embarrassment mode
If for some reason your selected payment card is declined, then you can activate up to two backup cards in the app which will be automatically charged instead. This is available on all Curve cards.
Smart Rules
This is a new feature that looks to be expanded on soon. You’re able to create rules for spending on specific cards based on factors like the type or size of transaction. I’ve set up cash withdrawals to always come from my main linked debit card.
You get one Smart Rule with the free Curve, moving up to five with X and then unlimited rules with Black and Metal.
Other app and card features
As soon as you use your Curve card to pay you’ll get a notification on the app, which helps you keep track of what you’re spending.
There’s a timeline of all purchases made on Curve, no matter which card you used. Which helps you see all your spending in one place.
You can also lock your card if it’s lost, or check your PIN and card details.
However, Curve is an attractive option as a back up or if you don’t already have or can’t get one of these specialist credit or debit cards.
For a start, there’s no credit check to get it – unlike when applying for a Halifax Clarity or Barclaycard Rewards credit card. You’ll also be able to use your connected main debit or credit card and avoid that bank’s own hefty charges.
However there are limits on spending and withdrawals that reset on a rolling 30-day period. The size of each limit depends on the type of Curve card you have (see table above). If you go above these amounts you’ll get charged a 2% fee.
Plus although Curve is fee-free when using it Monday to Friday, at the weekend a 0.5% charge will be added for Dollars and Euros transactions and 1.5% to other currencies. This is temporarily paused in the summer of 2022, but will return from 1 September.
Curve Flex
Curve Flex is a way to borrow cash on purchases you’ve already made. It’s effectively a restrospective Buy Now, Pay Later scheme – but with interest added on.
You can choose a transaction and then split it into instalments of three, six, nine or 12 months. Those instalments will be taken from a selected card each month to repay the loan.
There’s a soft check on your credit report to see if you can be offered the loan, then a hard check if you proceed.
There’s obviously interest added on top too. Curve says rates begin at 9% though the representative APR is 14.18%. This is probably cheaper than an overdraft or credit card (except 0% cards), but not something that should be used lightly. It’s better to save up for anything you can’t afford.
If you miss a payment because there’s not enough available on the linked account you’ve seven days to pay it (Curve will try this automatically). If you still don’t catch up in this time you’ll be charged £6.
A big attraction with Curve is cashback. There are two ways to earn this, though you won’t get both on all the cards.
Curve Rewards
This is available on all the Curve card and allows you to earn money back on certain purchases. These offers come and go, such as 15% off Disney+ or 5% back at Five Guys. Watch out for restrictions, such as new users only. You need to activate the offer in the app, then pay using your Curve card.
The money you earn will be added to your Curve Cash wallet, which you have to select before spending to use (Back in Time won’t work).
Curve Cash (Metal and Black only)
The premium Curve cards also offer ongoing cashback at 1%, but only on limited retailers that you must select. For Black, it’s three shops, and for Metal, it’s six shops.
Once you’ve chosen them you’ll earn money back each time you use your Curve card there, and once again the money made will be put in your Curve Cash wallet.
This is just a selection. The full Curve Cash list is available on the Curve website, although annoyingly it includes European brands alongside the UK retailers.
Personally I’d pick one of the supermarkets in my three or six. Spend £200 a month on groceries and you’ll earn £24 over a year.
The big rewards come if you’re looking to make a big purchase or two, such as furniture or white goods at the likes of John Lewis, Apple or Ikea.
Then it’s worth thinking about places you shop at often, such as Starbucks. You’ll get less cashback per transaction but it’ll add up over the year. Petrol is a good option too.
Curve cashback and existing bank offers
If you have any retailer-specific offers on your underlying cards they won’t be recognised.
For example, my John Lewis credit card will give 1.25% back off when I shop at Waitrose. But if I used that card via Curve I’d get just 0.25% back.
So only use the Curve rewards if they are better than what you’d get direct with your bank card.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Curve Insurances
Both Black and Metal come with added insurance as part of the fees. Black has worldwide travel insurance, while Metal also adds car collison waiver and mobile phone cover.
Don’t just assume these are going to provide the cover you need. Check the policy documents and limits.
Using Curve
As mentioned I’ve used Curve since it first launched in beta. On the whole it works really well.
In shops and online
You use the card as you would any normal debit card. I’ve had no problems paying in shops. On my bank statements, transactions appear as CRV followed by the shop name, so for example CRV*SAINSBURYS.
Cash machines
It works getting cash out of my current account via an ATM too. There’s a £200 a day cap.
You can even get cash out using a connected credit card without incurring extra charges (normally you should never get cash out on credit cards). However there is a limit of £200 a month for this.
You won’t be able to use Curve for pre-authorisations, such as pay-at-the-pump petrol or car hire deposits.
There’s a daily spending cap of £2,000, and a rolling monthly cap of £5,000. You can’t spend more than £10,000 a year. These will increase the longer you have your card.
Curve Fronted
You’ll be charged 1.5% if you use an underlying credit card for services which don’t allow this (e.g. paying your tax return or paying off a different credit card bill). This feature is known as Curve Fronted.
The Metal tier of Curve has a £10,000 allowance where this charge isn’t added, though Curve warns this could impact your credit score, depending how your credit card company treats these transactions.
Your consumer protection
Any purchase you make with Curve, even the underlying card is a credit card, isn’t covered by Section 75 of the Consumer Rights Act. These laws basically give you better protection for anything which costs more than £100.
However, Curve has its own customer protection policy, and ultimately all purchases via your Curve card are covered by the Chargeback scheme.
How to get a Curve card and £10 welcome bonus
You simply enter your mobile number on the Curve website and you’ll be sent a link to download the app, or search in your phone’s app store.
Get a free £10 credit (ended 8 July 22)
When you sign up via this link you’ll be eligible for a £10 welcome bonus – double the standard referral offer of £5. There’s no need to enter the promo code as the link has tracking which will register the offer.
Once you’ve signed up you then need to spend at least £5 on the card and do it within seven days of applying. If you don’t want to wait for the card to arrive in the post you can access the details to use it online via the Curve app, or add the card to your digital wallets such as Apple Pay.
To use this £10 reward you need to use the app to select the Curve Rewards option before you pay.
I love the idea of Curve and I’ve been a fan for many years. Sadly the new limits on the free options make it a frustrating product.
I’m not sure what benefits come from having just one card in your wallet rather than two cards, especially when they can’t be an Amex or business card.
I use features like Back in Time because I can, not because I need to. So I’m perfectly happy losing the access to this rather than splash out unnecessary cash. Though ultimately it means I can’t see a use for the free Curve card.
As as I want to use my Amex (for cashback) and non-Amex credit cards (for Section 75), I’ll probably just swap my Curve for my Chase card in my wallet.
It’s still a decent bet as a backup for travel abroad, though I’d encourage you to prioritise a completely fee-free card first.
So perhaps X, Black or Metal are better options?
It’s hard to justify £60 a year for the still limited features on Curve X. The main concern for me is the loss of using a business payment card but I doubt that applies to many of you. And I can just add that card to my Apple Pay instead. So it’s a relucantant no on X.
If you’re going to take full advantage of the cashback with the Black and Metal cards then perhaps you’ll eat into some of the fees – though it won’t be much.
I think Curve Cash is only a decent feature if you can use it in combination with a non-Amex cashback card and earn double cashback rather than instead of. But this extra cashback alone still won’t cover the full £10 or £15 a month.
To justify the charges you’d need to also factor in the travel insurance – as long as you actually need annual cover. If you do use both cashback and the insurance then perhaps £10 a month isn’t too bad.
But taking it a step further for Metal only really works for me if you need the added phone cover and pay £150 upfront. But even then it’s not something I’d personally go for.
Good news for anyone who signed up for Chase Bank’s current account as the 1% cashback will be extended – though you’ll need to add more money to your account each month. Here’s what you need to know.
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
When will Chase’s cashback now end?
Since launch, Chase Bank has offered new account holders 1% cashback for 12 months, which is activated when you open the account.
It’s already been extended twice. Those who opened the account before 1 March 2022 were able to keep earning cashback until 28 February 2023, and then last year another year was added on to at least 31 March 2024.
And now it will continue indefinitely, now called “Everyday cashback”. It applies to all customers, new and old, though it only begins once your current offer ends.
You’ll still be capped at £15 of cashback a month, but there are changes to the qualifying conditions this time around.
How to extend your Chase cashback
You don’t need to activate the offer in the app as it’ll automatically start when your current 12 month offer ends. For those who’s cashback is due to end on 31 March 2024, you’ll keep earning as normal until the end of the month as long as you deposited £500 in February.
But from 1 March that monthly requirement is going to increase to £1,500 a month. As long as you do this, you’ll earn your 1% cashback on spending in April. You’ll then need to add the same amount in April to get cashback in May, and so on.
If your offer doesn’t end until later, say 18 September 2024, then the new rules will apply from 19 September 2024, meaning you’ll need to have paid in the higher £1,500 in August.
The money has to come from an external source, and can’t be an internal transfer between your different sub-Chase accounts. Refunds also won’t count.
This time it can also be added to your Chase savings account as well or instead of the current account. At the moment this pays 4.1%, which is decent but can be beaten with more than 5% available elsewhere.
Don’t worry if you don’t have £1,500 a month to add in one go as the terms and conditions don’t state this must be a single payment (we’ve had this confirmed by Chase too). That means you’ll be able to hit this threshold in increments. In fact, you could add a smaller amount, withdraw it to a different account, and pay it in again, and both deposits would count towards the total.
This will apply to all existing customers once their existing cashback offer ends. However, new customers signing up won’t have to do this until their first year is complete.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
How much cashback can you earn?
The 1% rate remains the same, as does the £15 monthly cap. This means you’ll only get it on spending of up to £1,500 each month. That’s pretty generous for most everyday spending as there are already some exclusions.
However, you will likely miss out if you are making a large purchase – though since it’s often wise to use a credit card for anything really expensive to get additional consumer protection.
Where to earn cashback with Chase
You’ll get 1% back on most purchases made with your debit card, but there are some exceptions.
You won’t get the money back from financial transactions, such as clearing credit card bills, paying tax bills, buying crypto and cash withdrawals.
Also exempt are things like hospital bills and vehicle purchases. You can see the full list here.
The 1% rate is the best rate out there for most purchases. Though you might get a slightly better rate on retailer specific cards, they tend to offer much lower cashback when you spend elsewhere.
The only other card offering the same 1% is the American Express Nectar card, offering 2 points per £1, with each point worth 0.5p at Sainsbury’s, eBay and Argos. However in year two this card has an annual fee that needs to be factored in.
It’s also worth checking if you’re eligible for any welcome bonuses that could make your spending much more rewarding. Personally I’d wait until these are boosted so you earn even more, though you might also need to time them for when you have larger amounts of spending.
Cashback credit cards can also be better when you’re buying items costing more than £100 as you’ll get improved consumer protections.
Is it worth adding the fee-paying extra to your Barclays current account?
Barclays customers generally get a poor deal for bonuses and freebies, and the Blue Rewards scheme has been pretty poor compared to other banks.
You get a 4.87% AER rate on savings and free Apple TV+. I’ve taken a look at whether it’s worth signing up.
What are Barclays Blue Rewards?
Barclays Blue Rewards is an add-on you can choose to put on your Barclays current account. You’ll need to pay a monthly fee, which is currently £5 a month. This makes it one of the most expensive add-ons for current accounts.
For the monthly amount, you get an exclusive 4.87% savings account and free Apple TV+ streaming, and other benefits come along every now and then.
Barclays Blue Rewards requirements
First, you have to have a Barclays current account. You can’t get Blue Rewards if you already have Barclays Avios Rewards, though you can change over.
Barclays Premier current account holders can no longer add this to their account, though they’ll get the Rainy Day Saver and Apple TV+.
To get the rewards you need to:
Deposit £800 into the current account every month
Pay £5 a month fee
Register for online banking or app banking (app only for new customers from 4 September 2024)
Be over 18 years old
It’s worth noting that the £800 doesn’t need to stay in the account, so you can withdraw it to a different current or savings account (or spend it), straight away.
What you get with Barclays Blue Rewards
Rainy Day Saver: 4.87% on up to £5,000
This Rainy Day Saver offers an exclusive rate of 4.76% gross / 4.87% AER for Blue Rewards members. Though you can hold up to £10 million there, you’ll only earn the rate on the first £5,000.
It’s fully easy access, so you can take out and deposit the money as and when you want. There’s only one account per person, whether that’s in sole or joint names.
To find and open the account in the app, go to the Products tab at the bottom of the screen, click savings, then “see all accounts”. You’ll then see the Rainy Day Saver account to open. You can also open it online, over the phone or in branch.
Interest from savings is paid straight into the savings account, so if you have the full £5,000 saved you’ll want to withdraw the extra on top each month and move it to a better paying account.
Note this is different from the Blue Rewards Saver which pays far less.
Apple TV+ & MLS season pass
A new offer since June 2024 is free Apple TV+, worth £8.99 a month. This alone is worth £107.88 a year, so even with the £60 annual fee, you’re in profit.
However, there are regular free passes for Apple TV+, even for previous customers. I’ve had 25 months free in the last 41 months, and have never paid a penny! And even if you’re happy to pay full price for it, there’s really not enough content on there to justify a whole year.
You can also add on Apple’s Major League Soccer (MLS) season pass for free, which if you would pay for normally could represent a decent saving as it costs £99 for a year.
1% cashback
From September to November 2024 there was 1% cashback on spending with your Barclays debit card. This may return again this year. It was a decent offering but since it was only temporary and can be matched or beaten elsewhere it’s not a reason to sign up for or stick with Blue Rewards.
Exclusive offers
From time to time there are other offers and competitions. The main one to check is up to 15% cashback at selected brands via the Barclays Cashback Rewards feature – though you can also get this for free via a Barclaycard.
Blue Rewards have always been the poor cousin to better schemes from Halifax and Lloyds, and even NatWest/RBS.
The changes in 2024 and the rate drop in 2025 put not just Blue Rewards, but also Barclays, right at the bottom of the pile. When you look at everything you get, you need to decide if £60 a year is worth it.
I think not.
Yes, the savings account could be worth up to £243.50 per year, but you can get similar or better rates elsewhere, especially when you factor in that monthly fee, which brings the effective interest rate down to 3.56% if you save the full £5,000.
First, you need to have a Barclays current account. Once you’ve got this, you need to sign up for Blue Rewards from your online banking or the app.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
How to cancel Barclays Blue Rewards
If you decide you don’t want to continue with Blue Rewards you can easily cancel it in your online or app banking. I did in on the app in just a few seconds.
Open up your app and choose Blue Rewards from the home screen
Scroll down to the bottom of the screen
Select “Leave Barclays Blue Rewards”
Tick the box at the bottom of the screen
Press the “Confirm” button
Any money you have left or pending in the Blue Rewards wallet will be moved to your current account. If you want to re-join, you’ll have to wait at least two days.
Alternatives to Blue Rewards
Barclays isn’t the only bank to offer extras, and many have benefits without having to save any money. You could choose to switch your account to a different bank (and maybe nab a switching bonus) or you can simply open up extra current accounts.
You can also get complete access to your credit report at the same time.
Credit reports and scores are essential tools you need to be aware of – and continue to monitor. A few years ago you’d have needed to pay to access your full report on a regular basis, and even see your score.
But now there are third party websites and apps you can use which won’t charge you a penny.
Here’s why they are important, and how to sign up.
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
The three credit scores and reports
You’d think there’s just one credit score but actually three core ones (let’s ignore for now the fact that lenders might have their own scores too!). Each one is different, and they are based on the date in the credit reports managed by the UK’s three credit reference agencies – Experian, Equifax and TransUnion.
Frustratingly they all have different methods of compiling and presenting their scores. There are totally different ranges, so it’s impossible to compare them.
Now you might think, that doesn’t really matter as you’ll only focus on one report. Well sadly no. You need to check all three reports.
That’s because they potentially hold different details about your financial history. Not every company reports to all three. So you might find your bank or credit card appears on one or two, but not all three.
And that matters because when a lender checks a report to consider your application, they’ll probably just go to one.
And if that one is one with missing accounts or errors it could end up with a rejection.
Credit report vs credit score
A credit report is a collection of information about your finances. From all the bank accounts, loans and other credit you have, through to a record of missed payments, financial connections and address history.
It’s frequently used to confirm your identity, but more commonly it’s a way for lenders to work out if they will give you that mortgage or credit card.
So it’s really, really important – though it isn’t the only thing that’ll be taken into account when you apply.
The score is far less important. It’s simply a representation of the health of your credit report. In itself it won’t make any difference to any applications.
Still, it’s handy for us as punters to get a quick idea of things. And it’s easier to track a score than regularly go through the report.
If there’s a sudden drop in the figure it’s a good idea to try to find out if it’s anything significant that you need to deal with.
But if it carries on relatively steady then you know you’ll only need to take action if you want to bring it up – a sign you’re getting rid of errors and adding depth to your underlying credit report.
You can sign up to each credit agency’s own service to access your score for free. Some banks even bundle this in with your current account. So that’s pretty easy.
But if you want to see your full report (which is the important thing to check), then with both Equifax and Experian you’ll have to pay a monthly fee of around £11 to £15.
Though you can also request a Statutory Credit Report to view online, it’s generally not as detailed, and won’t have your score. So you’re better off using a third party service that’ll give you full online access in a few clicks for free.
They don’t all update in real time (often it’s a monthly refresh), and might not go back more than a year, but you’ll get everything you need right now to check for errors and find areas you might be able to improve. You can also use these sites for additional services, such card and loan eligibility and tracking.
These services will all also email you monthly or when things change. It’s worth clicking through to check when you receive them. This can be an early warning sign of any fraud or applications not in your name. If you ignore these (it’s easy to do when your inbox is full) at least check them before any you make any applications.
Free Experian credit score and report
Experian app
Since July 2025 you’ve been able to get digital access to your Experian report via the Experian app.
There’s also an eligibility checker. This is vital when you are looking to apply for a new credit card or loan. Here’s more on how they work.
You get an update to your report once a month which should be fine for most people. Since Experian is the biggest credit reference agency it’s probably the most important one to keep an eye on.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Free Equifax report and score
ClearScore
ClearScore is a free way to monitor your Equifax score for life. It’s simple to find your way around it and it explains what you’re seeing.
You can access on desktop or via an app. I like the timeline feature which lets you see how your score, as well as things like mortgage debt change month by month.
Again it updates monthly, but for most that’ll be fine.
A warning – ClearsScore will email you regularly trying to get you to open a new credit card or loan. Just ignore the products they try to sell you!
Free TransUnion report and score
Credit Karma
It’s completely free to check your full report direct with TransUnion. You can do this via their own Credit Karma website. Your score is updated weekly.
Check all three credit reports
If you’ve been a victim of fraud and you’re worried about applications going out in your name then you can also sign up to CheckMyFile.
This is free for 30-days, but it will give you full access to all three reports including those instant notifications of changes. If you don’t want to keep the service you’ll need to cancel to you don’t pay the full £14.99 a month.
Earn cashback to check your score
Cashback sites TopCashback and Quidco will pay you to sign up to Experian’s free site.
Rates can change so it’s worth checking both, but at the time of writing the amounts are listed below.
When is your credit rating good or bad? And what does it mean?
I’ve got four different credit scores. 1,245, 999, 970 and 671. Is one better than the other? You’d assume that since 1250 is highest, that’s my best one. And the lowest at 671 needs some work.
But all are actually classed as “excellent”. And the 1,250 and 999 are from the exact same data – but with different ranges.
So it’s clear that it’s not a simple case of saying the higher the number is better!
In this article I’ll help you get an idea of how good your score actually is, and how the different classifications of bands could impact your changes of borrowing money and applying for credit.
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
The problems with credit score ranges
The main issue with credit scores is there isn’t just one. In fact there are three different companies providing scores, and they don’t all use the same data about your finances.
Another problem with credit scores is they’re calculated in completely different ways. You can’t really use a number to say if it’s good or bad without the wider context such as the range that number is taken from. Some are out of around 1,250, others out closer to 700.
And, to complicate it even more, the companies you apply to don’t actually use these scores! They access the data behind the scores from the credit reference agencies alongside any information you provide. They also look for different things depending what you’re applying for.
So clearly it’s not always so obvious what a good score is and to know whether you’re going to be accepted for whatever credit youre applying for.
What credit scores are excellent, good, fair and poor?
Here’s how the three different credit reference agencies class each score, as well as their own ranges.
Experian
Experian is the biggest of the agencies. They score out of 999, but are changing to out of 1250 by the end of 2025. Accounts are gradually being moved to the new system from mid-November.
However, some bank apps that show you your Experian score will use the old range, out of 999.
Experian credit score ranges (new system)
Excellent 1,121-1,250
Very good 1,001-1,120
Good 861-1,000
Fair 641-860
Low 0-640
Experian credit score ranges (old system)
Excellent 961-999
Good 881-960
Fair 721-880
Poor 561-720
Very poor 0-560
Paid advertisement
What Experian’s changes mean for you
There’s a good chance the new larger range will mean you move up or down a tier. Experian say two in five (42%) will see an increase in score or band.
However, a similar number (44%) will go down a band. The rest will be in the same band but see a lower score (for instance they were 999 on the old system, but aren’t 1,250 on the new one).
The big thing to note here is if your score or band is worse under the new system, it doesn’t actually mean it’ll be any harder to get credit when you apply.
Experian told me that you’ll be able to see if recent action has impacted your new score, so you’ll be able to tell if a drop is down to the new bands or something else.
The new scores also take into account things that previously were missed off. This includes positive actions such as rent payments, overpaying mortgages and clearing an overdraft. Negative impacts that could now be reflected include taking money out with a credit card.
You’ll notice too that Experian has swapped “poor” for “low”. This is because they found the old wording discouraged people from trying to improve their score.
Equifax
Equifax changed their range from 1-700 to 1-1,000 back in 2021.
Equifax credit score ranges
Excellent 811+
Very Good 671-810
Good 531-670
Fair 439-530
Poor 0-438
Transunion
TransUnion, which you can access for free through Credit Karma, scores out of 710.
Transunion credit score ranges
Excellent 628+
Good 604-627
Fair 566-603
Needs work 1-565
Paid advertisement
What’s an average credit score in the UK?
Experian offers a map where you can break down scores by regions (and age too if you want). For Manchester the average credit score is 743, which ranks as the bottom end of Fair. For Bristol, it’s 805, halfway through Fair, while Tonbridge in Kent comes in at 844, near the top of Fair.
How important is a credit score?
The most important thing to say here is credit scores don’t actually mean anything definitively. They’re an indicator of how good or bad your credit report is (I’ve explained more in this article about credit reports).
But this isn’t the only information lenders take into account. Extra details you provide, such as your salary, could help or hinder your chances of acceptance. In fact, they won’t even see this score, and will create their own version of it based on their own criteria, the info on your credit report and the extra details they have.
Really the number itself is pretty meaningless, except to measure your progress when trying to improve it. If you see it go up you know you’re doing the right things.
If you see it dip then it could be a sign you need to take some actions – though it’ll always fall a little after a new application and will right itself after a while.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Paid advertisement
What do the different credit score ranges mean?
Really it’s probably better to look at the category your credit score sites in. Broadly scoring in the different ranges from excellent down to very poor is likely to mean the following:
What an excellent credit score means
Across the agencies “excellent” suggests you’ll probably get accepted for most types of credit and be offered the best rates and deals. But there’s no guarantee and you could still get rejected when you apply.
What a very good credit score means
A “very good” credit score indicates you will usually be accepted for credit, though you might not get the best deals.
What a good credit score means
A “good” score means there is still a decent chance you’ll get accepted but you won’t get the best deals or rates. For example, you might get a lower credit limit or a shorter 0% period. It’s even more important to use soft checks, particularly on credit card applications, to find out who will accept you.
What a fair credit score means
An “average” or “fair” score likely means your options will be more limited, and subject to higher interest rates or lower credit and borrowing limits.
What a poor / low / needs work credit score means
If your score is classed as “low”, “poor” or “needs work” – and it’s likely you’ll be seen as high risk to lend to therefore far less likely to be accepted when applying for credit, or only be able to get products with high interest rates.
Good news! You don’t need to pay to check your score, or more importantly, your credit report. We’ve written more detail on the free credit report sites here.
Here’s where I’ll post any particularly decent eBay deals and offers, whether selling or buying!
As you’d expect there are thousands of different products! Often you’ll see well-known shops selling on eBay now at prices less than their own website. Office and Argos are just some with “outlet” shops on eBay.
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
Buying offers
20% off on eBay
Another eBay deal, this time offering 20% off a huge variety of retailers. The code for 20% is MERRY20. The code expires at midnight on 16 December 2025.
There’s a minimum spend of £9.99 and the max discount is £75. The code can be used three times.
Do always price check elsewhere before buying though as they could be cheaper even without the discount.
You can get an exclusive £20 new member bonus. You need to spend £10 via one of the retailers listed on TCB to get this bonus, and that includes eBay. You must go via this link or the button below.
Read the full terms and conditions when you click through. Ends 31 March 2026.
The best Quidco deal is for subscribers to our free newsletter who get access to an exclusive £20 first-time bonus when they spend £10. Though you can use this at any shop, it also includes eBay. You’ll also get the cashback offered on top.
Once you sign up, you’ll need to click on the sign-up confirmation email that will be sent immediately. If you don’t see it, please check your spam folders as it could be there, and then add our email address to your safe senders list.
Then look for a special email that will be sent to you with the exclusive Quidco sign-up link. Make sure to read the terms and conditions on Quidco’s website before making your first purchase to ensure it tracks.
This offer is due to end 31 December 2025, but will hopefully be extended.
Everything you need to know to save money when going to a show
A trip to the theatre isn’t a cheap night out. Tickets for Hamilton go as high as £250. That’s for one ticket. Crazy prices. But there are ways to see West End and local theatre productions for less.
I obviously don’t pay that kind of price. Yes for the hottest shows that means I might go without, but there are plenty of ways to see top-quality West End and local theatre productions for less.
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
Hunt out the best deals
There are some big sales throughout the year which are always good bets. The biggest – Get Into London Theatre usually takes place from December to March, while Kids Week is every August.
Ad hoc sales and offers pop up on TodayTix, while TimeOut has the occasional deal (it used to be better). There are sometimes flash sales at Ticketmaster too. Lastminute.com isn’t as good as it once was, but it’s worth a look.
Generally, avoid sites like TasteCard+, which offer money off tickets as part of the membership. Each time I’ve looked the deals can be beaten elsewhere or aren’t even discounted at all.
When there are any really good deals on lots of productions, I’ll list them on my theatre tickets deals page.
Pay with discounted gift cards
This trick won’t always work – sometimes the best prices are on sites that don’t accept gift cards (e.g TodayTix). But there are often deals to save here or there on the likes of Ticketmaster and Theatre Tokens.
Thanks to this I managed to get 50% off seats at rarely discounted shows Cabaret and Hamilton (though sadly it’s rare to see such a huge per cent off).
Choose the best value seats
If there’s a play I want to see my first stop is often always the excellent Theatre Monkey. The website provides seating plans for each theatre, with crowdsourced feedback from readers telling you which seats are good value, and which are bad. Often a ticket might be cheap because you can’t see half the stage!
Paid advertisement
Get a cheaper day or rush ticket
A number of shows offer reduced tickets on the day, often called rush or day tickets. Sometimes these have been held back for the day, or they could just be returns. For the really popular shows this is a great way to get tickets.
It used to be you’d have to rock up at the box office very, very early. But now most of these are sold online. Theatremonkey has a list of how it works for each show, along with reader feedback on success rates for those queuing in-person.
However, the majority will be sold through the TodayTix where you unlock “rush tickets” at 10am. Most cost £25, but could be as low as £15.
The seats could be anywhere in the theatre, from restricted view through to the the top-end VIP seats. It’s first come first serve, though I’ve managed to get tickets as late as 5pm (obviously not for the most popular shows).
Some theatres have larger numbers of reduced tickets on set days. Over at The Royal Court there are cheaper seats every Monday (on sale 9am online on the day).
Try a lottery
Lotteries for plays can get you cheap tickets to performances, even the most popular and sold-out shows. However, as the name suggests, it’s a lottery as to whether your name is chosen to buy the tickets.
Over the years I tried for shows like Book of Mormon, Harry Potter and the Cursed Child, Hamilton and Cabaret – with no success!
They used to take place at the box office. You’d just turn up at the box office a few hours before the show and give your name… and hope! Now most are online.
More often these are also run via the TodayTix app. Some still offer them on their own websites such as the one for Matilda or The National Theatre’s £10 Friday Rush promotion.
Check in advance what the rules are. Some take place once a week for all performances the following week, others are daily. There’s usually a cut-off time to submit your entry and if you’re successful you’ll likely only be able to buy two tickets.
Be a seat filler
I’ve nabbed dozens of free tickets for my parents through sites like Show Film First and Central Tickets often for big West End shows. The reason? Theatres want to fill up the seats.
This tends to happen at the start to help spread word of mouth, or near the end of a run when less people are going. There’s usually a £4 to £10 fee per ticket – a fraction of the actual ticket cost. Here’s my guide to how seat filling works.
The Twickets website is a great place for people to sell on seats they can no longer use. Though sellers can’t inflate the selling price (it’s an anti-tout company), there are Twicket fees on top, so it’s always worth checking you can’t get the ticket for less direct.
However, the closer it gets to the performance date, sellers can reduce their asking price or allow offers. So if you can go last minute you might be able to nab a bargain. At the time of writing I spotted Matilda and Phantom tickets for this week’s performance going for below face value.
Go to theatres with special rates
The National Theatre offers hundreds of tickets at each performance at just £25. They go quick but you can sign up for alerts.
Meanwhile, The Globe has 700 £5 tickets for every performance (though they are standing) and The Young Vic has £12 Lucky Dip standing tickets that could be upgraded on the night to an empty seat.
You can of course avoid the West End and see something on the fringe, which will be much cheaper. The Arcola has a “Pay What You Can Tuesdays”, with a suggested price of £5.
Visit the official theatre booth
From when I was a kid through to just a few years ago I always used to head to the official TKTs Theatre Booth in Leicester Sqare to get my tickets (as long as I was flexible about what I saw). Unsold tickets for that day’s performances were often half-price – though there was usually a queue.
Recently the prices don’t seem as competitive as they once were, but they’re still worth a look if there are a few London shows you’d like to see. Don’t confuse it with other “discount theater booths” nearby.
And you don’t have to visit in person now. Last year I picked up tickets online to Dear England on the train down to London for that evening’s performance.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Paid advertisement
Go to a less expensive performance
If you can go on a midweek afternoon – usually a Wednesday or Thursday – you’re more likely to find availability in the cheaper seats. The same goes for evening shows at the start of the week.
Previews are often discounted as they’re essentially ticketed dress rehearsals. Most shows will be cheaper. However with full prices already so high, you could still pay a fair amount.
Cut your booking and delivery fees
A good way to save is to collect your tickets at the box office on the night of the show. If there are no special deals or discounts, head to the theatre box office where you can normally avoid booking fees too.
If you can’t do this and have to buy online then do shop around as you might find See Tickets is cheaper than Ticketmaster for one show, but more expensive for another!
Buy a cheap seat and ask for an upgrade
Buy a ticket in the cheapest part of the theatre – usually at the top of the upper circle or similar then you could be automatically upgraded. For less-busy shows these parts of the theatre are often closed and the tickets redistributed.
I’ve had this happen a few times. A few years ago I bought £10 tickets (to Let The Right One In) via Lastminute.com. They were meant to be restricted view in the top circle level, but when we arrived we found we’d been upgraded to £50 stalls tickets to fill those seats (the circle was completely closed).
This is more likely to happen on less popular productions in larger theatres for performances happening earlier in the week.
If that hasn’t happened automatically and the theatre isn’t too busy, you can always ask when you collect your tix. Or just see if you can move in the interval – though you might be asked to move back by staff.
Ditch the West End
Yes theatre does exist outside central London! There are lots of top theatres, especially in Sheffield, Liverpool, Manchester, Stratford-upon-Avon and Chichester.
Plus, many shows will tour the UK before moving to the West End, or will be revived a few years later. Seats will pretty much always be cheaper this way.
Watch it at the cinema or at home
If you’re not in London or can’t afford West End prices even when they are on offer, then your best chance to see the top plays is in the cinema. Tickets generally range between £15 and £20.
And there are streaming services that allow you to watch productions from your sofa.