It’s generally cheaper per month and you only need to commit on a month by month basis.
Despite this I think you should cancel NOW TV every month – even if you want to carry on watching.
Here’s why, and how to do it.
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
Rather watch than read? Here’s my video on cancelling NOW TV
Please do click through to my YouTube channel to like the video and subscribe.
Cancelling because you’re not watching
Of course, cancelling NOW TV is a given if you aren’t watching it. You’re not saving money if you’re paying for something you don’t need.
But even if you are using it, it might not be enough to justify the price. We have so many streaming options that I think we don’t need more than one or two in any given month.
Any more than that there’s a good chance we just won’t watch more than an hour or two of our third or fourth option. If that.
So it’s better to pick and choose your service, and binge watch the ones you are paying for. Then switch to a different one the following month.
Bonus requirementsTo get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
Regular saver8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
Existing customers?You can't have held a Santander account on 1 January 2026.
There are lots of ways to save money on NOW TV passes, though there are less than there used to be (here’s our regularly updated list of deals).
In fact, I never pay full price for a NOW TV pass. I rarely, if ever, pay more than 50%. And the easiest way to find a discount is to cancel.
When you go through the process (see the video above) the final page you get will usually offer you a discount for your next pass. It could even say that offer will last for longer, say three or six months.
Sometimes these are cracking deals, with huge savings. I’ve had £1.99 a month movies in the past, or £2.99 Entertainment. Sometimes they aren’t as good as what you can get elsewhere. And sometimes you don’t get anything.
But it’s always worth checking to see what is there rather than letting it auto-renew at full price.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
How to cancel NOW TV
Cancelling NOW TV is one of the more annoying ones to complete, but it doesn’t take long.
Navigate in your account to your passes, then select cancel. You’d think that’d be it, perhaps asked to confirm you mean to do this.
But you’ll actually be asked something along the lines of “are you sure” two or three times! I know people sometimes think they’ve done it but didn’t complete the process.
The important thing is to make sure you get confirmation of cancellation. This should show on the final screen, but I’d always double check in your account too to make sure it’s gone through.
Catch up on my top articles, podcasts and videos from the last 12 months.
Over the last 12 months I’ve written 172 articles, recorded 64 episodes of my Cash Chats podcast and uploaded 84 videos to YouTube. And that’s not including countless deals posted here on the blog and Instagram!
No doubt even the most regular readers among you won’t have managed to take in all that money-saving and making content. So here’s a look at the highlights that are still well worth a look.
I’ve shared the most read, listened to and viewed over the year, which lends an obvious bias to content produced earlier in the year, so for each category I’ve also shared my personal favourite from the last couple of months.
The blog
It’s been a record year for visits to this site. In total 1.2 million people came to Be Clever With Your Cash reading a total of just over 1.6million pages.
Deals were as ever a huge part of the traffic, but here are the most read articles published this year:
Artificial Intelligence (AI) transfers can help you build up your savings without noticing.
One of the biggest reasons people who try to save but fail is that they don’t prioritise the act of saving.
The money sits in their current account alongside all their other cash, making it hard to distinguish between what’s needed for bills and what is available for other spending.
The easy solution is to set up a standing order to move money to a separate account just after payday, but it’s possible to save even more thanks to fintech innovations.
Using rules and algorithms based on your spending habits, apps like Plum, Chip, Monzo and Starling can automate the transfer of cash from your current account into separate savings pots.
My favourite is the artificial intelligence or AI savings app. I’ve written about Chip before, but now it charges you to use this function, I wanted to take a look at the free alternative – Plum.
What is Plum?
Plums describes itself as “The AI assistant that grows your money”. Though it offers a few extras, it’s primarily about helping you boost money for savings via automation.
It also acts as an entry level investment platform, but I won’t cover this element in the review.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
How much does Plum cost?
There are three tiers with Plum, ranging from free to £2.99 a month.
Basic – Free
Plus – £1 a month
Pro – £2.99 a month
Personally I’d stick with the free Basic option, and that’s what this review will focus on.
Bonus requirementsTo get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
Regular saver8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
Existing customers?You can't have held a Santander account on 1 January 2026.
Plum is an app-only service, so you can’t take advantage of these if you don’t have a smart phone.
You connect Plum with your bank via Open Banking, giving the app read-only access to your account details. It’s a pretty simple process to connect as long as you already have your bank’s app installed on your phone. You need to reauthorise the connection every 90-days, which takes just a few clicks.
It’s possible to add more than one bank, though money will only be transferred from the account you designate. Unlike Chip you can change which bank this is whenever you want.
You can add credit cards too, but these won’t be used for the auto-savings features.
Plum currently works with the following banks:
Barclays
Danske Bank
First Direct
Halifax
HSBC
Lloyds
M&S
Monzo
Nationwide
Natwest
Revolut
RBS
Santander
Bank of Scotland
Starling
Tesco
TSB
Ulster Bank
Autosaves with Plum
This is the big selling point with Plum for me. These features help you build that savings pot without actually doing anything. The money is transferred via a Direct Debit that is set up when you link your account.
To access these savings features you need to find the ‘Brain’ option, which should appear on the home screen once you’ve connected to your bank.
The free tier of Plum has three ways to automatically move money from your bank to your Plum account:
Automatic
Round Ups
Pay Days
The Pro version also has Rainy Days and 52-Week Challenge options but I’ll ignore these here. Mainly because you’ll have to pay, but also because if they’re of interest then they’re available alongside even more options for free via Monzo.
Here’s more on each of these savings rules:
Automatic
This is my favourite of the three. As with Chip, an algorithm analyses your bank account, looking at your balance, spending and forthcoming regular payments in and out.
Based on this Plum works out how much you can afford to put aside. You can also adjust the ‘mood’ of your savings level, from the default option. The lowest level ‘shy’ will reduce that amount by half, while the top level ‘beast’ increases it by 75%.
Money is moved once a week from your connected bank account to your Plum account. You can pause these transfers, or turn them off completely whenever you want.
Round ups
Every time you make a purchase with a linked debit or credit card you can choose for the transaction to be rounded up to the nearest full pound, with the difference moved once a week to your pocket.
Be careful here though as these will continue even if you’re overdrawn, though you can switch this off in the app’s ‘brain’ under ‘overdraft deposits’.
Pay Days
This is essentially a standing order which automatically moves money from your bank account when you get paid. You set the date and the amount.
Personally I’d set up an actual standing order for this and move your money to an account where you’ll earn the best interest right now. Or opt for a regular savings account.
Our podcast
Listen to Cash Chats, our award-winning podcast, presented by Steve Alderton and Editor James Andrews.
The basic free version of Plum offers an interest pocket offering 0.25%.
You can beat this amount right now, but if you are using Plum then it makes sense to turn this feature on and put your cash there. You can choose where your money goes in the ‘brain’ part of the app.
It’s easy-access though if you move money into one of these pockets then you have to give one-day notice to withdraw the cash.
The rate is variable, so it could change (in fact it dropped in late January). If that happens Plum will give you 14 days notice.
The Plus and Pro versions increases this to 0.4%, but you’ll likely spend more to upgrade than you’ll make with the increased interest rate. For example, £1,000 at 0.4% for a year earns you £4. That’s £1.50 more than the Basic account, but at a cost of £12 (Plus) or £35.88 (Pro).
Is your money safe?
Any money in your main Plum ‘Pocket’ is held in something called an E-Wallet, meaning it’s not covered by the Financial Services Compensation Scheme. If something was to go wrong, or if Plum went bust, your money should still be fine, as it’s actually held at Barclays. But if Barclays went under then you’d lose your money.
The savings accounts are with Investec Bank and these are protected by the FSCS. It’s only up to a total of £85,000 and that’s across all accounts you might have with Investec.
Other features
The app also offers a handful of extra features on the basic option.
Free features
The Lost Money tab is the only significant extra on the Basic Plum account. It’s meant to analyse your bills to highlight where you’re overspending. However, since it can only see your payments, it’s not really that useful.
And though it’ll send you through to a comparison site to help you find better deals, you can do that yourself without the aid of the app.
Other paid features
I don’t think any of these are worth upgrading for, but just so you know what is on offer
Plum Plus
Access to 0.4% interest account
An extra Easy Access Interest pocket
The ability to use Plum Investing
Plum Pro
Cashback
Budgeting tools
Unlimited pockets
52 week challenge and Rainy Day savings rules
Plum alternatives
You can get the AI algorithm savings feature with Chip and Cleo for a monthly fee. Tandem did offer this but has closed the feature.
Round up savings are more and more commonplace now, with Starling, Monzo, Nationwide, Lloyds and others offering this.
Monzo also offers you the option to automate the Pro savings features such as savings challenges, moving money if it rains and much more – and it won’t charge you for it (more on this here).
The PayDay feature is essentially a standing order which can be set up between any two bank accounts.
Conclusion
I’m a huge fan of auto-savings algorithms, and now that both Chip and Cleo charge for this, Plum is my top pick.
Link up your main current account and set the “brain” to the savings rules and levels that work for you, and you should slowly but surely see the amount saved grow.
Of course you’re not earning much right now with this account so you might want to move the money on a regular basis to one that pays a little more.
I’d stay clear of the paid versions – you don’t get enough extra for your money – and the other features don’t really offer much.
How do Starling and Monzo compare to the apps from the high street banks?
App banking is getting bigger and bigger. I very rarely log in to online banking on a computer, hardly ever visit a branch and only phone up when there’s a problem.
So it’s vital that I can do everything I need to do on my app. And sadly my main bank for years – Nationwide – is really limited, requiring a card reader to add new payees and missing many of the features that started on new digital banks but increasingly copied by established banks.
I’d go as far as to say that how good a bank’s app is the number reasons to choose a bank for your everyday banking.
Watch my full analysis in this video, or keep reading to see the features broken down app by app.
Bank features compared
I’ve compared the features on 13 different banking apps, from digital challengers Monzo, Starling and Revolut through to high street titans Barclays, Halifax and HSBC.
So, what do I look for in a banking app? There are all sorts of things you can do – from adding photos of your receipts to individual transactions through to paying in a cheque. Lots of nice to haves.
But there are some basics which are essential – and surprisingly not all banks offer them. Here’s what I’ll check if I am going to use an app.
How easy is it to use?
Ease of use and being able to find everything are really important. Of course the more you use an app, the more familiar it’ll be, but there are some apps which are better than others
Can I set up new payees and amend existing ones?
I hate it when an app won’t let me do everyday things such as set up a new payee or amend a standing order. These are essentials that mean I’ll be able to do the basics whenever I want.
Sometimes there are payment limits on large transactions, largely to combat fraud, and I’m ok with these. It’s rare I transfer big sums so it’s only an occassional inconvenience.
Does it offer instant notifications?
More banks now offer this on their apps, and it’s a handy budgeting feature. You’ll get a notification on your phone as soon as the payment processes allowing you do check the amount is correct and also get aheads up of any fraud.
Can I search old transactions?
I want an app that’ll go back for at least 18 months and also offer filer options such as payments in or out.
Can I copy my account details?
This innovation is simple but so useful. With a couple of taps I can copy by account number and sortcode to share with people, or to enter into direct debit forms.
Does it let me control the card
Finally, it’s essential that my banking app lets me freeze my card. This is a security measure where you can stop anyone using your card if you lose it.
Extra app features I love
I’m a happy camper if the app contains all of the above, but there are extras offered by some banks which you might not be aware exist.
Of course, just because a bank app does something all shiny and new, it doesn’t mean you need it.
The biggest one here is being able to add other bank accounts to your app dashboard via Open Banking. This is a great idea, but the banks that do offer it only allow you to connect to a small range of banks.
You’re better off going for an app that is designed for and allows you to connect credit cards such as Yolt or Money Dashboard.
Similarly the auto-savings feature you’ll see with most banks (except Monzo) is a variation of the “Save the change” or “top-up” method where small amounts are transferred from your main account to a savings pot when you spend. There are better options out there, such as those from Plum and Chip.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Bonus requirementsTo get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
Regular saver8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
Existing customers?You can't have held a Santander account on 1 January 2026.
Allied Irish Bank Bank of Scotland Barclays Danske Bank First Direct First Trust Halifax HSBC Lloyds Monzo Nationwide NatWest RBS Santander Ulster Bank
Instant notifications
Yes
See upcoming regular payments
No
See pending payments
Yes
Go back more than one year
Yes
Filter in/out
Yes
Download statements
PDF
Add receipts/notes
No
Management
Freeze card
Yes
See Pin
No
See card number
No
Order new card
Yes
Gambling blocks
Yes
Spending controls (eg block contactless)
Yes
Update personal info
No
Biometric log in
Yes
Extras
Get cash
Revolut
Savings
Savings pots
Yes
Auto savings
Yes
Banking
Easy transfer
Yes
New payee in app
Yes
New SO
Yes
change SO
Yes
pay in cheque
No
share account details
Yes
Budgeting
Analyse spending
Yes
Set Budget
Yes
Add other banks
Yes
Amex Bank of Scotland Barclays Danske First Direct HSBC Halifax Lloyds M&S Bank Monzo Nationwide Natwest RBS Santander Starling TSB Ulster Bank
Instant notifications
Yes
See upcoming regular payments
Yes
See pending payments
Yes
Go back more than one year
TBC
Filter in/out
TBC
Download statements
PDF, XLS
Add receipts/notes
Yes
Management
Freeze card
Yes
See Pin
Yes
See card number
Yes
Order new card
Yes
Gambling blocks
Yes
Spending controls (eg block contactless)
No
Update personal info
Yes
Biometric log in
Yes
Extras
Virtual Card
Group bills
Santander
Another app I don’t currently have access to so there are a handful of gaps.
Here’s how to manage direct debits and cycle money to get current account perks.
It’s a good idea to have more than one current account, but with each extra account comes more admin. The good news is that most of the task can be done in one go early on, and then looks after itself! Here’s how I do this for all my accounts.
Current account admin
From cashback to monthly rewards, there are all sorts of incentives and freebies you can get with multiple current accounts. And don’t forget bank switching bonuses.
But many account switches and perks require extras like direct debits or minimum deposits each month. They also have fees and other requirements. Get them wrong and you could miss out or even lose money.
All this can put some people off. But it’s actually a lot easier to manage than you’d imagine, and I think the reward is well worth the effort.
Regular readers will know I have 15 different current accounts at the moment so I’ve got to have processes in place to make sure I don’t accidentally go overdrawn on one or miss out on a perk on another.
Minimum transfers
Many accounts require me to pay money in every month. If I didn’t I could miss out on all those little bonuses or get charged a monthly fee.
The good news is the money doesn’t need to remain in the account, and in most cases doesn’t need to be in one go, so you can hack this by moving the same money through all the accounts. Still that’s potentially a lot of transfers to process, which can take time.
If you have more than two or three accounts, then automation is the key. Set up standing orders to move the money on the same day each month. You can do this easily in your online or app banking.
If you do have multiple accounts with the same provider, transferring between them often doesn’t qualify (eg Halifax to Halifax), so you’ll need to factor this in.
Remember, it’s not just minimum deposits you need to cover here. There are those account fees, and in some cases you’ll want to be adding money to regular savers each month, so they need to be factored in.
There are three methods here:
The endless cycle
One trick is to move the same cash from account to account so it cycles through each one and back to the start, then repeats itself the next month and so on.
For example, you’ve got £2,000 in account a, which you transfer to account b, then to account c, then account d and finally back to account a. Then it repeats the next month, and so on.
The back and forth
Another option is to set up a standing order out of one account into another, and then back the next day. And then move the money into another account and back.
So you’re move £2,000 from account a to account b, then back to account a. Then move £1,000 from account a to account c, then back to account a. And so on.
It makes sense to spread these out through the month so you’re still only moving the same amount of cash. to make sure there is cash in the account to leave it in the first place.
The bitesize transfer
If you don’t have a large amount in your account to keep moving around, you can split the requirement into smaller chunks.
You can use either the endless cycle or back and forth methods to automate this – you’ll just have more standing orders in action.
Let’s say you have an account requiring £2,000 each month, you could use the same £500, and just deposit it and withdraw it four times to total a cumulative £2,000.
Account fees
Reward accounts are great – though you normally need to pay for them. As long as you’re making more that you put in then they can be worth it.
Direct debits
Quite a few switching offers and perks require a couple of direct debits each month. Often it’ll say ‘active’ direct debits, which technically could include any payment that has been taken in the last year.
But for the most part these direct debits have to come out every month to qualify – ruling out annual or quarterly payments.
First Direct: £250 interest free buffer and 7% regular saver
Making sure everything is OK
The standing orders and direct debits should all take care of themselves, but I’ll always check in. In part that could be required to trigger a reward, or to claim the perk itself.
But most importantly it’s to ensure nothing has gone wrong and there’s no risk of going overdrawn. I’ve set up two spreadsheets to keep an eye on things.
The first tells me all the standing orders and direct debits in and out of each account. If I need to amend the size of a standing order (for example when switching banks), I know exactly which is which. It only updates if I change bank.
The other spreadsheet is more active. Every month I open up the apps for my accounts and write down the balances. I try to do this in the first week of the month. This way I know exactly how much I have in each account, and overall.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
What each account requires
Minimum transfers
These accounts that require a minimum deposit each month to trigger perks. Remember some bank switch offers might also require this.
Account (a-z)
Perk
Monthly deposit required
Barclays Blue Rewards
Free Apple TV+
£800
Bank of Scotland Vantage
3% interest on £4,000 to £5,000
£1,000
Chase
1% cashback on groceries and travel spend
£1,500
Halifax Rewards
No fee
£1,500
Club Lloyds
Free Disney+ w/ ads or 6 cinema tickets and no fee
£2,000
Nationwide FlexDirect
5% interest and 1% cashback (year 1 only)
£1,000
NatWest Reward
£2 reward after fee
£1,250
RBS Reward
£2 reward after fee
£1,250
Santander Edge
1% cashback on bills
£500
Account fees
You’ll need to pay a monthly fee to have the following accounts, though in a couple of cases you can avoid paying this.
With 47% of employees having worked from home in 2020, there’s a good chance you’re able to claim between £62 and £140 in tax relief.
If you’ve been required to work at home at all in the last year then you are eligible to get back some of the tax you’ve paid. You can do this for the whole 12 months even if there was only one day where this happened!
It’s also really easy to do thanks to a microsite set up by HMRC to process it for the 2020/21 tax year.
Update – And you can also now claim in the same way for 2021/22!
Most people are looking at receiving £62.40, though those who pay a higher rate of tax will be doubling that. A handful will be able to get £140.
Keep reading for everything you need to know about who can claim and how to do it, or watch this video with a step-by-step guide to applying.
What is working from home tax relief?
The logic behind this is you will have incurred extra household expenses while at home – from heating to insurance.
Who can claim?
Normally you can only claim for the weeks you’ve actually had to work from home. But that’s different for this last year.
You only need to have been required to work from home for one day since March 23rd 2020 (when lockdown began) to get the rebate for the entire 2020/21 year, and again for the 2021/22 year.
However, if your employer has already covered extra expenses you aren’t eligible. Also, you shouldn’t claim if you have chosen to work at home.
How much can you claim?
The tax relief is dependent on a few things – largely what you are claiming for and the rate of tax you pay on your income.
You can work out exactly how much extra you’ve spent on permitted expenses to claim the exact amount of tax back, but you do need to have receipts or proof of the extra costs.
What’s probably easiest for most people is to go with the set allowance. For the financial years 2020-21 (April 6th 2020 to April 5th 2021) and 2021/22 , it’s set at £6 a week. For previous tax years the rate is £4.
It doesn’t mean you’ll get £6 back for every week. Instead you’ll get the tax back on that £6, which works out as follows:
Basic rate taxpayers (charged 20% tax on most of your income) will get 20% of £6 back – a total of £1.20 a week. That’s 62.40 a year.
Higher rate taxpayers (40%) will get double that at £2.40 a week. That’s £124.80 a year
Additional rate taxpayers (45%) will get a little more at £2.70 a week, and £140.40 a year.
How will you get the money?
You won’t receive the money as a lump sum to your account or as a cheque. Instead, your tax code will be altered to accommodate this extra allowance. So essentially claiming really this means you’ll pay less tax each month.
How to make a claim
To make things easier there’s a government “microservice” most people can use. This uses the set £6 weekly allowance.
However this shortcut is only for those who don’t already fill in a self-assessment form. Those people will have to wait until they fill that in for that full tax year once it ends.
You can also claim for previous years but only for the days you were at home, and not via the microsite.
You’ll be asked:
Are you only claiming tax relief on your expenses for working from home? (Answer “Yes”)
Do you complete Self Assessment returns? (Answer “No”)
Has your employer paid your expenses for working from home? (Answer “No”)
Did you start working from home because of coronavirus (COVID-19)? (Answer “Yes”)
To make the claim you need a government gateway ID and password. This should take 10 minutes online. You’ll need your National Insurance number and either a payslip/P60 or your passport.
Once you have this you simply log in and follow the instructions. Don’t forget to claim from 23rd March 2020 if you were working from home then too.
What about 2021/22?
Money Saving Expert reported on 6th April 2021 that the microsite will carry on working for the new financial year, and you’ll be able to claim once more for the full year even if you only worked from home once.
If you didn’t claim for 2020/21 then you can still do this on the site.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Is it worth opening multiple current accounts to earn monthly rewards?
I’m a bit of a bank account geek, and have tried and tested most of the UK ones – often as part of nabbing a switching bonus of £100 or more.
But these cash incentives aren’t the only way to make money from your account. There are quite a few which will give you a smaller cash reward every month if you meet certain criteria.
Often that is a requirement to pay in a set amount each month. Sometimes there’s also the need to pay out some direct debits or spend a minimum amount. You might also need to log into your app on a regular basis.
It’s all simple enough. But is it worth the effort? Here’s my take on which ones to open and which ones to avoid. Plus how much you could make if you opened them all up.
The essential reward accounts
If you’re not sure how many current accounts, these are good ones to start with.
With these three accounts combined you’ll make around £160 a year, give or take a tenner since the Santander 123 Lite account cashback value will depend on the size of your household bills.
The Club Lloyds account doesn’t give cash but a choice of “lifestyle benefit” such as cinema tickets or a magazine subscription. I’ve given it a monthly value of £3.50, though it could be more.
Halifax Reward
Santander 123 Lite
Club Lloyds
Reward
£5.00
£7.00
£3.50
Fee
£0.00*
£2.00
£0.00*
Monthly profit
£5.00
£5.00
£3.50
Annual profit
£60.00
£60.00
£42.00
Requirements include
Pay in £1,500 a month
Pay in £500 a month
Pay in £1,500 a month
Spend £500 on debit card
Two direct debits (though five or six to get full cashback)
If you want to take it further you can open up three more reward accounts, each earning you £3 a month after fees. So there’s potentially £108 extra a year from these accounts.
These are definitely worth adding to or upgrading existing accounts you have with the banks to get the cash. But the smaller returns mean you need to weigh up whether you are happy to do the admin required to apply and then manage the accounts.
Barclays Blue*
Natwest Reward
RBS Reward
Reward
£7.00
£5.00
£5.00
Fee
£4.00
£2.00
£2.00
Monthly profit
£3.00
£3.00
£3.00
Annual profit
£36.00
£36.00
£36.00
Requirements include
Pay in £800 a month
Two direct debits of at least £2
Two direct debits of at least £2
Two direct debits
Log into mobile app
Log into mobile app
*changing in March 2022
The final three rewards
These final accounts are for completists only and personally I’ve not bothered with them. They require minimum usage of your debit cards – 30 for each of the TSB accounts and 60 for the Co-operative Bank account. I think that’s too much hassle.
But if you want to go through with these then you’ll get an extra £80 in the first year. The TSB accounts can earn you cashback via Quidco, worth an extra £30 to £60 (and sometimes more) on the first one you open.
TSB Spend & Save
TSB Spend & Save Plus
Co-operative Bank Everyday Rewards
Reward
£5.00
£5.00
£2.20
Fee
£0.00
£3.00
£0.00
* limited to six months
Monthly profit
£5.00
£2.00
£2.20
Annual profit
£30.00
£24.00
£26.40
Requirements include
30 debit card transactions
30 debit card transactions
60 debit card transactions
Four direct debits
Pay in £800 a month
Keep balance above £0
Getting more as joint accounts
If you have someone you can open a joint account with then you can get the rewards again with a handful of the accounts.
It’s probably worth doing this for the Halifax and Club Lloyds accounts, earning an extra £102 a year. I think adding another TSB Spend & Save Plus account makes very little sense as that’s another 30 debit card transactions you’ll need.
Halifax Reward
Club Lloyds
TSB Spend & Save Plus
Reward
£5.00
£3.50
£5.00
Fee
£0.00
£0.00
£3.00
Monthly profit
£5.00
£3.50
£2.00
Annual profit
£60.00
£42.00
£24.00
Requirements include
Pay in £1,500 a month
Pay in £1,500 a month
30 debit card transactions
Spend £500 on debit card
Keep balance above £0
Even more accounts for your partner
And if you’re opening accounts with someone else, they can obviously also open up their own accounts. It’s not quite the same list as for you as there’s no point having a second Santander 123 Lite account (you can’t earn cashback twice on your bills), which brings the most they’ll earn for opening a Halifax Reward, Barclays Blue, Natwest Reward, RBS Reward and Club Lloyds down to £210.
How much you can make?
Obviously it depends on how many accounts you open, and whether you’re also able to open up those extra joint accounts.
But sticking with those first six account will get you £270 a year. Add in a second (joint) Halifax Reward and Club Lloyds boosts that to £372.
And if the person you have the joint account with opens those same ones except for Santander 123 Lite, you’re looking at another £210 and a total of £582 a year.
If you wanted to go extreme and add in the TSB Spend & Save, TSB Spend & Save Plus and Co-operative Bank Everyday Rewards you could add on another £80 for your own accounts, and another £50 for joint accounts.
Andy’s analysis
These rewards are great ways to earn extra cash every year, and in the most part pretty easy to manage. But they’re only worth opening if you feel the return is enough.
That could mean you just stick with the first three accounts and only look at others if there’s an extra reason to open one, such as a bank switch offer.
Still, even I draw the line at the TSB and Co-operative Bank accounts. if you already have them and use them as your main account you might find it easy to meet the debit card transaction requirements. But I’d argue you’re better off switching that account to a different bank for a reward that takes less effort!
Meeting the reward requirements
I’ve said it’s easy to have more than one of these accounts, but you do have to make sure you meet the different requirements.
As I’ve written about elsewhere, this can be quite simple – even automated. Do read my full guide which also shares tips to help you find extra Direct Debits.
Make even more money from your bank
If you open up any of these accounts, make sure you also take advantage of other benefits. The Natwest and RBS accounts, for example, make you eligible for a 3.04% paying regular saver – and you can have one with each account.
And don’t forget the biggest earners – bank switching. You might want to wait for Halifax to offer a cash bonus for opening an account. In the past Natwest and Lloyds have let existing customers switch in for a bonus, so you might not have to wait to open those (though I can’t guarante it).
What you need to know about the Government’s spending and taxation plans.
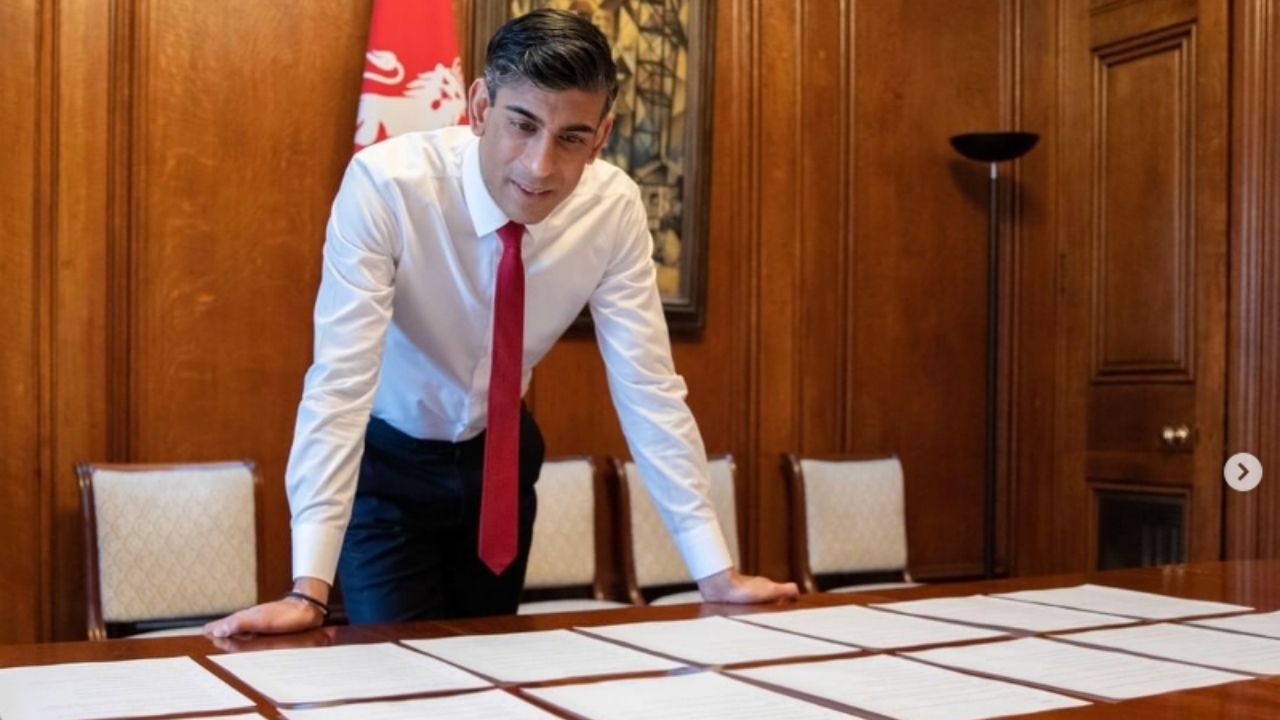
The Spring Statement, delivered in Parliament by Chancellor Rishi Sunak on 23 March 2022, isn’t meant to have any policy announcements. But the cost of living crisis is getting worse, with the energy hikes coming next month the largest cause for concern.
So as a result, we were given a handful of measures to relieve some of the pressure. Here’s what was announced and what difference this could make to your finances.
More detail may come in the next few days, and I’ll add information below as it’s revealed.
I’ll also be talking to the financial journalist Faith Archer on Thursday evening’s bonus episode of my Cash Chats podcast to analyse everything. You can subscribe now on your favourite podcast app so you don’t miss it.
Photo from HM Treasury Instagram account
Watch my video on YouTube talking about the Spring Statement or keep reading.
Fuel and energy
Fuel duty
There’s a 5p per litre cut to tax on petrol, which actually works out as 6p as there’s VAT on top. Depending on the size of your car, this will reduce the cost to fill a tank cost by around £2.50 or £3.50. So not much.
It comes into action from 6pm on 23 March 2022 and will last for a year. It will be worth a total of £2.4billion.
Of course, prices are still increasing all the time, so you’ll still be paying much more than you were a few months back.
Energy bills
Nadda. Zilch. Nothing. There’s no additional support to add to the £150 rebate due in April via Council Tax and £200 “loan” in October. A windfall tax on energy firms, as wanted by Labour, did not appear.
Green energy
There will also be a cut in VAT from 5% to zero for “energy saving materials”, things like solar panels and heating pumps. It’s a welcome move, but only the well off will be able to afford these changes.
Benefits and support
Household Support Fund
Those who are most vulnerable can apply for help from their local council’s Household Support Fund for help with things like bills, and the size of this will double from £500 million to £1 billion.
This sounds like a lot of money, but it’s a fraction of what would be needed to make up for the additional costs, so it really will only help those facing some kind of crisis with their finances.
Universal Credit
No change. This will only increase by 3.1%, as dictated by last September’s inflation figure, well below the average 7% predicted for the next year.
State Pension
It’s the same here, with the annual increase remaining 3.1%. There was also no talk of bringing back the “triple lock”.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Bonus requirementsTo get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
Regular saver8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
Existing customers?You can't have held a Santander account on 1 January 2026.
The increase to National Insurance Contributions (NIC), announced last September, is still going ahead in April. But from July the threshold where you start paying this is jumping up by a huge £3,000 to match the wages where you start paying Income Tax (£12,570 a year).
This means for the next financial year, those earning £35,000 or less will either pay the same or less National Insurance, with the most made here will be around £330 for those earning £12,570. The Treasury says this amounts to 70% of those paying NIC.
If you earn more than £35,000 in the next year then the increased NIC paid on those additional earnings will be more than the money saved, and you’ll take home less pay each month. Those earning £60,000 a year will see a loss of £232 this year.
It’s worth coming back to the dates for those changes. The NIC increase starts 6 April, but the threshold change isn’t until July. So you will be taking home less in your pay packet in April, May and June. Then from July, depending on your salary, you might be paying less.
Technically, when you average out the different allowances at the start and then the rest of the year, the threshold will be £11,908 for 2022/23. Then from 2023/24, when the whole year is at £12,570 (unless it changes again), those earning between £35,000 and £40,000 will benefit from a slight cut in their NICs.
Income Tax cut in 2024
One that won’t happen for two years is a cut to Income Tax. The basic rate tax rate will be 19% rather than 20% from 2024. But this is a long way away so it won’t help anyone right now, and a lot can change in 24 months.
Our podcast
Listen to Cash Chats, our award-winning podcast, presented by Steve Alderton and Editor James Andrews.
How to avoid overpaying for Netflix, Disney and more.
One of the things I love about the likes of Netflix, Disney+ and NOW TV is they are each far cheaper than getting premium channels from Sky or Virgin.
The problem is it’s so easy to sign up for these monthly streaming services. And with yet more new streaming sites launched (hello Paramount+), the more you have, the less of a bargain they actually are.
And with inflation hitting all our other costs too, it makes sense to find as many ways as possible to reduce what you pay.
So if you want to take advantage of these sites but also make a saving, here are the rules I follow to make sure I get the best value from the money I spend on streaming film and TV.
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
Binge, cancel and swap
There’s no way you can get the most of every service at the same time. At a push you might be able to justify two, but I think you’ll get the best value from one at a time.
Fortunately, all these services have 30-day or month-long contracts, meaning you can dip in and out whenever you want and only pay for the months you are signed up for.
Focus on the shows you want to watch on that platform, and when you’ve had enough you cancel your monthly payment and move to the next one. And so on.
This obviously requires you to cancel one when you’re done with it, and restart another. But this is very simple with each service, and can be done with a few clicks. You’ll probably want to put a note in your diary to remind yourself to do it.
Streaming Service prices compared
There are so many options, I’ve focussed this table on the main services, then some of the next tier options.
Monthly Cost
Annual Pass
Amazon Prime Video
£5.99 (£7.99 if full Prime)
£79
Apple TV+
£4.99
£49.99
BT Sport
£25
N/A
Discovery+ (Entertainment/Entertainment + Sport)
£3.99 / £6.99
£39.99 / £59.99
Disney+
£7.99
£79.90
Netflix (Basic/Standard/Premium)
£6.99/£10.99/£15.99
N/A
NOW Cinema
£9.99
N/A
NOW Entertainment
£9.99
N/A
NOW Sky Sports
£33.99
N/A
Paramount +
£6.99
£69.90
Arrow
£4.99
£49.99
BFI Player
£4.99
£49.99
Britbox (merging with ITVX in late 2022)
£5.99
£59.99
Mubi
£9.99
£71.88
Shudder
£4.99
£47.88
Starzplay
£5.99
N/A
So how much could you save having just one at a time? Let’s assume you can watch everything you need to in two months a year per main service. So that would be:
two months of Netflix Standard @ £10.99 a month
two months of NOW TV Entertainment @ £9.99 a month
two months of Amazon Prime Video @ £5.99 a month
two months of Disney+ @ £7.99 a month
two months of Apple TV+ @ £4.99 a month
two months of Paramount+ @ £6.99 a month
Paying full price each month would mean you pay £93.88 a year. That’s less than a year of Netflix on its own and you’ve got so much more choice. And if you nab deals, you’ll pay even less.
Avoid annual passes
This is an obvious extension of my first rule, but unless you know 100% that you are going to be watching one service at least 10 months of the year (most annual passes are 12 months for the price of 10), there’s no real saving in buying a discounted annual pass.
Of course, you might feel differently (especially if you’ve kids who are always on Disney+). So if you will watch it consistently then go for it, buy bear mind the cost when adding on extra ad-hoc subscriptions.
Watch out for extras
It’s tempting to upgrade Netflix to 4K quality, but I’d caution against it. Though it can make a difference, I’d argue it’s not worth an extra £5 a month over the HD Standard Netflix.
Likewise, the extra £2 a month to move from Prime Video to full Amazon Prime seems to make sense, but if you do this you will spend more money at Amazon – something I and many others are trying to avoid.
However, when it comes to NOW TV, the £5 Boost option is essential for basic HD and to avoid adverts (though I’ll always use the cancellation trick to hopefully bring this down to £1 or £2 a month).
Look for deals and freebies
Ok, an obvious one, but if you can pay less for a pass, then it’s a great way to save. Special offers are rare (though not impossible) to find on Netflix, but the other services all have promos and discounts, even freebies.
At the time of writing I’m on three months free Disney+, six months free NOW Entertainment, £2 NOW Boost for six months, one year free Prime Video, £1 NOW cinema for a month and I’ve got eight months of free Apple TV+ to activate before late August. That’s too much to watch, but it’s not costing me anything at all really.
These offers come and go, so check out my deal pages for the latest offers when I spot them.
Though not all services offer free trials, a handful do, so make sure you use these. Plus, though you’re only allowed one free trial per person, that doesn’t mean your partner, housemates or (older) kids can’t sign up.
You might even be able to repeat a trial. Amazon let you take a free trial every 12 months, sometimes sooner. If there are two of you in the house, that’s two months free a year – which should be enough to binge most of the content you want to watch.
These are the standard offers. For the links and details, check my deals pages. I’ll also share short-term extended free trials (eg with Apple and Mubi).
You probably do this already! But it’s possible to share your account details with all the main services.
It’s likely we’ll see Netflix clamp down on this (they’ve trialled a few different methods), and once they do, others will follow. So make the most of it while you can!
Be careful not to become the one who pays for all the services. Either get those using your service to contribute their fair share, or get them to pay for a different service and share that with you.
There can be limits on how many times you can do this and how many people can watch at once. And of course, just because you can do it, doesn’t mean you should. I’ve got more details in my article should you share streaming passwords and accounts.
Plan what to watch (and be picky)
With so much available, it’s easy to watch something just because it’s there. Yet so much of what’s available is trash. Really. Take a look behind the main titles and there are movies you won’t even believe were made. So I’m selective(ish). If there’s nothing I NEED to see, I’ll cancel.
And if there’s good word of mouth on programmes while I’m not subscribed, I’ll just add them to my list ready to binge when I next sign up. I’ll also time signing up for when all the episodes are available.
The only flaw in this plan is for shows on NOW as they come and go frequently, so if you miss it the first time around you might have to wait a long time for it to return.
Bonus requirementsTo get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
Regular saver8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
Existing customers?You can't have held a Santander account on 1 January 2026.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Check where you can watch it
There are some shows and movies that are exclusive to one platform or another, but many others will move about, or even be found on more than one service.
For example at the time of writing, Icon Films is pushing cult Ryan Gosling movie Drive on it’s front page, but that’s also on Prime Video. Or the US remake of comedy series The Office is on NOW, Netflix and Prime Video!
So before you sign up to watch that specific thing, check if you can watch it for less on another service. I use JustWatch for this.
Watch free catch up
And don’t forget, as long as you pay the licence fee, you’ll still have access to iPlayer along with All 4, ITV Hub and other free streaming services if you are stuck for things to watch.
There’s always a new drama or comedy to watch on the BBC (homemade and imported) along with some decent boxsets. There are new and recent programmes on Channel 4’s All4 along with a great back catalogue (The IT Crowd, Father Ted, Shameless). It’s well worth taking a break from the paid services every now and then to catch up on this classic TV.
If you hate adverts (I really do) you can pay extra to watch C4 and ITV catch up ad-free.


















 Featured deal

 Customer rating
3.9/5