Fix your finances in 2019 part 3: Sort out your savings

How to get in the savings habit, get the best interest rate and make sure you stick to it.

If you’ve been following these fix your finances posts over the last few weeks you’ll have a good sense of where your money is going and hopefully have also started reducing the cost of any debts. The next part is to focus on savings.

Savings might seem out of reach – various reports state most people don’t have much put aside, but there are some simple things you can do to help you get in the savings habit. Even managing to put aside £30 a month thanks to these tricks can make a big difference in 12 months time.

Work your way through each of these steps and you should be able to improve not just how often you save, but also how much money you make as a result.

1. Work out how much you can save and why

This is the first thing you need to do. Check what’s left each month after you’ve paid for the essentials, and work out how much of this amount you want to have for other spending and how much for savings.

It’s worth thinking at the same time why you are saving, perhaps even having a savings goal. This can really help motivate you.

2. Keep your savings separate to other money

If all your money is in one account it can be difficult to keep track of how much you’re saving up, and its easier for that money to be spent on everyday purchases. So set up a completely different account to store your savings.

3. Prioritise your savings

If you only save at the end of the month, you’re more likely to spend the cash elsewhere. Instead move the money immediately after payday into your separate account.

4. Pick the best account for you

This can be a simple savings account – but you won’t get much in interest like this. Likewise ISAs aren’t much use to most of us now because we can all earn a decent amount of tax-free interest in other accounts. Others can pay much more though. Here are a few options:

You want the highest interest

The best rates right now are with current accounts. You can have as many of these as you want with different banks, though individual banks might limit how many you can open with them. Right now the highest paying ones are:

  • Nationwide FlexDirect – 5% on savings up to £2,500 for one year
  • TSB Classic – 5% on savings up to £1,500
  • Tesco Bank – 3% on £3,000 (you can open two accounts)

You don’t have a lump sum but want to save every month

I love a Regular Savings account. You can get as much as 5% interest on monthly deposits for 12 months, with the interest paid and account closed when it reaches the end of the first year. You can then set up a new account and start again.

You are limited as to how much you can save each month, usually around £250 or £300, but that’s great if you are gradually building up savings and you don’t need to access the money for a year. The highest paying Regular Savers at the moment, which also require you to have a current account with the bank are:

  • First Direct – 5%
  • Marks and Spencers Bank – 5%
  • HSBC – 5%

If you’re not with any of the banks listed here or above it’s worth looking to see if there are other incentives, such as a £100 cash bonus, to get you to switch.

If you’re saving for your first home

Open up either a Help to Buy ISA or a Lifetime ISA. You’ll get a 25% bonus on savings, as well as the set interest rate, when you buy your first home – though do read up about the restrictions.

If you’ve got a lot of money

The options above don’t work for anyone with hefty sums put aside. If you don’t need to access the money then you should probably consider investing some of the money. It’s a risk, investments can fall as well as rise, and I’m no expert, so you should do plenty of research to decide if it’s for you.

Alternatively, you could look at an easy access account such as the one from Marcus, currently offering 1.5%. This is below inflation but better than you’ll get elsewhere.

5. Automate your savings

There are ways to make saving a lot easier too.

Set up a standing order to move your wedge of cash and you won’t forget to do it. This is really useful for regular savers.

You can also link your bank account to a smart app such as Chip or a Facebook Messenger bot such as Plum. They use algorithms to analyse your spending habits and decides how much you can afford to save. That amount is automatically moved into a savings account. Chip, in particular, is good as you can start off with 3% interest for the first year and earn as much as 5%.

Or you can see if your bank has a “top-up” feature. Banks including Lloyds and Monzo do this. When you spend money on your debit card, your account will round-up transactions to the nearest pound. So spend £1.30 and 70p will be moved to a separate pot.

Chip app review – Can it help you put money into savings?

The best bank switching, cashback, interest & overdraft offers (May 2021)
#FoodBankAdvent: How it works, and why you should take part

Join me and hundreds more in donating food and raising awareness of food poverty with a reverse advent calendar.

Many of you know I also run the UK Money Bloggers community. It’s a group of people like me. We’re all a bit geeky when it comes to money, and we enjoy sharing our passion with the readers of all our blogs. It’s a lovely network and a great source of support for everyone involved. But that’s not all it does.

Collectively we’ve got hundreds of thousands of readers, Insta-groupies, Facebook fans and Twitter followers. We’re what the industry calls “Digital Influencers”. And this means we can make a difference en mass. Or at least make a decent bit of noise.

So each year we run a Christmas campaign. A couple of years ago we had the idea of #FoodBankAdvent  and this’ll be the fifth year we’re doing it. Tens of thousands of people have taken part, and we want even more of you to join in this year.

What is the #FoodBankAdvent challenge?

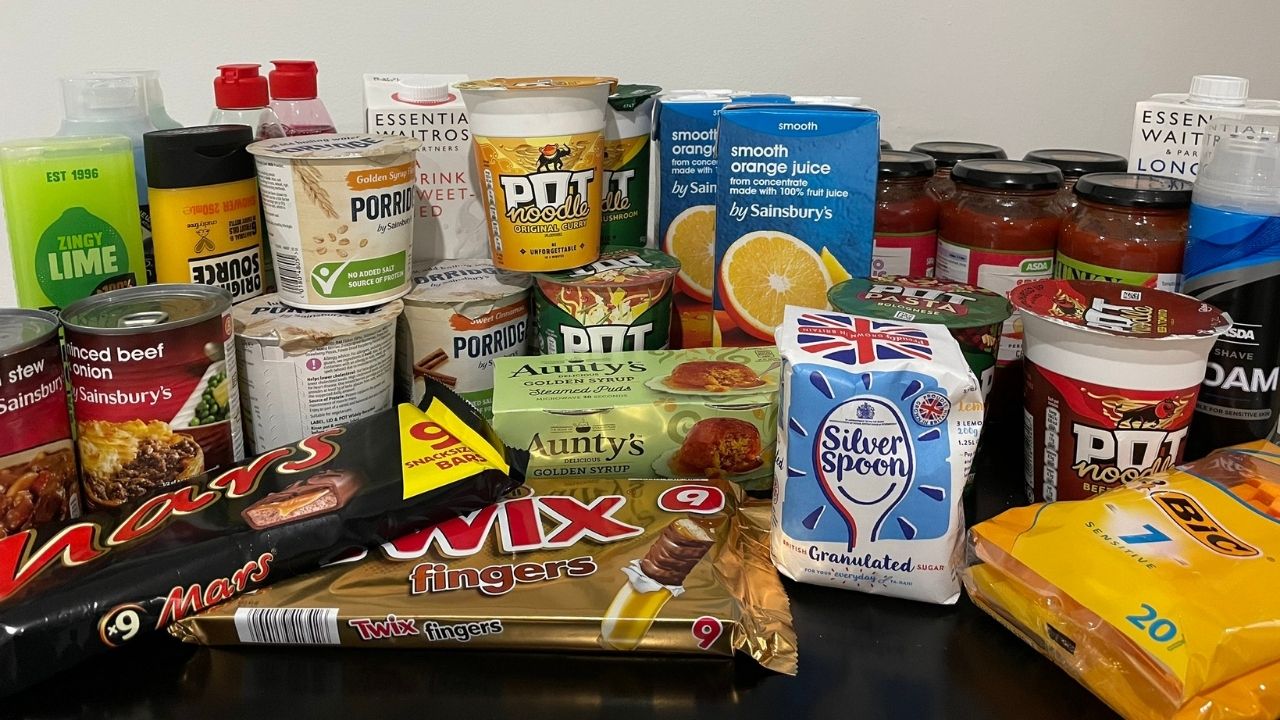
You all know how advent calendars work. Well this is a reverse advent calendar. Rather than take something away, you give instead.

The challenge is to do this for 24 days. On each day you put an item into a box. And then once the box is full, you donate it to a food bank.

It’s very simple. Yes, you could just donate a box of food in one go (please do!), but doing it this way not only makes it a bit of a project, but it also helps raise awareness of the need for donations.

Each year many of the people taking part, both bloggers and readers, shared their pictures on social media with the hashtag #FoodBankAdvent and it makes a huge difference getting more people to join in.

Why food banks?

Millions of people in the UK are going hungry every year. Some of this is down to debts and low pay, but delays to Universal Credit payments are often making the matter worse.

Those struggling don’t have enough money to cover their essentials, and that often means there’s not enough money to eat.

Recent figures from the Trussell Trust, which runs the largest network of food banks in the UK, show they distributed three-day emergency food supplies to 1.9 million over the 12 month period BEFORE the pandemic. And demand has soared since. It’s shocking that this happens.

If you aren’t convinced, then watch Ken Loach’s film I, Daniel Blake. It’s an amazing film, even if I was in tears for most of it. Please do watch the whole movie, but if you can’t, then watch this clip. It really brought home to me the needs to do something to stop food poverty.

Now is the time to start your reverse advent calendar

You can do this at any time, but it helps to do it in November. The main reason is you are then ready to donate it in early December rather than just before Christmas.

Food banks are usually staffed by volunteers and rarely open every day. That means the earlier you get your donations to them, the easier it is for them to sort the items and get them to people. A donation on Christmas Eve might seem the most festive, but it’s also the least practical.

You can of course donate in the New Year instead if you want, just make sure the dates on the food you are collecting are long enough. And if you can, please do continue to donate throughout 2022.

How you can take part

It’s really easy. Start collecting extra bits when you go to the supermarket. And not just food. Toiletries, including sanitary towels, are expensive too and are very welcome donations.

Here’s my collection from 2020:

It’s well worth checking out what your local food bank needs, as often there’s a surplus of some items (pasta and beans for example) and a lack of others.

You can search for Trussell Trust food banks by postcode, but there might be others in your area run by local community or church groups. It might be you need to take your donation to one of the foodbanks, but you might also have a drop off point at your local supermarket (there’s one in my Waitrose for example).

Please, please, please do share your progress on social media, and use #FoodBankAdvent. Combined we can use this to make some noise and get even more people taking part.

You can also read more about the campaign and get regular updates over at www.ukmoneybloggers.com.

Fashion sales and deals

Here is the pick of the current fashion offers, discount codes, flash sales and deals

Whether you’re looking for a great deal on the high street for your summer or winter wardrobe or searching for something a little more specific, it’s always nice to grab a bargain. Here are some of the best ways to save on clothes.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

Sales and offers

Discounts for joining mailing lists

Uniqlo: £5 off in-store

Download the Uniqlo app and you’ll get a £5 voucher to use in shops (not online). There’s a minimum spend of £40.

Cashback sites

It’s always worth checking what rate you’ll get from the likes of TopCashback or Quidco. If you’ve not used them before then you can also get a welcome bonus worth up to £20 by joining our newsletter.

Fix your finances in 2019 pt 2: Better manage your borrowing

From credit cards to mortgages, it pays to get on the best deal possible on any debts or money you borrow.

Last week I shared the basics of fixing your finances, from working out what you really have through to identifying the easy places to trim your spending. This week I’m showing you how to better manage and reduce the cost of any money you borrow.

This can make a decent difference every month. Reducing the interest you’re paying will not just mean you’re shelling out less, but it gives you extra cash to clear any debts faster. And once that debt is completely gone, there’s even more money every month to save or spend as you want.

So here are a few steps to take:

1. Identify the state of your debts

In last week’s article I suggested you analyse all your statements and bills, and look for things like interest charges or fees on debts, from credit cards to overdrafts. It’s also worth totalling up all the different debts. How do they look?

It’s all a bit scary

If you are worried about the size and monthly cost of all your borrowing and think they are out of control, then the tips below might not be enough. It’s worth reading this guest post from the top debt blogger Debt Camel explaining a few methods to try and where to get help. Don’t, whatever you do, ignore the situation.

You can afford the repayments

Hopefully you think what you owe is manageable and not pushing you further into debt. Great. There’s no need to panic, though you should take it seriously.

Work out which debts are the most expensive. That’s generally the ones with the highest interest rate. These should be your focus, though don’t ignore any which could mean you end up in the courts or without power.

There are no debts… at the moment

Or you might not have any debts at all. Even better! But there’s a chance you might need to borrow money in the near future. And that’s not necessarily a bad thing.

Borrowing can be good too. It can be used to spread out the cost of expensive items we don’t have the cash for now. That’s not just things like student loans or mortgages, but even buying a car so you can get to work can be a “good debt”. The key is to make sure it’s as cheap as possible, more on this in a bit.

2. Are any of the costs avoidable?

Next up, a very simple exercise.

Have you got savings as well as debts? In most cases, it makes little sense to have lots of savings if you also have lots of debts. The interest you’re paying on your credit card bill or loan is likely to be a lot higher. So if you’ve got savings, use them to clear your debts. In the event of an emergency then you can still use your credit cards.

Have a think about why the debts are being built up. Some might just be down to bad management. You might only be going overdrawn because you’re not checking your bank balance regularly enough. Or your bills might be going out the day before payday rather than a few days after. These are easy to fix.

And, unless something is urgent, it’s better to save up and buy something later with no interest charges than to whack it on a credit card now. Basically don’t spend money you don’t have or can’t afford!

3. Find more money to pay the debts off faster

You’ll hopefully already be finding ways you can cut back on spending from last week’s article, and I’ll be sharing more ways to spend less on bills and shopping over the next few weeks. It really is worth using any extra cash you find or make to pay off debts.

4. Cut the cost of borrowing

If you can’t clear existing debts immediately or are likely to borrow money in the future the trick is to make it as cheap as possible.

Here are a few basic things you can do to reduce how much you pay on credit cards, overdrafts and mortgages, but similar principles apply for other money you owe.

Credit cards

I’ve already written about clearing credit card debts fast, so do read that article for more details. But basically, it’s best to clear the cards as fast as possible, potentially with any savings. If not you can look to transfer your balance to a 0% card or a lower rate, long-term card. This will reduce the interest you are charged.

With new or existing credit card debt it’s good to pay off as much as you can each month, ideally the full balance. Avoid just making the minimum. it’s also worth, automating your repayments. The easy way to do this is via a direct debit. Just make sure you’ve enough in your account to you don’t hit your overdraft.

Zero per cent credit cards can also be useful to spread out the cost of big purchases – and can even save you money in some instances. The key here is only to use them for things you know you can afford but don’t have enough cash for now. For example, buying a new iPhone outright is usually cheaper than getting one via a contract. However, at a cost of around £1,000 it’d be tough for many to afford it in one go. So say it’s spread out over 20 months at 0%, then it’s a more manageable £50 a month. Just don’t overextend yourself.

With any type of 0% card make sure you have a plan to clear the full balance before the initial interest-free period ends. You’ll also need to make at least the minimum repayments every month.

Overdrafts

If when you went through your accounts you found you’ve gone into your overdraft, even once, then you’ll also probably have been charged. Yep, overdrafts are a debt. You’re borrowing from the bank, and charges can be very expensive. As with credit cards, it’s worth clearing this as soon as you can, and savings held elsewhere can do the job.

Another option is to switch banks to one which offers a 0% buffer. First Direct will give customers a £250 interest-free overdraft which is good if you occasionally dip into the red. If the amount is more substantial, and happening regularly, then look at Nationwide’s Flex Direct account. A larger fee-free overdraft (subject to approval) is available to new customers for the first year, which should hopefully be enough time to clear it without getting pesky additional charges.

If neither of these work for you, it’s worth comparing the fees at other banks for going overdrawn. Some charge a monthly fee, others charge each time you go overdrawn so the best option depends on the amount and how often you use the overdraft. You can also talk to your current bank to see if they’ll help with your existing overdraft.

Mortgages

Your mortgage is probably your biggest debt, meaning even at a low rate it’ll likely be your most expensive. And this means finding a cheaper deal can make a big difference to your monthly costs.

The lowest rates could well be with a different lender, though when I reduced mine a few years ago the cheapest was with my existing provider. Make sure you’re not just comparing the interest rate. Look for additional charges and restrictions on things such as the ability to overpay.

You also need to watch out for early repayment charges, which could make it more expensive to move your mortgage.

5. Build up your credit score

Credit scores are really important for borrowing money as they’re a key indicator of what rate you’ll get. So start doing what you can to improve it and in time you’ll be able to get even cheaper borrowing.

Next week, the third part in this series will help you get the best return from your savings.

Credit scores explained

How to quickly clear your credit card debt

How to convert your Tesco Clubcard points into vouchers, including the new ‘Faster Vouchers’

You can now convert Clubcard points into vouchers within 24 hours.

If you collect Tesco Clubcard points, you’ll be familiar with the frustrating wait to use those points. Historically you’d get a statement in the post every quarter, converting all your newly earned points into vouchers to spend. Then if you only part used a voucher you had to wait for the next statement for the leftover points to be converted to a new voucher.

But that’s all changed with the addition of Faster Vouchers. Here’s how they will work.

How to covert your Tesco Clubcard points into vouchers

You can still wait for the paper vouchers to come in the post every three months, but if you do want them faster you need to go into your online Clubcard account or the app. Here go to “Points” and select to transfer the points. You’ll then get the vouchers in your account ready to spend in 24 hours.

When you do this, all your points will be converted into vouchers as long as the total value is divisible by 50p. So if you had 444 points, you’d get £4 in vouchers, and be left with 44 points to convert later.

However there are a few tiny complications whether you opt for the digital or paper vouchers. For example, you’ll need at least 150 points in your account in order to convert them to vouchers. This is worth £1.50. My balance is 107 points, and I’m not sure how quickly that’ll grow as since I moved out of London we don’t really have a Tesco near us.

You also can’t convert with faster vouchers for two weeks before the quarterly statement date. These are in February, May, August and November each year, though the exact dates are listed anywhere.

Faster Vouchers also won’t work if you have opted into another scheme such as Christmas Savers or British Airways Executive Club. You’ll need to leave those if you do want Faster Vouchers.

Despite these three points, I think this is a good move from the supermarket.

How to spend Clubcard vouchers

You can spend the Faster Vouchers in exactly the same way as you did the standard paper ones. That means in Tesco stores or online with partners.

If you want to use them in a physical shop then you can either print out the voucher or show it in the Tesco app on your phone.

However, I think the best way is to boost your points online. Do this and you can triple the value. I’ve written before about my top ways to spend the points, but my faves are the ones which are harder to discount elsewhere. So that includes Red Spotted Hanky for train tickets or Uber for taxi rides.

You’ll see your converted points as vouchers in the checkout when you select your boosted reward so there’s no need to print them out or cut and paste the codes.

Once you covert your Clubcard points to vouchers, you’ve got 21 months to spend them. The date will be printed on the vouchers, and you can check them in your account too.

What if you want to get your vouchers in the post?

If you do nothing then you’ll continue to get the quarterly statement and vouchers in the post. However if you did opt for the Faster Vouchers the statement will be sent via email instead. You can revert back to paper ones in your Clubcard account.

The best ways to use and earn Tesco Clubcard points

What are loyalty card points worth?

The real value of your Tesco Clubcard, Nectar, Morrisons More, Boots Advantage and Superdrug Beautycard points

If you’re like me, you’ll have a few loyalty cards on your phone and swipe away when you get to the till. But do you have any idea what the points you earn are worth?

I’m a big fan of Clubcard points as you can boost their value. I know what my Tesco points are worth as I use them frequently, but what are 2,000 Nectar points worth? Or 800 Boots? Plus there are schemes at Morrisons and Superdrug too – and they’re all different.

To help me – and you – I’ve taken a look at the biggest schemes to see what you get for your points, and how much you need to spend in order to actually use them.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

How much are Tesco Clubcard points worth?

Value of Tesco Clubcard points

  • 1,000 Clubcard points = £10
  • 500 Clubcard points = £5
  • 100 Clubcard points = £1
  • 1 Clubcard point = 1p

Real value of Clubcard points

  • Usually 1 point earned per £1
  • So 1 point = 1% of your shop
  • Minimum payout is 150 points = £1.50 in vouchers
  • So you need to spend £150 before you can start using points

You can earn these at Tesco shops, petrol stations, website and also via Tesco Mobile and Tesco Bank.

Though the value is equivalent to 1%, you can boost them, usually double the value. Read the Best Uses Of Clubcard Points article for more on how to make the most of these points.

There are often extra discounts in store for Clubcard holders.

How much are Nectar points worth?

Value of Nectar points

  • 1,000 Nectar points = £5
  • 500 Nectar points = £2.50
  • 100 Nectar points = 50p
  • 1 Nectar point = 0.5p

Real value of Nectar points

  • Usually 1 point earned per £1
  • So 1 point works out as 0.5% of your original Sainsbury’s shop
  • Minimum payout = 500 points will give you £2.50 credit
  • So you need to spend £500 before you can start using points

You can get bonus points on specific items each week, but you need to activate these in the app. You can also earn Nectar points at Argos.

There aren’t really any ways to boost the value of your points, but here are the best ways to earn and spend your Nectar points.

How much are Morrisons More points worth?

Value of Morrisons More points

  • 1,000 Morrisons More points = £1
  • 500 Morrisons More points = 50p
  • 100 Morrisons More points = 10p
  • 10 Morrisons More points = 1p
  • 1 Morrisons More points = 0.1p

Real value of Morrisons points

  • Points are earned on specific products rather than your whole shop
  • The amount you earn will vary, so you can’t assign a percentage value for 1 point
  • Minimum payout = 5,000 points will give you a £5 voucher

Morrisons brought back points in the summer of 2023 (having axed them two years earlier). It’s different from the likes of Clubcard and Nectar but you can find out how Morrisons More works here.

You’ll need 5,000 points to cash them out as a £5 voucher and there aren’t any ways to boost the value of the voucher.

How much are Boots Advantage points worth?

Value of Boots Advantage points

  • 1,000 Advantage points = £10
  • 500 Advantage points = £5
  • 100 Advantage points = £1
  • 1 Advantage point = 1p

Real value of Boots Advantage points

  • Usually 3 points earned per £1
  • So 1 point works out as 3% of your original shop
  • Minimum payout = 1 point / £0.01
  • But you can’t part pay with points (you need enough points to cover the total of the transaction for which you are using them)

You can only spend them in Boots shops or online at Boots.com. Of course, if you can get your shampoo cheaper elsewhere, the points probably won’t make any difference.

Keep an eye out for frequent bonus deals and vouchers where you can earn double value or even more for your shop. There are often extra codes in your online account.

How much are Superdrug Beautycard points worth?

Value of Superdrug points

  • 1,000 Superdrug Beautycard points = £10
  • 500 Superdrug Beautycard points = £5
  • 100 Superdrug Beautycard points = £1
  • 1 Superdrug Beautycard points = 1p

Real value of Superdrug points

  • Usually 1 point earned per £1
  • So 1 point works out as 1% of your original shop
  • Minimum payout = 100 points / £1
  • So you need to spend £100 to use any points

It’s similar to Boot’s in that there are often bonus points offers. You can only use your points in multiples of 100.

How to find bargain second-hand clothes

This September Oxfam is urging us to shop second-hand in a bid to reduce the environmental impact of making new clothes.

Thirteen million items of clothing are added to landfill every week in the UK! That’s a huge amount of material that could be recycled or repurposed.

In fact much of it is probably still ok to wear. But with clothing so cheap, and new styles available every week (both the consequences and cause of ‘fast fashion’), items can be worn just a few times before they’re consigned to the scrapheap.

The problem is every time a new garment is manufactured, it takes its toll on the planet. Oxfam say 20,000 litres of water are required to make one pair of jeans and one t-shirt. For a person to drink that much would take 13 years.

And that’s not the only problem. There’s also an issue with pollution (particularly from dyes) and how often do we hear about labour issues, whether child labour or incredibly low wages. We really need to consider more sustainable alternatives. 

Listen to Andy chat with fellow money bloggers Hollie and Faith about the Second-hand September campaign in this episode of the Cash Chats podcast.

And if the environmental argument to buy less new clothing is quite enough to get you away from Primark, there’s also a financial one. 

If you’re guilty of buying items you hardly wear, so are other people. If they donate it after a couple of wears, then you’ll be able to buy something practically brand new for a fraction of the price. And there are other ways to get second-hand clothes without spending anything at all.

So whether you’re looking to take part in #SecondHandSepember or just want to reduce how much you spend on clothes, I’ve a few tricks to help you get involved.

Where to buy second-hand clothes

Find local charity shops

The obvious places are charity shops. It probably makes sense to hit a few in one shopping session to help uncover that gem that’s just right for you.

Some shops will be a jack-of-all-trades and sell everything from cutlery to board games, but take a look to see if there are specialist fashion stores which will have a wider range. There are also some geared explicitly at younger people.

You can use this Charity Retail Association tool to see which shops are near you and get an idea of what things are sold there.

Remember too that there are lots of charities which need your money, so you might want to choose local or smaller ones in the first instance, or ones which support causes close to your heart.

Hunt for high end and designer second-hand

If you can go to posher areas you might find that the items that have been donated are not just M&S or Top Shop. They could be high-end high street, or even proper designer. Last year a Mind shop in Kent had £50,000 worth of gear dropped off anonymously. Of course, if the staff are on to this, they’ll price the items accordingly.

Big brands sometimes even donate old or second stock to charity shops, though they might be detagged so you need to have a keen eye to spot the Miu Miu from the M&S.

Some of the bigger charity shop networks will get individual stores to send through anything obviously designer. Oxfam, for example, has a designer outlet store, while the Red Cross has specialist shops around the country.

> Oxfam’s designer boutique

> Red Cross vintage and designer shops

Even so, you could still pick up something that you’d never normally afford for a fraction of the original price. And you might find a better range of donations at smaller, independent charity shops where they sell what they are given.

This article from Stylist magazine has some great tips for how to work out if what your looking at is a retro classic or cheap knock off.

Check out vintage shops

Though run for profit rather than charity, and usually at the pricier end of the second-hand market, vintage shops still fit with the sustainable and ethical approach to buying second hand. This Harpers Bazaar article shares ten top vintage retailers around the UK.

Search on resale sites

We all know about eBay, but I think you’re better off looking for bargains on Facebook Marketplace (it’s easy to find on the app), or websites llke Debop, Shpock and Preloved.

How to get free second-hand clothes

As much as I like the idea of buying second-hand (the money often goes to good causes), you can also refresh your wardrobe without spending a penny.

Stocktake

I’m confident that if you properly had a look at what’s in your wardrobe you’ll find items you’ve completely forgotten about. And if you start wearing them again (or even for the first time), you’ve updated your wardrobe without any new spending.

Shwop

If, during your Marie Kondo style clearout you find items that are still perfectly good but not right for you, then try shwopping. This weird word is an amalgam of swapping and shopping which should give you an idea of what you’ll do. 

You can go to organised events or just run one with your friends (or just informally do it with one or two mates). The idea is you bring along anything you no longer want, as long as it’s in good nick, and hang it up in a makeshift shop. Then you get the chance to take something new back home, and someone gets to give your old gear a new lease of life.

Becky, my good friend Silke and half a dozen others did this a few years ago and all of them went home with something new, as well as clearing out those items they didn’t want anymore.

Hand-me-downs

Parents do this all the time to their own kids, but there are Facebook groups set up to help parents who don’t have relatives or friends that can pass things on.

Donate

Of course, as well as not buying new clothes, it helps to not add your old ones to landfill. You’ve got a couple of options. One is to give wearable items to charities – whether shops to resell or places like refuges. Or if they’ve had better days look to donate the items for recycling. 

Get free M&S and H&M vouchers for donating and recycling

M&S, John Lewis, New Look and H&M all have schemes where you get vouchers to spend in-store for bringing in old clothes. I’ve written more about how they works here.

Buying less new clothes longer term

Buying second-hand is a great alternative to brand new, but there will be times where you need to get items that haven’t been worn before (do not buy second-hand pants!). So how do you do this in a way that’s sustainable?

Buy it good, buy it once

Cheap clothing just doesn’t last as long. Buy something that’s better made and it should last longer. This also means you should be looking at classic styles that you know you’ll be happy wearing next year and the year after. 

Make do and mend

The wartime necessity of fixing broken clothing was brought about through rationing, but there’s no reason why adopting those principles today can’t give your clothes an extra lease of life, Basic repairs such as sewing buttons back on should be within the grasp of most people (or your mum). If you have better skills then you could even look at turning old clothes into something new. 

Rent

You could also consider renting clothing. It’s not just formal wear like tuxedos and prom dresses that you can get. Online stores such as Girl Meets Dress let you hire designer gear for a few days at the fraction of the price of buying it.

Secondhand doesn’t just mean clothes

Think broader than clothes too when considering second-hand. You can buy cheap books, DVDs, CDs and games from the likes of CEX and MusicMagpie, while furniture is a big thing for charity shops. Facebook marketplace is once again a good place to look for things.

Comping: a beginner’s guide

Fancy winning prizes and cash? Here’s how to get started.

Once a month I ask one of my money blogging friends from my UK Money Bloggers community to share their savvy experiences on a topic I wouldn’t normally cover.

A few years ago I had a brief spell of entering competitions. I had a few nice wins, but I never got in the habit. So for March, I’m delighted that the queen of competitions Di Coke from Super Lucky Me has written a guide to get you winning.

How to be a winner

Comping is one of the cheapest and most rewarding hobbies there is – since I started entering competitions twenty years ago, I’ve won more than £300,000 of prizes, including a VW Beetle, over £20,000 cash and around 40 holidays abroad!

To a beginner, comping can be overwhelming – it’s easy to get sucked in by survey websites offering big cash prizes, and before you know it your details have been passed on to a hundred other companies! Stay safe by only entering competitions on the websites and social media pages of brands and blogs you know and trust.

Where to find competitions

There’s a huge range of prize promotions in the UK – the easiest way to find them is to check out the competition section of websites like MoneySavingExpert, Loquax or Latest Deals. But of course, thousands of other compers will be using those sites as their main source of comps – so you should also look out for brand new promotions advertised on products, in magazines, on Facebook, Instagram and Twitter, in shopping centres and on the radio!

Which competitions offer the best chance of a win?

The harder a competition is to enter, the easier it is to win. If you need to buy a product, download an app, or tweet a funny story – most people just won’t bother. Photo comps are popular on Twitter and Facebook, and the same themes crop up time and time again – smiley selfies, DIY disasters, summer fun…. set up an album on your phone to store ‘competition photos’ so you can find them quickly. And don’t worry if your photo isn’t great – quite often the winner will be chosen at random! An easy photo competition to enter is Ambrosia’s – upload a happy photo featuring an Ambrosia product, and every month until December 2017 a hundred random winners get a prize!

Enter competitions with lots of smaller prizes, or those with multiple daily or weekly draws. Look out for comps that offer 100+ prizes a day, or try the regular Quidco and Topcashback giveaways when you can win thousands of cashback prizes instantly. The prizes might be small, but a win will be almost guaranteed, and will keep you enthusiastic about the hobby!

I have a lot of success with on-pack promotions, yet most people ignore them. You usually need a receipt or a unique code from the packaging to enter – but only buy if it’s a product you will use. This year’s biggest on-pack promotions so far have been on Walkers Crisps, Plenty kitchen towel and Velvet toilet roll, and the products are usually heavily discounted at the start of a promotion, so it’s worth stocking up! Some instant win promotions give out prizes after a ‘winning moment’ – if you enter very early in the morning, you’ll have a better chance of winning a prize than entering at lunchtime. Watch out for the misleading promotions with huge prize numbers where prizes are ‘available’ to be won though (for example, Walkers Spell & Go) – only a small percentage will ever be given away!

Comping tips and tricks

  • Read the rules – check the closing date and that you’ve done everything required. If the prize is on a set date, make sure you can go.
  • Set up a new email account for comping and avoid signing up to mailing lists if you can (NEVER agree for your details to be passed to third parties).
  • Search your inbox and junk folders every couple of days for ‘congratulations’ or ‘winner’ in case you’ve missed a winning message.
  • Use Twitter or Google search to find local competitions and specific prizes.
  • Filling online entry forms can be time-consuming – use autofill in your browser and ‘text replacement’ on a phone to set shortcuts for your email address, postal address and Twitter handle.
  • Set notifications from your favourite brands and local businesses on Instagram, Twitter and Facebook to make sure you’re the first to know about their latest competition.
  • Take advantage of any spare time you have by entering a few quick comps on Twitter or Instagram.
  • Join Facebook groups for advice, to make friends and to share competition details (Lucky Learners is great for beginners).

Don’t give up!

Most people start comping and expect instant prizes – it doesn’t (usually!) work like that. You need patience and persistence to succeed. Put in the effort, and make sure you’re always looking out for the word ‘Win!’ – on your Twitter feed, in magazines, on the supermarket shelves… opportunities to win prizes are everywhere, you just need to be prepared to take them!

For competitions and advice, visit Di’s blog Super Lucky Me, plus her book of comping tips, ’SuperLucky Secrets’ is available on Amazon.

Budget 2015 basics – the six things you need to know

Will it make a difference to you?

Last Wednesday saw the chancellor reveal his fifth budget, and the last one before May’s General Election. It wasn’t the “giveaway” that many had predicted, and behind the gags aimed at Ed Milliband, most of the changes announced won’t be relevant to us normal folk, at least not on a day-to-day basis.

There were a few changes though that it’s worth knowing about – here are my top six.

1. Less tax for savers

At the moment you pay 20% tax on most of your savings (40% if you are a high earner). It gets automatically deducted by your bank and pretty much the only way to avoid this is with an ISA.

From April next year, everyone will be able to make £1,000 interest tax-free in normal accounts. I’m always going on about making sure you’re using the high interest bank accounts to get the most cash, and this means you’ll make even more.

The question is, will anyone need an ISA after this? £1,000 is a LOT of money to make on savings (eg you’d need £50,000 at 2%).

If you do have an ISA, another change this autumn will mean you’ll be able to withdraw money and then pay it back in without it affecting your £15,240 allowance. This is a good thing!

There’s also going to be a new Help-to-Buy ISA for any first-time home buyers. From the autumn, the government will top up savings in these accounts by 25%, up to a maximum of £3,000. You’ll only be able to save a maximum of £200 a month and it would take over four years to save the max possible. Still, it’s free money if you fit the criteria.

If you have money to save, you can read my thoughts about whether you should get an ISA or a high interest current account.

2. Less tax for workers

We already knew that the amount of money you earn before you pay Income Tax (called the Personal Allowance) will go up from £10,000 to £10,600 this April. In this Budget, the chancellor announced that it’ll go up by another £200 next April, and £200 again the year after. Each £100 it rises is worth £20, so by 2018, that’s an £200 we’ll all take home in our paypack.

The minimum wage will go up by 20p from October, good news for any low earners.

If you are a “Higher-earner” – basically anyone who currently earns more than £41,866 – you have to pay 40% tax on earnings over that amount. From April this won’t kick in until you earn above £42,385, which means you’ll pay £104 less in tax. It’ll go up again to £43,300 in April 2017.

If this all sounds confusing, I’ve written a guide to explain your payslip.

3. Less tax for drivers & drinks, more for smokers.

A planned petrol tax increase due in September has been cancelled. That’s meant to be worth around £10 a tank.

Beer will be 1p cheaper a pint, while the tax on cider and spirit will go down by 2%.

Just because both will be cheaper doesn’t mean you should be doing it at the same time!

Smokers though will still have to pay more as the already planned rise will go ahead.

4. There’s a new £1 coin

From 2017 we’ll all be using a 16 sided coin rather than the normal rounds ones. It’s to tackle forgeries. Though I’m pretty sure vending machine and supermarket trolley companies won’t be too happy!

5. More freedoms for people with a pension

From next year, anyone who has already cashing in their pension pot and bought an annuity will be able to sell it for a cash lump sum. Whether that’s a good idea or not is another matter!

6. Less hassle for anyone who fills in a Self-Assessment tax return

They’re going to gradually replace these with digital accounts, hopefully making it a lot easier for people to work out how much they owe. It’ll start in the new year but take five years to finish.