How do 0% purchase cards work?

We explain how to get the most out of them.

The right credit card can let you spread the cost of a big purchase, or a string of smaller ones, interest free over months or potentially even years. Just make sure you follow our three rules to make the most of them.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

What is a 0% purchase card?

A 0% purchase card lets you spend money on it for a set period before any interest is added to your balance.

The set period runs from a few months to potentially years – with the longest 0% purchase card on the market at the time of writing being 25 months.

That means if you need to buy something big, or have a string of expenses coming up, you can spread the cost over a long time without being charged interest.

I used one after moving into my current flat, as I knew I needed to buy a lot of furniture and other essentials in a short time and this let me spread that cost out.

Crucially, you will still need to make payments and will be sent a bill every month – it’s not free money after all – but there won’t be any interest added to your bill while you’re in the introductory period.

Paid advertisement

How 0% purchase cards work

You apply for an interest-free credit card the same way you do a standard credit card. That means you’ll need to be over the age of 18 and pass a credit check.

You won’t be told your credit limit until you’re accepted, with this often determined by a combination of your credit report and income, after that the card will be posted to you along with the PIN for it. Once you activate the card, you’re free to start spending on it.

After this, the cost of any purchases get added to your credit card balance. No interest is charged on this balance until after the end of the 0% period.

Once a month, you’ll receive a bill from your card provider, which you’ll need to pay to avoid penalties. However, everything you pay will go towards clearing that balance, rather than paying any interest.

You can choose how much the payment is as long as it’s more than the minimum amount – which is normally a small percentage of the overall amount.

Paid advertisement

What happens when the 0% purchase period expires

The month after your introductory period ends, interest is charged on whatever balance is left on the card.

This will be at the card provider’s standard rate – typically about 25% APR at the moment, but some cards can charge significantly more.

Any new purchases or payments made on the card also will have interest charged at them at the same interest rate.

What are the risks of 0% purchase cards?

The first thing to say is that any application for credit leaves a mark on your credit report

It’s not a huge factor, but it could affect your eligibility for other products, so it’s best not to apply for new cards ahead of taking out something like a mortgage.

Applying for several products in a short time, for example if you are rejected by one provider and re-apply to another or apply for several things at once, is also seen as a worrying sign by lenders. 

It can look like you’re desperate for money, and so put them off from wanting to deal with you.

Once you have the card, you need to make sure you aren’t late or miss any of the monthly payments. A missed payment not only risks you having your 0% period invalidated, it also leaves a mark on your credit report that lingers for years.

Not every purchase will be interest-free, either. Taking money out of the cash point, for example, will have interest charged on it immediately. Make sure you read the terms and conditions of the card to check what’s excluded.

Finally, you need to have a plan for when the 0% period expires. Ideally, you’d have cleared the balance by then, but if you haven’t, you’ll be left with an expensive debt.

If you don’t have the money on hand to clear the balance, you could try a transfer to another card – which could reset your 0% period – but be careful about fees associated with these.

Paid advertisement

What else should I consider instead of a 0% purchase card?

There are a fair few other options if you’re looking to spread the cost of payments without being charged interest.

The first is to save up for it first, instead of paying for it afterwards. Of course, you might not always have the time to do this.

The second option is a money transfer card. These send money directly to your bank account for you to use however you like. That money is added to the credit card’s balance, and frequently come with a 0% introductory period similar to purchase cards.

The big difference is that you’ll need to ask for the full amount at once, and you’ll be charged a fee of about 4% of the total amount when you make the transfer.

Finally, some banks still offer 0% overdrafts – although these are either limited in time to about 12 months, or for smaller amounts of £500 or less.

The three rules for using a 0% purchase card

Overall, 0% purchase cards can be a fantastic option to spread the cost of something expensive.

But to get the most out of them, you need to make sure you:

  1. Check your eligibility BEFORE applying 
  2. Set up an affordable standing order and stick to it
  3. Make a plan for when the 0% period expires

Our podcast

Listen to Cash Chats, our award-winning podcast, presented by Steve Alderton and Editor James Andrews.

Episodes every Monday.
Beauty & health deals

From freebies to money off, here are some great deals on health and beauty

From free trips to the gym to money off skincare and beauty products, here are some of the best health and beauty offers available at the moment.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

Nuffield: free 7 day pass

You can get a free seven-day pass at Nuffield gyms. It’s available at selected gyms only, and to get it, you need to sign up via the website and enter your postcode to choose a gym. You’ll be asked for some basic details and will be able to choose a date for the seven days to begin.

Everyone Active: free day pass

You can get a free day pass at Everyone Active gyms

This gets you free use of the gym, pool and fitness classes at your local Everyone Active leisure centre for one day. You can’t use it at Coral Reef Waterworld or Moorways Water Park.

To get it, you just need to sign up for it on the website, then download the app and show the pass when you visit.

The Gym Group: free day pass via Lidl Plus

Until the end of January, you can get a day pass at The Gym Group via the Lidl Plus app. You just need to go to your Lidl app and scroll down to ‘Partner offers’ on the home page.

Then you can select ‘redeem this offer’ and reveal a code. Go to The Gym Group website and find the day passes section to redeem your code.

Body Shop discounts

£5 Body Shop voucher on your birthday

Love My Body members get sent a £5 voucher on their birthday every year. You can sign up for the scheme (for free) here.

Paid advertisement

Grüum beauty deals

Grüum: skincare and/or haircare bundle for £4.95

You can get two or three full-sized products from Grüum (worth up to £36) for just the cost of delivery (£4.95).

There are several bundles to choose between. The options include skin cleansers, shampoo bars, body wash bars and fragrances, to name a few.

You have to pay £4.95 for delivery, but for a couple of products, that’s not bad.

Holland & Barrett offers

£3 free spend via Holland & Barrett loyalty scheme

Sign up to the H&B Rewards for Life scheme and you’ll get 300 bonus points straight away – worth £3.

You’ll then earn 4 points for every pound you spend, and vouchers are sent out four times a year (minimum 50 points needed).

Liberty beauty deals

Liberty: Subscription box offer

You can get an unusual beauty subscription box from Liberty. If you deposit £25 per month into your Liberty “beauty bank” (essentially buying store credit), then you get a “Discovery Box” four times a year for £5 per month, worth a total of £300 per year. 

You’ll still have the credit in your account that you deposited (except the £5 fee for each box), but it can’t be refunded or withdrawn.

What’s in the beauty box?

The box is called The Beauty Drop. You get four per year, full of trial-sized products. They’re sent in January, April, July and October and they’ll be worth up to £300 throughout the year. 

Remember that just because Liberty would sell the products for £300, it doesn’t mean they’re worth that for you.

The drawbacks

Your typical bank account has protection – you’re protected by up to £120,000 if your bank goes bust. However, your money in the “beauty bank” at Liberty isn’t protected. This means that if Liberty were to go bust, the money you have in the account likely won’t be refunded to you, much like a gift card.

You could mitigate this by spending the money you deposit as soon as you can and not letting a large balance rack up, but Liberty’s high prices might prevent this. 

Boots offers

There are often regular offers and savings at Boots so we’ve set up a page just for those deals.

Paid advertisement

Lush beauty deals

Lush: £3 Lush Club bonus (ended)

If you join Lush’s UK loyalty club then new or existing account holders can get a £3 welcome voucher if they sign into the latest version of the app before 8 October 2024.

You don’t need to do anything to trigger the coupon, though do check if it’s showing in the banner on the app or in the ‘Rewards’ section of the app.

You’ll be able to use the £3 in-store or on purchases via the app. It’ll last three months from activation.

Space NK offers

Space NK: up to 20% off with £5 charity donation (ended)

This is a decent opportunity to stock up on beauty essentials (and luxuries) as you can get up to 20% off at Space NK until 2 June 2025

You must donate £5 to the charity Switchboard LGBT+ via Space NK’s link, and then you’ll get a unique code to use.

This includes rarely discounted brands such as Diptyque – only a handful of items are excluded, which you can see here. You can’t use the deal on gift cards or sale items either.

It ends 11.45pm on 2 June 2025

Paid advertisement

Health deals

Vision Express: free eye test with £50 spend (expired)

Download the Lidl Plus app, and in the partner offers section you’ll find you can claim a free eye test (worth £30) and get 30% off frames, as long as you spend £50 on prescription glasses at Vision Express.

Ends 10 October 2025.

M&S deals

Beauty: £330 beauty advent calendar for £60 (ended)

You can get a £330 M&S beauty advent calendar for £60 when you spend £35 on full-price clothing, homeware or beauty.

The Beauty Advent Calendar 2025 includes a selection of 25 products, including some full-size products across bath and body, skincare, haircare and make-up.

Now, just because M&S say it’s worth £330 it doesn’t mean it actually is. You can see the entire contents here, so use that to work out whether it’s not just worth paying £60 for.

And of course, try to buy something you actually need to want for the initial £35 spend. Sale and clearance items are excluded from this qualifying spend.

Best Current Accounts 2026

These banks accounts are my top picks for the year

I’ve got 25 different personal current accounts right now. Yes, that’s far too many for most people, but trying them all out really helps me recommend to you the good from the bad.

You could just switch your existing account to get a better deal, or you could open a handful to take advantage of the different offers. Personally I’d look to have at least two accounts just in case of tech failures stopping you from getting access to your cash.

But there are other reasons to look around, from improved banking experiences to rewards to cashback to interest on savings.

To help you decide I’ve shared below my top picks of the best current accounts (you can also check out a full list of the latest offers).

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

Best dummy current account for switching

If you’re looking to take advantage of switching deals, it’s often worth setting up a dummy account you’ll use purely for this purpose.

Winner: Chase

A couple of reasons why Chase wins here. First, there’s no hard credit check when you first apply. Second, once you have one account, you can set up nine more in the app – and it’s these ones you’ll want to use to switch away.

Just be sure not to switch away your only Chase account as that’ll close your whole account down and you won’t be able to reopen it. Here’s more on how to use Chase for switching.

Best bank account app

Banking apps are improving all the time and the best have features such as freezing your card if it’s lost and features to help you save.

Winner: Starling

Recent improvements to the Monzo and Revolut apps made this a close call this year. Chase is decent too. But Starling still edges ahead. All of these digital only banks have features to help you track spending and manage your card, but I think not only does Starling do it best, it does a little more on top.

You can use it on both app and desktop, you can pay in cheques with your phone, you can deposit cash at Post Offices and more.

Runner up: Monzo and Chase

It’s worth taking a look at these other digital banks as often it’s personal preference which makes one stand out over the other. You might prefer them to Starling.

Runner up: Natwest

If you’re after a high street bank then the app I like the best is from Natwest (or RBS which is basically the same). You can do most things you need to do, and it’s clearly set out. A nice extra is you can use it to take cash out at Natwest or Tesco ATMs if you don’t have your card.

Featured deal
Customer rating 3.9/5
  • Switch bonus
    £240
  • Perks
    8% regular saver
  • Monthly fee
    0
  • Offer ends
    Unknown
  • FSCS Protected? Yes
  • Bonus requirements To get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
  • Regular saver 8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
  • Existing customers? You can't have held a Santander account on 1 January 2026.

Best bank account for spending

Thanks to changes to Chase’s cashback last year, there are no longer any accounts which I’d recommend to use for your spending. Instead you’re better off using a cashback credit card, or the debit card from PayPal.

However, there is a runner up.

Runner up: Monzo

Though many banks offer additional cashback offers linked to specific retailers, Monzo has the easiest one to view and manage. Here’s our review of the feature.

Our podcast

Listen to Cash Chats, our award-winning podcast, presented by Steve Alderton and Editor James Andrews.

Episodes every Monday.

Paid advertisement

Best bank account for your bills

Winner: Santander Edge

Santander will give you money back each month on direct debits for your bills – but sadly the top paying Santander 123 is no longer open to new customers (if you’ve already got it, then keep using it).

Instead you can choose between the Edge, Edge Up and Edge Explorer accounts, and it’s the first one that will probably earn you more cashback each year.

All three give 1% back on household bills such as Council Tax, energy and broadband, though the Edge costs £3 a month vs the Edge Up’s £5 monthly fee. That extra £24 a year for the Edge Up really cuts into your returns. The Edge Explore costs £17 but includes extra insurances, so it could be worth a look.

Though the earnings aren’t as much as they once were, this cashback via the Edge is better than nothing, and you’ll also get access to the 6% paying Edge Saver.

Runner up: Biscuit by Zopa

You can also get cashback on some bills via Zopa. It’s capped at £30 a year, the equivalent of £2.50 a month, but it covers any direct debit, so you could well use this as well as the Edge to pick up bills that are missed off.

Runner up: Monzo/Starling

If you’re more worried about budgeting than cashback then both Starling and Monzo will let you segregate money into separate pots and then assign one to pay bills direct from it.

Paid advertisement

Best bank accounts with rewards

Some accounts will pay you each month, either in cash to your account or with a freebie. You often have to pay a monthly fee and meet other criteria.

Winner: Club Lloyds

Sadly the Halifax Reward account was gutted in September and no longer gives £5 a month.

So my top pick for 2026 is the account from Club Lloyds. You can choose either 6 cinema tickets or a year of Disney+ with Ads – but once you’ve set up standing orders you can just leave the account alone. A couple could benefit from three accounts – one personal account each and a joint one too.

As long as you deposit £2,000 a month into the account you avoid the monthly fee. This is easy to do. There’s more in my full Club Lloyds review.

Runner up: Monzo Perks

This account from Monzo offers much more, but you have to pay £7 a month to access the perks. That can be great value if you need what you get. This includes:

  • a Vue cinema ticket every month
  • a Greggs treat every week
  • an annual railcard
  • Uber One membership

You also get extra Monzo budgeting features which I think are great. More in our Monzo Perks review.

Paid advertisement

Best packaged bank account

From inclusive insurance and breakdown cover to extras, sometimes it’s worth paying a fee each month for a packaged account.

Winner: Santander Edge Explorer

This account is the Edge, which I already like, plus some extras. It costs £17, £14 more than the Edge, but is cheaper than most other packaged accounts. And in return, you’ll get travel, breakdown and phone cover, 1% cashback on some debit card spending, 1% cashback on bills and access to the 6% Edge Saver. Here’s my full Santander Edge Explorer review.

Runner up: Virgin Money Club M

This account goes up from £12.50 a month to £14 from 1 February 2026, but it’s still one of the cheapest packaged options. You’ll get worldwide family travel insurance and phone cover, as well as UK and European breakdown cover for the account holders (so it’s worth opening it as a joint account). That’s decent value if you need two or three of those policies. Here’s our full Virgin Money Club M review.

Best bank account for savings

Current accounts often give you access to higher rates than elsewhere, though with limits. Here’s our guide to the best savings accounts.

Winner: First Direct

For ongoing savings the highest paying account is a regular saver that’s only open to First Direct current account holders. It pays 7% AER – and that’s fixed for 12 months. You can only add up to £300 a month into this regular saver. Read more about other regular savers here.

Winner: Santander Edge

The highest interest rate on larger balances at the moment is from Santander. As long as you have the Edge current account you can open the Edge Saver. This offers 6% on up to £4,000 – though that previously mentioned £3 a month fee needs to be factored in if it’s not covered by cashback. The rate also drops by 2.5% after a year.

Paid advertisement

Best bank account with an overdraft

If you use an overdraft you’re probably paying around 40% in interest – far more than it’d cost to borrow elsewhere. So they’re best avoided. But if you are overdrawn then it makes sense to reduce that cost ASAP.

Winner: First Direct

You can currently get a £250 0% buffer from First Direct. That’s not amazing, but it can be useful if you occasionally go a little below zero.

Runner up: Monzo/Starling

If you really need to use an overdraft then you might be able to get as low as 15% of 19% with these digital banks.

Paid advertisement

Best ethical bank account

Winner: Triodos

This account tops the charts on Ethical Consumer’s list of ethical current accounts and it’s hard to beat. However it does come with a £3 a month fee and the app is limited. Here’s my full review.

Runner Up: Nationwide, Starling or Co-op

These banks also score well. As it’s a building society, Nationwide is committed to putting the bulk of its lending towards mortgages so it can’t invest heavily in non-ethical practices. It also has positive policies in place to avoid this.

Starling has the edge over its challenger bank rival Monzo, while Co-op is the top-ranked from the other high-street banks.

Best “I only want one” bank

If you don’t want to have multiple accounts, and really want everything in one place, then these banks combine multiple extras.

App and perks: Monzo Perks

As long as you would spend £84 a year the perks included, the extra budgeting features on an already excellent app make Monzo Perks on of my top account for 2026. The only let down is on savings rates and there are never any switching deals.

Cashback and savings interest: Santander Edge or Edge Explorer

As long as you pay bills, you may as well get cashback on these. On top there’s access to the 6% paying Edge Saver account. The app is average though. If you need travel insurance and breakdown cover, the Edge Explorer is a good upgrade.

Interest and freebies: Club Lloyds

It’s too early to say whether First Direct Perks will be worth it in the long time, so I also think Club Lloyds is also worth a shot. The app is pretty good, and the six cinema tickets or year of Disney+ with Ads is potentially worth £60 a year and there’s a decent (though not best buy) monthly saver at 6.25%.

Ethics and loyalty: Nationwide

Finally, if you want your bank to be doing some good AND get something in return, Nationwide is well worth a shout thanks to the annual Fairer Share payment. It’s not guaranteed for 2026 but it should be worth £100 and offer access to a decent 18 month fixed saver.

Read next: other bank reviews

Paid advertisement

Should you regift an unwanted present?

The do’s and don’ts of passing on unwanted or duplicate gifts.

There’s a good chance at some point each year you’ll be given a gift you don’t want or need. Unwanted presents are frustrating and disappointing but also a bit awkward. So what do you do with it?

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

What to do with an unwanted present

The worst thing you can do with an unwanted gift is just throw it away. Not only are you adding to landfill, but the money spent by the gift giver has been wasted. Not much better is just putting it out of sight in a cupboard or drawer. It’ll probably just sit there gathering dust for a few years until you have a clear-out, and then go to the tip too.

You could try to make use of whatever you’ve been given, even if you don’t like it. But why wear a jumper, use the vase or eat some chocolates that aren’t to your taste simply because you feel you should? It’s not your fault the gift wasn’t right, so you shouldn’t feel guilty about it. Saying that, you might find you later learn to love it.

You could try to sell the present, though the admin and fees associated might be enough to put you off. It’s worth having a look online just to see what similar items have gone for, but it’s something likely only worth it for higher-value items.

Perhaps the best option, if you’re brave enough, is to be honest about the present. Tell the gift-giver why it’s not right and ask if they would be able to give you a gift receipt so you could exchange it, or if they would do it for you. This will be a lot easier if the gift is something you already have than if it’s just not to your taste. Still, it’s worth a go.

But if you can’t see that working, your next best bet financially is to pass the present on, also known as regifting. This can be controversial. Imagine how you’d feel if a gift you put thought into wasn’t just unwanted, but given to someone else? Not great. But it’s better to know someone, somewhere is making use of it rather than it getting chucked away.

And if you can avoid the awkwardness, then it’s a winning strategy. You’re giving someone a gift they hopefully will like, you’re helping the environment by not chucking it away and you’re saving yourself some cash by not having to buy something new.

So here a few simple rules and tips to help you navigate the minefield of regifting.

Do: only regift to someone you think will appreciate the present

Regifting doesn’t mean you can just palm off an unwanted present to any old friend or family member. If they won’t appreciate it, you’re just passing the buck, and it could still end up in the bin.

Instead have a think about who might like it, and there’s a good chance you’ll have a few contenders. Most unwanted gifts aren’t bad gifts. They might simply not be to your taste, or perhaps be a duplicate of something you already have.

Don’t: regift everything

It’s worth taking into account any politics within your family or friendship groups. It might be better to keep hold of something and just bring it out from time to time to avoid any rifts. Yes, that could mean keeping hold of that awful painting your gran got you. But that might be better than the potential fallout if she found out.

Also some gifts are just plain bad. The kind you can’t understand why someone would manufacture it, let alone buy it. If you’ve got one of these and there’s no one you can think of who would like it then don’t regift it.

Do: have a regifting box

It’s worth keeping any unwanted gifts together in one box or cupboard. This way if you need to buy a present you can check what you’ve got and see if there’s anything suitable.

Don’t: forget who bought you the unwanted gift

There’s a danger with regifting of whoever you gave the gift to finding out, or perhaps even getting it back themselves. You hear stories of presents being passed around the same group year after year. Neither of these scenarios are desirable.

To avoid this, make a clear note of who gave you the gift and when. Then when you regift it, make sure it’s given to someone in a different circle.

The best deals

Find our picks of the best offers in our dedicated deals library

Do: remove any tags or personalisation

Take a good look at your unwanted present. Have they inscribed a message in a book? Is there a tag stuck to the bottom of the box that you missed? If you’re sure there are no tell-tell signs the item is regifted then it’s fine to re-gift.

Don’t: regift anything that’s been used

Any unwanted present you want to pass on has to be in as good a condition as if you’d just bought it yourself. Packaging is key here so ensure any tags are intact and the box unopened. It’s important to check use-by dates on any food or drink gifts too.

Do: remember charity shops

Finally, as we’ve mentioned a few times above, you can also give an unwanted present to a charity shop. But don’t just dump a bag outside the shop. Take it in and see what they will take and then you can deal with anything they reject.

How we saved thousands on our wedding

The list of pressures surrounding a wedding is too long to list. It’s your BIG DAY. It has to be PERFECT. But worries about everything going to plan, or if people will have a good time, are dwarfed by the general insaneness of just how much weddings can cost.

The average spend on a wedding in the UK is £30,111 – well, according to Brides Magazine. For some reason, they include the gift list in their sums (why?), as well as engagement rings and the honeymoon. Stripping them out the total cost comes to £20, 261.

Obviously, you still need to pay for the engagement ring and honeymoon; but I don’t count them as part of the wedding day itself. Nonetheless, spending £20k on one day – ONE DAY – isn’t something you’re ever likely to repeat.

I got married last year (yes, I know I promised this post ages ago) and, being dedicated to getting the best value from everything I spend, I wanted to share with you how we managed to have a pretty awesome day AND stay on budget.

We didn’t have a frugal wedding – we still spent £16,000 – but I’m confident anyone who attended would be surprised we didn’t spend a lot more, particularly for a London wedding; and that’s because we worked hard to get as much for our money as possible.

Here’s how we planned and paid for a pretty fantastic day.

Setting the budget (and the date)

When we got engaged, Becky and I were both travelling South and Central America having taken redundancy from our jobs. So, we had to start planning our wedding without knowing when we’d start working again.

This was probably the most important decision we made; we didn’t let the date decide our budget, we let our budget decide the date. We could easily have chosen a day six or twelve months away – but we knew we’d not have enough money saved up to afford the day we wanted. So we looked at existing savings and made a guess on how much we’d be able to save each month.

With this in mind, we chose a date two-and-a-half years after our engagement – a long wait by today’s standards. But any earlier and we’d have had to compromise on the day; there was no way we were going to get into debt to fund it.

Deciding the guest list

Money wasn’t the only factor that shaped our guest list – we didn’t want something so big it lost its intimacy – but it played its part.

We could only afford 70 guests for the sit-down meal, so that’s how many people we invited. It wasn’t easy – I ended up inviting my aunts and uncles, and most of my friends’ partners just to the evening – but I think this is where you can totally lose control of the budget.

You probably will lose some people this way, but hopefully most people will understand and enjoy themselves at the parts they do go to.

Choosing reception venue and food

As with any big purchase, we shopped around to compare what was on offer and the prices we’d have to pay. We looked in London, where we live, and Yorkshire, where Becky is from.

Unsurprisingly, prices jump as soon as you mention the “w” word. Working out costs is also incredibly complicated. Some venues will offer all-in, others will have different charges for the venue, staffing, catering, ceremony etc.

We eventually chose the Hawksmoor restaurant in London’s Guildhall for our wedding reception. It held special memories for us and cooks the most amazing steak.

Unlike many of the other places we looked, they operated a minimum spend system. We had to pay up-front, by instalments, £9,500 plus 12.5% service charge. We also managed to negotiate with them a refund of £2,000 if the bar spend exceeded that amount.

We calculated this cost less than a separate room and catering hire at other venues we liked, but with top quality food (it’s genuinely fantastic food – regarded as one of the best places to get steak in the UK), fantastic wait staff and a really lovely venue. Of course, this was only possible as the restaurant closes at the weekend – it’s in the City of London which is a ghost-town at weekends with all the bankers back in their country retreats. To get one of their other restaurants in Covent Garden or Mayfair to ourselves would have been far far more expensive.

All-in and after the drinks refund, £8,700 covered the venue (with a late licence ’til 2am), a few canapés, welcome cocktails, a three-course meal for 70 guests, wine, evening food (lobster roll, yum), the service charge and a couple of drinks each for another 20 evening guests. Not cheap, but I’d say outstanding value for money.

We’d have liked to have provided more free booze for our guests, but our budget didn’t allow it. However, we did save on the fizz to toast the speeches. We found it was cheaper to buy some decent supermarket prosecco (on offer, of course) and pay the corkage charge than buy bottles direct from the venue.

Getting what we wanted for far less

I could write a hell of a lot more here (if I wrote about every element in detail then this article would be well over 2,000 words – another blog post – or two – perhaps), so for the sake of brevity here are other ways we saved.

Buying the dress for less

Becky didn’t choose the dress based on the budget, but it just so happened it was cheaper for us to order this dress from the States and fly to New York to collect it than buy a traditional wedding dress! The savings made freed up cash to spend elsewhere.

My tux was also a bargain. I knew what I was after and happened to chance upon the online Moss Bros sale with one left in stock of exactly what I wanted – for just £79! Becky also found great deals on high-street dresses for the bridesmaids.

Finding the right suppliers

Any London photographer with a decent portfolio will easily cost you £1,500 to £2,000, if not more. We cut this drastically by using someone out of London. She’d taken pics at a friends wedding in Stratford the year before, which we knew were good, and she was happy to come to London for our wedding.

Cakes also don’t come cheap, but, thanks to a huge amount of research by Becky (research by Becky was key to so many of our savings), we found a relatively new baker whose prices were a fraction of others we looked at, but just as tasty, and if anything, more talented in decoration.

The quotes we got on flowers were the most ridiculous, but we found one amazing florist who was happy to work within our budget. She and Becky had very creative ideas to get the most for our money on tables, bouquets and buttonhole flowers. Less really is often more – when it’s done right.

A little bit of DIY

We were also lucky that the venue looked pretty fantastic as it was. We simply added some cheap fairy lights from Amazon to give a little sparkle.

In fact, Amazon, along with Hobby Craft, Not on the High Street and Etsy, was our friend in helping us buy decent quality materials to boost our invites and table plan.

Breaking with tradition

We didn’t buy favours for our guests, choosing instead to give them more booze. Likewise, we didn’t kit out the grooms people in matching gear.

We also asked our guests to contribute to our honeymoon rather than buy us stuff we already had. Not everyone did this, but it made our three weeks in New England far more affordable and allowed us to put more cash into the wedding day itself.

Saying no when we couldn’t afford it

I really, really wanted to hire a mariachi covers band (the ones from those Doritos’s adverts). They weren’t actually that expensive compared to what I know friends have paid for bands, but it was too much for our budget. So sadly we said no. But my carefully curated playlists did the job perfectly, so we didn’t even need a DJ – though we did shell out for a dance floor, PA system and lights.

As much as we’d have liked to have stayed in a posh hotel the first night, knowing we’d have got there about 3am and left at 10am meant it was a bit of a waste of cash – better spent on the first night of our honeymoon. In the end it was lovely to be back in our own bed.

You can read more – and find our suppliers – in this article Becky wrote for Boho Weddings (even though ours was absolutely not Boho!)

I really could keep on writing about this! But I won’t. Instead I’ll leave you with what might have been – the Mariachis singing East 17…

Be Clever With Your Cash is Financial Blog of the Year!

Wow, this was a bit of a surprise. Last night Be Clever With Your Cash won a big award – Financial Blog of the Year at the 2017 Headlinemoney Awards.

These annual awards recognise the best in personal finance journalism, with hundreds of journalists and publications nominated from the likes of the Sunday Times, Which?, Moneywise, Financial Times and Money Saving Expert.

Last year I was runner up, or highly commended, in the same category and that was amazing. And this year I thought that might be the best I could hope for – until they announced they were only going to announce a winner.

Still, it’s a fun event to attend. I knew I’d be able to catch up with lots of blogger and journalist friends, and I was able to use the gathering as an opportunity to record my latest Cash Chats podcast.

So it was a fantastic, unexpected result when the host Jeremy Bowen announced Be Clever With Your Cash as the winner!

It’s lovely to get the recognition for all the work I’ve put into the blog, but I guess it also validates that I’m giving you useful information in an entertaining way.

headlinemoney awards 2017 Andy Webb
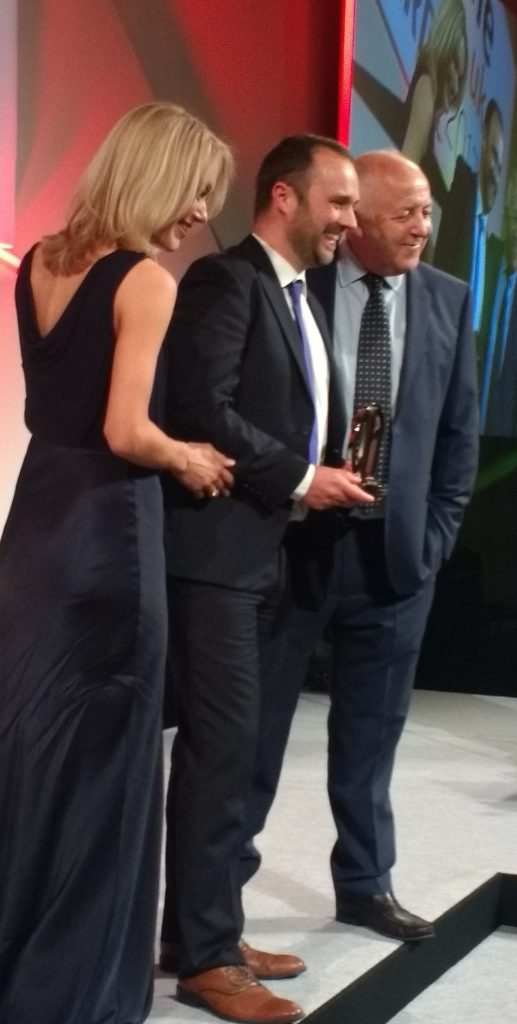
Picking up the award from Georgie Frost and the BBC’s Jeremy Bowen

As part of the nomination process, I had to share three different articles from 2016 which best summed up my work. So I thought it would be good to share those same posts with you.

I selected each to demonstrate that a big part of the blog is showing I put my money where my mouth is, that I really live the articles I write. I also wanted to show that brands can’t buy my endorsement or a place on the blog – Be Clever With Your Cash truly is independent.

The first is a fun look at my addiction to reduced food stickers (it was picked up by BBC Online!).

>> My addiction to yellow reduced food stickers

The second is my reflection on the post-Brexit currency crash, using a forthcoming trip as a way to get you all to think about your holiday money.

>> Currency crash: My holiday just got A LOT more expensive

Finally, showing that blogs can start bigger stories, my investigation into dodgy iPhone handset pricing at O2 , which was then covered by Mirror Money and Moneywise.

>> O2’s iPhone rip off


Listen to the phone scammers trying to take over my computer

This scam could let tricksters take over your computer – and steal your cash.

A couple of months ago I shared how scammers had repeatedly called my landline pretending to be from TalkTalk.

Well, a new bunch are at it. The latest con artists called my mobile phone and pretended to be from BT. So I grabbed a camera and recorded what they said. I hope the video gives you an idea of what to look out for – and what to avoid.


I think you could tell that was a scam from the off, but people do get sucked in by these all the time. Often it’s the panic that they could lose everything that prompts them to follow the instructions.

If I’d done as the scammer said they could have taken over my computer to steal my details or, like with the recent NHS hack, locked it using what’s called ransomware.

The basics to beat scammers

Phone, email and text scams are getting more sophisticated, so you always need to be on guard. But the basics to keep safe are simple.

  • Be wary of any unsolicited contact
  • Don’t give any personal details unless you are sure it’s legitimate
  • Don’t download any software you’ve been instructed to over the phone, or click links in emails or texts
  • Hang up and call back on a different line using a number you find

Read more about protecting yourself from phone scammers in my article How phone scammers tried to rip me off


Be Clever With Your Cash turns four!

Another year gone, and so much to share!

Today is the fourth birthday of the blog, so as is now the tradition I wanted to share my highlights from the last 12 months and reflect on some of the big changes that took place.

The site

What really blows me away is just how many people are reading my little blog. In the 12 months up to today just under one million people read the blog. ONE MILLION! I hope I’ve been able to save people a lot more than £1 each, but even if that’s all that’s been saved, that’s still £1 million!

There’s been a big increase this year and in part I think that’s down to me moving the blog from something I did in evenings and weekends to on average two full days a week. Alongside a redesign last March, Be Clever With Your Cash has benefited from more time – and more writing.

The articles and deals

And I’ve written a lot. In the last year I’ve published 125 articles here on Be Clever With Your Cash. And the scary thing is I’ve stil hundreds of ideas I didn’t have time to write about! Plus there were so many fab deals I was able to find and share with you.

I’d also imagine you didn’t get a chance to read every single one of those – even if you are the most dedicated of readers ;). So here are my highlights from the last year:

I also started making a lot more video content for you on my YouTube channel, with this my fave. I was first with the story that morning, and the video was picked up by a few national newspaper websites. Lots more to do here in 2018 though!

I’ve also produced 44 episodes of the Cash Chats podcast. Here are a couple of my favourites which I think are well worth a listen.

A big award win

I guess the highlight of the year was picking up Financial Blog of the Year at the 2017 Headlinemoney Awards. It’s billed as the Oscars of the personal finance journalism world, so to win best blog was just amazing!

I also was delighted to win Best Money Saving Blog and Best Money Vlog at the 2017 SHOMOs awards, which recognise the best of UK Money Bloggers. Ok, yes I do run the awards, but I’m not involved in the judging so it was lovely to be recognised by my peers!

More established

One of the weirdest things about how my career has changed since starting the blog is that I’m now asked to appear on TV and radio as an expert. I’m used to sitting behind the camera and microphone, not in front of it!

Though I’ve done less telly this year, I still popped up on Rip Off Britain and Right on the Money, both on BBC One. And I’ve also done a lot more radio, including talking on BBC 5 Live a few weeks back, and regular appearances on BBC Radio Berkshire and BBC Radio London.

I’ve also continued writing for Moneywise magazine and Reader’s Digest, alongside guest blogs and articles for many websites.

It’s a genuine delight for me that I get to share my ideas and passion with so many people. Hopefully 2018 will see this continue!

What do you think?

I’d love to know what you think about Be Clever With Your Cash so I can make it even better for you. If you have a few minutes, please do fill in the survey below.

Thanks,

Andy

Be Clever With Your Cash is Financial Blog of the Year (again!)

I’m really proud to share with you that I won an award this week. For the second year running Be Clever With Your Cash was named Financial Blog of the Year at the 2018 Headlinemoney awards.

The Headlinemoney awards are a swanky affair and a big deal for personal finance journalists. When I won last year it was a huge shock, but I’d say this year I was even more surprised as I really thought there was no chance of getting it two years in a row.

But as the presenter, BBC journalist Sarah Smith, began by saying something along the lines (details are vague as it was all a bit of a blur) of “For the second year…” it clicked that I’d won. It’s a very surreal and humbling moment to have your name read out and then go up on stage in front of hundreds of personal finance journalists and PRs. But I was, and still am, absolutely delighted.

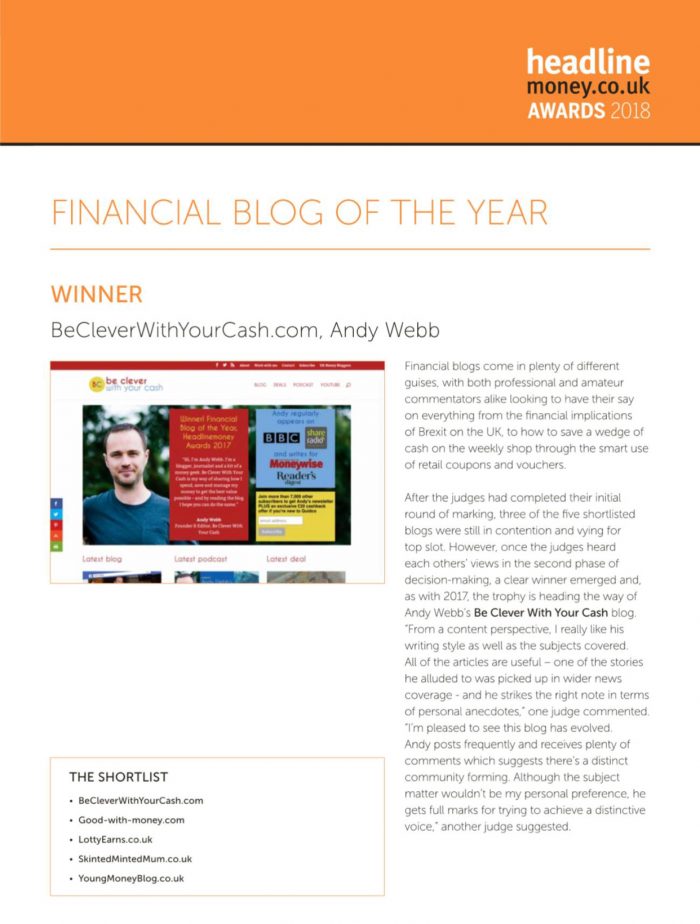
Headlinemoney awards 18 Financial Blog of the Year

As part of the process, I had to submit three articles from the blog – the ones I felt demonstrated why I do what I do. So I thought it would be good to share those same posts with you.

I selected each to demonstrate that a big part of the blog is showing I put my money where my mouth is, that I really live the articles I write. I also wanted to show that brands can’t buy my endorsement or a place on the blog – Be Clever With Your Cash truly is independent. So here they are if you missed them last year.

The corner shop stamp rip-off
How I tried to learn investing, but ended up blagging it
The 1p trick to get your “free” Waitrose tea or coffee

The judges’ comments


Also, do check out some of the fantastic and lovely bloggers who were also nominated, including Charlotte (LottyEarns), Becky (Good With Money) and Jane (Skinted Minted Mum) who are all from my UK Money Bloggers community, as well as Iona (Young Money).

A little perspective

As chuffed as I am with my win, I wanted to tell you about another award on the night. My category was immediately after the Lifetime Achievement award, which this year went to Daily Express journalist Geoff Ho. If the name sounds familiar, it could well be because in June last year he stood up to the terrorists attacking London’s Borough Market. His first-person account of the attack is a difficult read, but if you can take a look it shows why he received such a rapturous standing ovation.