I’ve had credit cards over the years but rarely used them. Now thanks to some great deals, I put everything I can on my American Express card. Here’s why it’s one of my amazing savings.
** This is the first in a series where I’ll share some my favourite ways to save. Be Clever With Your Cash is completely independent and the brands featured have nothing to do with the posts. These are just the companies or products which I’m a big fan of for saving or making money. **
I’ve always managed my money well. So when it came to credit cards I only used them for you overseas spending or when I wanted the extra protection you get with big purchases.
That all changed a year ago when I signed up for my first American Express – or Amex – card. In year one the card earned me an extra £350!
Here’s why it’s an amazing saving:
1. Cashback
With the Platinum Cashback credit card I get 1.25% back to my account for every full £1 I spend. For the first three months it was 5% (up to a total of £125). There’s a £25 annual fee but I’ve worked out it’s worth it.
Last year I earned £200 with the Preferred Rewards Gold card. The second year had a £125 fee so I cancelled it and applied for the Platinum card.
I spend as much as I can on this card, then have a direct debit to pay it off in full each month. That means I can earn an extra month’s interest on my savings in a high interest account and max the cashback.
The only downside is that there are still places that won’t take it, but that number is getting smaller and smaller. Other cards also give you money back on purchases, but American Express is my top pick.
2. Statement credits
The idea is you register your card for specific offers. When you spend the required amount you’ll get a credit to your statement. Some are open to all, others tailored to you and your spending. I’ve never had a product that offers so many deals.
In the last year some I’ve used have included:
Free £5 for writing a TripAdvisor review
£15 when you spend £50 at Gap
£5 when you spend £10 at Tesco
£25 when you spend two lots of £25 at the London Restaurant Festival
£25 when you spend two lots of £25 at selected shops (including Space NK and Argos)
£10 when you spend £50 at House of Fraser
£20 when you spend £100 at Westfield
£10 when you buy a month’s Spotify (at £9.99)
£10 when you spend £30 at Gourmet Burger Kitchen
£5 when you spend £10 at a selected small business.
There are dozens more throughout the year, including shops such as Top Shop, Selfridges, Curry’s and much more.
You can get a card for your partner, or have more than one card yourself, and the statement credits offers are usually per card rather than card holder, so you can increase your benefits.
3. Great member perks
American Express sponsor plenty of events, which means members can get discounts and special access on tickets. I’ve picked up tickets for otherwise sold out shows, had early bird access to booking the recent Mastercard pop-up and recently picked up a free behind the scenes tour of the National Theatre.
There have also been around a dozen free apps given away this year, with more to come.
4. Amazing customer service
It’s rare that something goes wrong, but when cashback or a statement credit haven’t gone through correctly, I’ve been massively impressed by the service. Based in Brighton, they’ll sort your problem quickly, politely and without a queue. I’ve also heard some great stories of the help they’ve provided people with card issues overseas.
I found two TVs on sale which were practically the same – but had a £250 difference in price.
Sometimes a new version is blatantly different, even if the main reason for change is to generate more sales. A new football kit, for example, will look different to the previous season’s. Sometimes the updates are hidden but make a difference, such as the change from an iPhone 7 to an iPhone 7S.
Now, whether they are worth paying for is up to you. The older versions still do the job they were designed for, but at least there are tangible changes to partially justify shelling out for an upgrade. But that’s not always the case.
A tale of two TVs
One of the families I recently visited as part of Channel 5’s Shop Smart Save Moneywas after a new TV. Prior to my visit they’d spotted a 49″ Sony model at Curry’s. The cost, a hefty £799. My job was to help them make some savings, and mum Debs had already searched online and found it for £50 less at Huges Electrical. I couldn’t beat that price by much, just a few per cent using cashback sites. But I noticed this was a brand new model. So I had a look at the long and confusing model number: Sony KD49XF7073SU.
The model number is the key to work out exactly what you’re getting. It just doesn’t make much sense! However a quick Google and I found an explanation of the different characters. For this TV, ‘KD’ just means it’s a Sony Bravia TV while ’49’ is the screen size. ‘X’ signifies it’s a 4K TV. The next one is the model year, with an ‘F’ telling us it’s a 2018 release.
The next two digits show the spec, so the higher the number, the more features it has, while the next two numbers are cosmetic such as different colours. While the final two letters (if they are mentioned) tell us it’s got a UK plug.
So armed with this information I had a quick search for Sony TVs with similar model numbers And not only did I find a similar number, I found an exact match with just one difference. There was an ‘E’ for 2017 in the model number. And this Sony KD49XF7073SU cost just £499.
Ok, you’re probably thinking a newer version of something should be better right? Why would you upgrade something that’s perfectly fine if you haven’t improved it somehow? And normally that’s the case. But when I compared the specifications for these two TVs on the Sony website, all the features looked the same.
In fact they were so similar the only differences I could find were the inbuilt speaker and the stand design. Ok, you might prefer the look of the 2018 stand. And the speaker might be better. But are they worth £250? If like the family after the TV it was going to be hung on a wall, the stand became irrelevant, and many people plug in a soundbar so it doesn’t matter what the built-in speakers are like.
So in this instance, the latest model isn’t an upgrade, it’s just a way for Sony and the retailers to make more money. But you can use it do save decent money as retailers look to clear out older versions by cutting prices.
Still want the new model?
Comparing prices is obviously a great way to save money, but while you’re at it, also check out the price history. This could help you work out whether just waiting a few weeks or months could save you a little more cash.
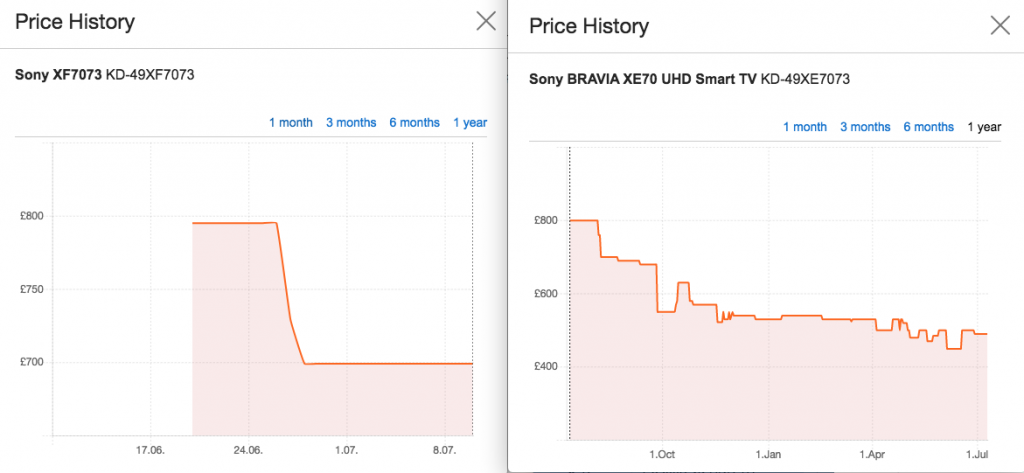
The 2018 model of this TV was released in mid-June at £799, which was the price listed when I did the research. Using price comparison site IdealoI can see that within two weeks it was available for as low as £699. So with most tech, this suggests it’s not worth getting it in the first few weeks.
And if it follows the same pattern as the 2017 model, it could well drop again in a few months. The 2017 model was below £600 by late September. So finding out the price history of similar models could help you know the best time to buy.
How to decipher model numbers
In most model numbers each character represents some variation from a similar version. It could be the age of the model as with the TVs above, or it could be additional features – which you won’t necessarily need.
For example, when I was looking for a new oven I found one letter difference between the two models. One ended with a ‘B’, the other with ‘BP’. The price difference was £240. so what was the ‘P’? It essentially stood for “Pyrolytic” – an enhanced self-cleaning mode. Yeah, nice to have, but not for £240.
Once you’ve worked out the differences, use this information then to swap characters, or ditch them completely to see if there’s a similar but cheaper alternative.
Find a guide to model numbers
Ideally you’ll find a guide online like I did for Sony, though this won’t always be possible. But it’s worth searching, or even asking in store.
Look for obvious differences
If you look at a couple of similar models it doesn’t take long to work out some of the characters. An S might stand for Silver and a W for White. Easy. A higher number usually means it’s higher spec, and so on.
Other characters might require a little more work, but as with the oven I bought it can be worth it. Often all you need to do is read the description online and see if there’s a key word different, such as the Pyrolytic feature of the more expensive oven.
Compare features on the manufacturer website
Sometimes though, codes change significantly when a new model is released. When this happens it’s best to use the manufacturer’s website as you get to compare all the models, not just the ones sold by a retailer. You can then use filters to narrow down your search based on the features listed. Here’s an example.
Last week I spotted a Miele washing machine on special offer. Our current machine is working OK, but it’s over a decade old. Being Miele, the new one wasn’t cheap, but as it was from 2016 and not listed on the Miele website I assumed it was an end of the line model – meaning the clearance price could have been significantly less than the current model.
However, I couldn’t find it on sale anywhere else in the UK to compare, and there were lots of models with very similar codes. There’d be no point buying if the discount was only £50!
So instead I found the full specs for the washing machine on Miele’s Hong Kong website, then used the search function on Meile’s UK site to filter out any current machines without those features. I managed to nail it down to one model which was practically the same apart from one enhancement. The difference in price was £700!! However, it was still too much to splash out right now, as tempted as I was!
Something I love as the resident money expert on Channel 5’s Shop Smart Save Money is that they don’t just accept that I can save people cash – they want me to prove it! So every week I’m sent to meet a family who could do with some extra money and challenged to find them at least £1,000 of savings in a few hours.
Now I’m confident I can do this for pretty much any family as even the savviest won’t be doing everything – and they probably don’t need to. But I’m a little bit different as I genuinely enjoy finding new ways to get better value for my money. So when I meet the family I’ve probably got something up my sleeve!
My first challenge was from Sophie and Rakesh who live in Birmingham. They were a great couple who admitted to sometimes spending money they shouldn’t – including £300 on a piano neither can play! But they’ve got hopes to move into a house which will be the family home for a good few years, and need cash to build up the deposit.
So here’s a bit more info on each of the savings I found. If you didn’t catch the episode live, you can watch it on Channel 5’s catch up service.
Their car
I started before I even got into the house. Their car has seen better days. Handed down from Sophie’s dad it’s been good to them but now the cost of keeping it going was becoming prohibitive. Last year they spent £820 making it roadworthy, and they’ve got an MOT around the corner which they don’t think it would pass without even more money thrown at it.
Not only that, but they hardly use it. Sophie estimated they drove it just 10 to 15 miles a week. That’s mainly because Rakesh walks to the train station to get to work, and Sophie uses the bus. The car journeys were pretty much just to take son Leo to nursery, but that was only 10-minute walk away.
So I suggested they should ditch get rid of their car. Yes, I know that sounds a little extreme – but I think a good option for them as the savings were pretty decent, even using a conservative estimate on repairs. They’d also get around £200 for scrapping or selling the car. So the money back in their pocket would break down like this:
£552 – Car insurance
£205 – Road tax
£472 – Repairs (average annual cost in the UK)
£200 – Scrapping or selling
That’s a huge £1,429 year!!! Of course, that would have been too easy. Challenge over. And realistically Sophie and Rakesh would still want to make the odd trip. So having no car at all probably isn’t feasible.
But for the amount they use the car I think they could be better off using a car club. The one I found five minutes from their house costs £50 a year to join. Then it’s £4 an hour plus mileage. But how much will that cost over the year? Well, a 200-mile journey from their home to the seaside at Weston Super Mare would cost £71.30. If they do a big journey like that once a month (which they probably wouldn’t) and a handful of shorter journeys I still don’t think they’d spend more than £1,000 a year on the car club.
Total saving: £400
Unused gift cards
I like to get my hands on the families’ wallets and purses to learn a little about their spending, so once inside the house I asked Rakesh if I could have a nose inside his.
The first thing I noticed was just how many gift cards he had. There was one for House of Fraser, another for Asda, a handful from returns to Wickes and a few more. What’s the problem with that you might ask?
Well, most gift cards have expiry dates and easily run out, they can get lost or forgotten, and they become valueless when companies go bust – that £50 House of Fraser card is a good example where the money could be at risk. In fact, an estimated £90million of the £6billion spent each year on gift cards is unused. A total waste of cash.
The cards in Rakesh’s wallet had all been in there for a long time. Sophie was proud that she’d got 4% off the Asda card – but they’ve been shopping elsewhere and not used it. They’d even been back to Wickes and forgotten to use the gift cards! So I think they had two options if they didn’t want to lose £200. They could use them as soon as possible (ideally on things they need) or sell them via online marketplaces. They’d obviously not get the full price for the latter, but even a 10% loss is better than letting them become valueless.
Total saving: £180
Bank accounts
Regular readers will know I’m passionate about switching banks and getting some kind of deal. Sophie and Rakesh had a few accounts between them, including a joint Natwest account which earned cashback on bills – great. But both also had one account each which wasn’t doing much in terms of rewards.
So I suggested a simple switch to immediately help the household finances. Moving from their respective banks to Marks & Spencer Bank would earn each £125 in M&S vouchers. Then they get another £5 voucher a month for a year. And both of them could do this! They could use these on food or clothes for Leo and put the money they’d normally have spent here towards their savings.
Now to get the £125 voucher you do need to fully switch your old account including two active Direct Debits. This means closing down the old account. But all your payments in and out are transferred for you, and monitored for at least three years. I’ve done this a lot and it’s been fine every time, but if something did go wrong there’s a guarantee which means you wouldn’t be out of pocket. For the extra £5 a month, account holders need to pay in at least £1,000 a month and keep those two Direct Debits.
Total saving: £370
Broadband
I had a look at their bills too, and one stood out. Sophie and Rakesh are currently paying £23 for phone and broadband from Sky, but that is due to go up to £30 odd in the next month. So it was definitely time to switch.
The best deal I could find at the time of filming was with Plusnet for just £10 after cashback. It was the same speed and the price was locked for 12 months – but £20 less a month.
Total saving: £240
Packed lunch
Finally I wanted to tackle Rakesh’s pricey lunch habit. Apparently, even when Sophie made him a decent meal to take to work, he still popped out to get a Pret or burrito. This isn’t uncommon. And I get that it’s nice to mix up your meals each day. But the savings you can make are huge.
The average people spend when they buy a lunch near work is £1,800. That’s roughly £7 or £8 a meal. See how quickly it adds up! Of course a packed lunch isn’t free – whether it’s sarnies or leftovers you still need to pay for those ingredients. So the average spend here is just £600.
But Rakesh wasn’t going to do this every day. So instead I suggested doing this just two or three days a week. That should make it easier to stick to, and still gives a massive saving of £600 a year.
Total saving: £600
How did I do?
Well, if Sophie and Rakesh take all of these savings on, they’re going to be better of by £1,790! So I smashed the challenge in my first week. I’ll need to reign it in for future episodes otherwise there’s a chance I might run out of new tips to share.
You can watch me on Shop Smart Save Money on Channel 5 every Wednesday in June at 8pm.
In my second £1k challenge for Shop Smart Save Money, I travelled to Matlock in Derbyshire to meet Debs, Neil and Amelia.
I’m really enjoying seeing how my suggestions for savings can work for families in real life. Of course the idea isn’t to completely fix the family’s finances, but just to find a handful of manageable changes which can bring in some extra cash. My target was £1,000 once more, but the challenge this week was a lot tougher as mum of two Debs is on top of a lot the things I’d suggest. Still, I was confident I could find some easy extras to save a grand. Here’s how it went.
Using loyalty points
Debs had her purse by the front door so I had a little look inside. Straight away I found Tesco vouchers which had expired, and Debs told me they often forget to use the points earned via Clubcard too. She hadn’t used any for over a year, and some had already gone out of date. Since Clubcard vouchers last for two years from issue there were a few more approaching expiration. It’s a waste of money to not use these. Debs said she was unlikely to boost the points, so rather than lose the £40 she had sitting in her account, I suggested just spending them in-store on her next shop.
Saving £40
Getting a new mobile phone
The whole family is on Vodafone, spending about £80 a month. Youngest daughter Amelia’s contract is about to end and she was planning to upgrade to a new iPhone 7 as part of the renewal. This wouldn’t have been cheap, working out at £9.99 upfront and £43 a month, and she’d have been tied in for 24 months. The total cost would have been £1,041 over those two years.
A better option, and this is what I do, is to buy the new phone upfront and then get a SIM only deal. Most of the time doing it this way will work out cheaper – though it’s worth checking upgrade options just in case there’s a special offer.
For Amelia, the best bet for the iPhone was direct with Apple. It’s just relaunched a 0% interest plan, so you can spread the cost of the handset out over 12 months. An alternative is to buy it on a 0% interest credit card which may give you more time to clear the cost, though you obviously need to make sure you do that before the 0% period ends.
Then for the data, calls and texts there were quite a few cheap options. I suggested one using the ID network (which works over the Three network) for £10 a month, though she probably could have gone for one a little cheaper if I’d had time to look at how many calls she actually makes and how much data she uses. This contract was only for 12 months, so she’d have more freedom to look at deals again in a year.
The total cost for the phone and SIM over two years would be just £789! A massive £252 saving. However, since the challenge is about annual savings, I halved that to £126 to add to my running total.
Saving £126
Selling an old mobile phone
With a brand spanking new iPhone, Amelia didn’t need her current iPhone 6. She could pass that on to another family member, but if she (or more likely Debs and Neil) wanted to cover some of the costs of the upgrade then it’s worth selling.
Personally, I use eBay when I sell old handsets as I’ve found I can get a little bit more cash. But the family weren’t keen on the hassle so instead I suggested a quicker route which was to use online comparison sites. When I had a look she’d get £80 for her phone, which was in very good condition.
Saving £80
Cutting down Sky costs
Debs and Neil spend £67 a month on Sky every month. A huge £804 a year – and that’s with a discount. They have all the channels, so entertainment, movies and sports. But I had a look at their Sky + box and most of the recordings were of programmes on free-to-air channels, with the odd drama from Fox or Sky Atlantic. They hardly watch the movies and Neil only really watched Manchester United matches on Sky Sports.
So instead I suggested they got rid of Sky TV completely and replace it with NOW TV. Sky actually owns NOW TV, which is an online streaming service like Netflix or iPlayer. You can watch channels live or on demand, but you can’t record them. However the savings are massive.
They admit they don’t need the Sky Cinema channels, but they do want to keep the normal TV ones. A year of these with a NOW TV Entertainment Pass (and a box to connect to their TV) would cost £57 for a year. In fact there are often so many deals I’d expect they’d be able to get it for less if they wanted.
I had a look at how often Man Utd were on Sky and found on average it’s 24 games a season. If Neil got a day pass to watch each of these games on NOW TV the total cost would be £191.76. Far cheaper than subscribing to Sky. Again, he could probably get these cheaper by looking for deals or taking out the odd week pass.
The only downside would be the Sky + box would stop working, so they couldn’t record the free channels. But for £125 they could pick up a BT YouView box. We’ve got one of these and it works great. Even with this purchase the saving from just one year without Sky is massive, and will be bigger in year two.
Saving £430
Trying a smaller energy company
Debs already fixes her energy, but with her 12-month deal about to end she planned to fix again. She said she’d stick with one of the big companies, possibly staying with NPower. That would save her £432. Great. But I couldn’t claim that one for the challenge as she as already going to do it.
However, I took a look on a comparison site to check out the other options, and in just a few minutes I found a small provider called Arvo could beat the price. It had decent reviews and no exit penalties, so Debs could switch away if she wasn’t happy with the service. And this was £108 cheaper than the Npower fix, plus she could claim £25 cashback.
Saving £133
Buying a new TV
Shop Smart Save Money and Be Clever With Your Cash aren’t just about saving money. A big part of both is getting the best value when you spend money so I asked if there was a big purchase the family were planning on making.
They came back with a new TV, showing me a Sony model they liked the look of in Curry’s at £799. Debs had already found a £50 off deal with Hughes Electrical. I couldn’t find it cheaper than that. But I did notice that this was a brand new model, literally out this month. The previous year’s model is still available, and having contacted Sony, the only significant difference is that it has a different stand. So it’s essentially the very same TV! And that was on sale at John Lewis for £499.
Saving £250
How did I do?
So I managed to beat the challenge once again. The total this week – if the family take all my suggested actions – is £1,183.
You can watch me on Shop Smart Save Money on Channel 5 every Wednesday in June at 8pm, and you can read about the other families I’mhelpingas part of the series.
My final £1k challenge of this run of Shop Smart Save Money covers savings, holidays and cashback credit cards.
I freely admit I’m a bit of a money saving geek, so I have a decent arsenal of tricks and tips which I doubt many actually use day-in, day-out like me. Even so, when this week’s family professed to be pretty good with their cash I was worried I might not be able to beat the £1k challenge.
But when I headed to Peterborough to meet Frankie and Scott, my first saving was already waiting for me at the front door (OK, a bit of TV trickery meant we had to put a pretend box out as we couldn’t show the branding!). Here’s how I did, and a little more about how you can take up some of the same savings.
Monthly recipe boxes
The family get a Gousto food box delivered to their door every month. These come with all the ingredients you need to make a series of meals. Convenient? Yes. Cheap? No.
I asked the Shop Smart Save Money team to crunch some numbers for me to work out just how much more expensive it was to get meals this way rather than pop to the supermarket.
If you go on the prices for those exact ingredients, do gram for gram the savings worked out as a huge £28.33 a box!
So it’s certainly cheaper to buy it all yourself. And since Frankie works at a Tesco, the convenience argument doesn’t really work!
Frankie is a smart shopper – she’s got more loyalty cards than I’ve ever seen and has two wallets to hold them all. But while delving through her purse I spotted an M&S credit card.These aren’t bad. You earn 0.2% back for every £1 you spend, but with a spend of £300 or £400 a month, means I think Frankie only earns £10 a year, more or less. She could do better.I recommended an American Express Platinum Cashback credit cardwhich gives 5% for the first three months (up to a maximum of £125) and then 1% after. I reckon that’d make them around £150 over the first year.
As Frankie pointed out, there is a £25 fee, but you can usually get this back if you apply via a cashback site.
Of course, with any credit card spending you need to clear the whole balance off of every month to avoid getting charged interest, which would make the cashback pointless.
Save £140
Savings
Frankie and Scott have got £4,000 in savings, but it’s earning nothing at all! Instead I suggested they open up a Nationwide FlexDirect current account each. I’ve got one of these and it offers 5% on £2,500 for the first year. The best interest you can get on cash savings right now.
Save £200
Holiday
When they go away, Frankie and Scott don’t do anything themselves when booking. They simply head to the local Thomas Cook and ask them to book something that meets their requirements and fits their budget.
So I asked them for a holiday brief. They wanted seven nights bed and breakfast for three in Turkey during the summer holidays. The hotel needed to be at least three stars and have a swimming pool. I had a look on the Thomas Cook website and found one that fitted the bill for £2,236.
The seemed quite happy with that, but I wanted to see if I could do better than a travel agent. I managed to get exactly the same holiday for just £1,906, simply by booking each stage individually. And I mean exactly the same holiday. It was exactly the same flights, exactly the same hotel (though with a bigger suite rather than three-bed family room) and some transfers. Then there was even 10% cashback on the hotel on top.
That’s not to say you can’t get package holiday bargains, and they can come with added consumer protection, but it pays to check the cost of the component parts. I’ll write more about this in a few weeks.
Save £330 + £66 extra from hotel cashback
Holiday cash
Frankie and Scott tend to get their cash where they get their holiday. And this costs them.
They normally spend around £1,000 so I looked up the price on the day of filming for Turkish Lira. You’d get 5,633 lira for this from Thomas Cook. But by comparing prices online I worked out the cheapest rate near them was with either Sainsbury’s or Asda.
They’d get 5,873 lira for £1,000, and that extra 240 lira was worth £41, which as Frankie said, that’s a whole meal out in Turkey.
Save £41
Free student railcard
Finally, I was asked to recommend a student bank account for their daughter who’s heading off to university in the autumn.
One of the best is with Santander as you get a four-year 18-25 Railcard. Though a one-year card costs £30, you can get a three-year one for £70, so £100 seems like a fair value.
Save £100
How did I do?
So I managed to beat the challenge once again. The total this week – if the family take all my suggested actions – is £1,217.
You can watch me on Shop Smart Save Money on Channel 5 every Wednesday in June at 8pm, and you can read about the other families I’mhelpingas part of the series.
Iceland has launched what it claims are the cheapest supermarket chicken breasts – and I’m not happy.
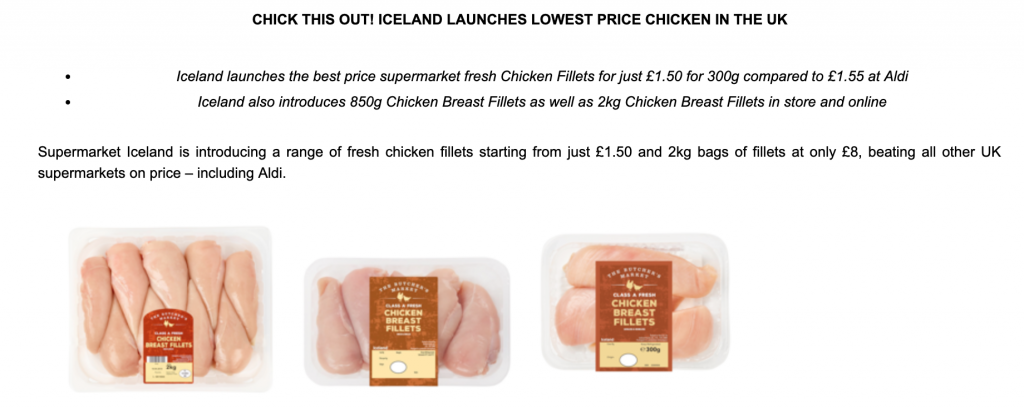
Late last week a press release popped into my inbox. The title read “Chick this out! Iceland launches lowest priced chicken in the UK”. You can see some of it in the image below.
So what’s the problem? Well, although I’m often celebrating saving money, I don’t think supermarkets should be shouting about the lowest price chicken.
Really cheap chicken can only mean one thing – poor welfare. And it could be a signifier that it’s lesser quality meat too, perhaps pumped full of water. Yes, ok it could be a subsidised loss leader to get people through the doors. But not to an extent that mitigates my concerns.
And according to the RSPCA, most people don’t want this either. Eight out of 10 people think the chicken they are buying is higher welfare – but it’s not.
Animal and bird welfare
To sell chicken at this price must surely mean these birds will be enduring horrific conditions. It’s not just the overly crowded pens with little or no natural light, which are both pretty horrendous.
The RSPCA has further concernsabout the consequences of intensive farming of the birds. Many are genetically selected for faster than natural growth which means the chickens can’t walk or stand, and even suffer heart attacks.
And intensively farmed birds aren’t likely to have been slaughtered to any sort of humane standard.
The scale of the problem
Chicken is the UK’s most popular meat, with one billion chickens reared each year. Yet, according to this infographic from the British Poultry Association, less than 4.5% of UK reared chicken is free-range or organic. That means there’s a huge amount of chicken that’s potentially raised in these shocking conditions.
Infographic by the British Poultry Association
What supermarkets should be doing
Rather than trying to find the cheapest chicken, I think Iceland – and the other supermarkets – should be trying to find a more sustainable way to give us ethical and affordable meat.
Instead most are actively making it harder for consumers to find and afford it. Labels can mislead people into thinking the chickens are living on an idyllic farm, or just that there are any kind of humane conditions. The RSPCA even found higher-welfare meat positioned away from shoppers’ eyelines and rarely in promotions.
And by offering even cheaper intensively farmed chicken, they are also making the price difference between it and free-range and organic chicken even wider.
What Iceland says
I was surprised to see this come from Iceland because they made such a strong stance on palm oil and deforestation at Christmas with their banned Greenpeace advert, which focussed on saving a sad cartoon orangutan. Are they saying they only care about animals they don’t sell in a party platter?
It’s unfair to single them out though – I’ve just picked out Iceland for actively trying to promote the cheapest chicken. The majority of chicken you buy in a supermarket isn’t going to have been raised in the conditions you imagine.
I wanted to let Iceland respond to this. Here’s what they said about the welfare conditions of their chicken.
“We offer a range of poultry products across our chilled and frozen ranges, with tiered price points to appeal to all of our customers. We work closely with our suppliers and have reduced the level of margin on our lowest priced chicken in order to offer these lines at such low prices.
We are committed to offering our customers choice, and alongside our ‘lowest priced chicken in the UK’ we offer slightly higher tier products which are Red Tractor Assured, for example. All of our suppliers must adhere to our strict animal welfare policies and we work with them to ensure high standards based on the ‘Five Freedoms’ endorsed by the Farm Animal Welfare Council.”
Personally, this doesn’t make me any more confident about the standards used to farm the chickens, and I wouldn’t buy any chicken from Iceland. But the same goes for any other low-welfare chicken at most supermarkets.
So what can you do?
How to be ethical and pay less for your chicken and other meat
For most of us, we can’t afford to live a life that’s 100% ethical. You need to pick your battles – and I think better conditions for chicken is one which can be fought. Here are just some of the ways you can eat higher-welfare poultry and other meat without breaking the bank.
Look for RSPCA Assured, free-range or organic chicken
The only labels you can trust are RSPCA Assured and Soil Association Organic. These are certifications which require the farms to adhere to certain standards. And though free-range isn’t certified, it will be fine too.
Don’t be fooled by Red Tractor logos – something Iceland and others offer on some poultry. These are the minimum legal animal welfare and food safety standards – which in reality doesn’t mean much if you are concerned about the life an animal led. Jamie Oliver has said he wouldn’t feed his kids anything labelled Red Tractor.
Only buy your chicken from certain supermarkets
If free-range or organic prove too expensive – and they can be – then you should buy your meat from supermarkets which have their own higher welfare policy. Though they won’t be at the same level as RSPCA Assured, they won’t be far off.
You can bring down the cost of your chicken if you switch breasts for thighs, which are generally cheaper and tend to have more flavour and moisture than chicken breasts. Skin-on will cost less, you just need to remove it.
Use the whole bird
If you’re buying a whole chicken, don’t waste any of it. Get into the carcass and pick out all the bits to make sure your money and meat go further. You can even go one further and use the carcass to make chicken stock for use in soups and gravy.
Raid the reduced shelves
I do all the above, but my biggest savings are down to picking up some reduced to clear bargains. I’ll separate the packs into portions and then put them in my freezer. This makes shopping more affordable at supermarkets such as Waitrose or M&S where I know the standards are higher even if I’m not able to find free-range or organic.
Eat less of it
A few generations ago a chicken was a treat. Now it’s a daily meal in some households. Realistically the price of ethical chicken means most of us will have to eat less of it. But that’s no bad thing either – there’s a whole other article that could be written about farming and its impact on the environment, particularly cattle.
It’s not actually that much more money a year to upgrade to an ethical banana.
This is the first in an occasional series where I’ll break down just how much you’d need to spend in order to go green.
Each year in the UK we buy 5 billion bananas. That’s 100 per person, so roughly two a week each.
Of that around a third are Fairtrade certified, meaning the farmers and other workers are getting paid a fair price for each banana, but also receive rights as workers and money to invest in their communities.
If you’re buying your bananas in Waitrose, Sainsbury’s or Co-op then you’re buying Fairtrade every time – whether loose or in a bag. But the other supermarkets tend to only offer Fairtrade in packaged bunches.
These bundled ones tend to be more expensive per banana than the loose alternative, and of course there’s also the wasteful plastic bag, which I know lots of people try to avoid on fresh fruit and veg (it really isn’t needed).
And it’s both those reasons which can put people off buying these more ethical bananas. But should they?
How much more do Fairtrade bananas cost you?
Before MySupermarket shut down this weekend, I took a look at the prices for loose and packaged bananas, Fairtrade and non-fairtrade, at the major supermarkets.
Loose Fairtrade vs non-Fairtrade bananas
First loose bananas. The price you see is in pence per banana. Morrisons and Ocado don’t sell loose bananas on their websites while Co-op and Aldi don’t do online shopping, so these retailers aren’t in this table.
Now, the price given online is the price per KG rather than banana. So I weighed the five bananas I had at home and have gone with 170g as an average weight of a banana bought loose. Of course it could be higher or lower, but this gives us something to work with.
Waitrose
Tesco
Asda
Sainsbury’s
Lidl
Loose 170g banana
14.28p
14.161p
13.94p
Loose 170g Fairtrade banana
14.96p
14.45p
(Scroll right on your phone to see the full table)
Straight away you can see there’s not much difference between the supermarkets. Yes the Fairtrade ones at Waitrose and Sainsbury’s are a fraction more expensive, but not by much.
The smallest difference is between Tesco at 14.28p and Sainsbury’s at 14.45p. That’s a difference of just 0.17p. Nothing. Even over the average 100 bananas a year it’s 17p difference. Seventeen pence. A year.
And even the biggest difference, between standard non-Fairtrade bananas at Lidl and Fairtrade bananas at Waitrose is just 0.96p – less than a penny per banana. Over a year, you’d just be paying an extra 96p, not even a quid.
So if you can swap your banana shop to Waitrose or Sainsbury’s (or Co-op) then you’ll be making a huge difference to the farmers without even noticing an impact on your wallet.
Packaged Fairtrade vs loose non-Fairtrade bananas
Of course, you might not have the option to shop at one of these supermarkets. So if you want to go Fairtrade you’ll have to buy them in those five or six banana bundles in a plastic bag.
For a moment, ignore the environmental concerns about the plastic bag. Let’s focus on the price of the bananas.
The table below covers the main options from the supermarkets. I’ve ignored “ripen at home” and so on. The price is once more per banana, rather than per pack.
Tesco
Asda
Morrisons
Lidl
Ocado
Loose 170g banana
14.28p
14.161p
13.94p
Non-Fairtrade bunch
20p
18p
20p
17.8p
Fairtrade bunch
19.8p
Fairtrade organic bunch
27p
20p
26p
19.2p
26.7p
(Scroll right on your phone to see the full table)
The first thing you probably notice is that packaged bananas cost more than loose ones! You’re be paying between 17.8p and 20p for a non-Fairtrade banana this way.
Next you’ll probably spot Tesco, Asda, Morrisons and Lidl don’t sell just Fairtrade. They only sell Fairtrade and Organic. This allows them to charge them at a higher price – and therefore make the price difference much larger.
I think that’s really cheeky and it’s got to put people off. At Tesco a loose non-Fairtrade banana will cost 14.28p on average, but 27p from a Fairtrade Organic package.
For comparison, the Fairtrade only packaged bundles from Waitrose, Sainsbury’s and Ocado come in at 20p per banana. The same price Tesco and Morrisons sell non-Fairtrade bunches. So it is possible to sell bunched Fairtrade at a lower price.
However, the 12.72p difference at Tesco between it’s loose and packaged Fairtrade Organic bananas works out as £12.72 for 100 bananas. That’s still not a huge amount of money.
So if you really can’t buy your Fairtrade bananas loose, then it’s not going to cost you the earth to buy the premium bundles from your usual supermarket.
Bananas and plastic wrapping
Sadly doing the latter doesn’t help with any desire you’ve got to buy less food that has plastic wrapping.
Personally I’d go for Fairtrade bananas every time, and making it known to your supermarket that you want less plastic in general, not just on bananas. And while you’re at it say you want lose bananas to be Fairtrade too.
Bananas and food waste
Wherever we buy our bananas from, one thing we can all do is cut down on the amount we throw away because they’re a bit brown or mushy.
This works out as 10 bananas each a year. If you’re in a household of four or so, assuming an average banana price of around 20p, that’s £8 of wasted bananas you’re chucking out.
Ok, so not a huge amount. But alongside the other edible things you’re likely binning at the same time it can all add up.
What to do with those bashed bananas
Personally I’m happy to put an overripe banana in some porridge, but I know some people still won’t be keen.
Even then you don’t have to bin them as there are plenty of ways to use them. For a start you could look at freezing them (peel and chop them up first) and using in smoothies, or even better use them in baking.
Recipe: Low-fat bashed Fairtrade banana and berry cake
My wife Becky is an amazing baker and often whips up a banana cake. She’s got a few different recipes, but this is her favourite. It’s really easy and low fat.
Who you use to fundraise and donate money with can affect how much money the charity gets – so it pays to use Just Giving alternatives.
When you donate on one of the big fundraising websites, you’d think all your money is going to the cause you’re supporting. Well, it doesn’t. I was pretty shocked when I discovered this a few years ago.
There can be fees added to or taken from the money you give, and the charities themselves could be faced with charges just for being listed on the platform.
Among the worst is the most popular – Just Giving. This is the only one of the major platforms that isn’t non-profit. Alongside these costs to the charities, it until recently also added a compulsory transaction fee for customers too. It’s now made that an optional charge, but paying it still means less of your money goes to the charity.
But some are much more affordable platforms that are Just Giving alternatives. And as with most things, a little shopping around can maximise how much of your cash actually goes to the good cause.
As you’ll see further down the article I’ve broken down how much money gets taken by the platforms. The cheapest gives 44p more to causes than Just Giving per £20 donated.
Though it might not seem a huge amount based on a £20 donation, it scales up massively over all the money that is raised.
For example, Captain Tom Moore had raised an unbelievable £32.8 million for NHS causes before it was closed on the 30th April. This was via Just Giving, and the fees and voluntary “tips” could easily be over £2 million.
If he’d chosen Virgin Money Giving then the total would have been half that (figures calculated via Virgin Money Giving’s calculator). And potentially even less with a different platform.
It just shows that the platform you choose for fundraising or donating can make a huge difference.
(FYI Just Giving has said 97% of the money raised by Captain Tom will go to the NHS after processing fees, though I assume that doesn’t include any extras people volunteer to pay to cover the fees. Plus it’s made its own £100,000 donation on top)
Where your money goes when you donate
You’ll be relieved that most of your donation does go to the charity – but not all.
Payment fees
For a start, there are card transaction fees that all the charities have to pay. They don’t have a choice about this as it’s a cost levied by the card processing companies. In fact, any time we use our debit or credit cards these are part of what we pay, whether charity or not.
Just Giving will also take a cut of any Gift Aid added to your donation too, as part of the processing fee.
However, Just Giving alternatives all charge different fees, which can make a difference.
Wonderful, one of the best free platforms, has had to close (hopefully temporarily) but shared that it paid just 0.8% plus 18p for each transaction. So anything higher than this is possibly hiding additional charges.
Tip jar warning: The cost we had to meet for payment processing was 0.8% and 18p per transaction. We handled £5m in donations. If your platform processes more than £5m and you’re being asked to contribute more than 0.8% and 18p, do ask what they class as card-processing fees.
— wonderful.org (@wonderful_org) March 20, 2020 via X
Platform fees
Of course, these donation websites have all got to cover the costs of staff and operations. And, yes, this money does have to come from somewhere.
And it’s not cheap to do this. BT used to offer My Donate, a free service to charities, and fund it from its profits. But this project was closed down in 2019.
So some of the websites will add this as an extra charge on your donation, possibly voluntary, or just take it from the money you give.
Charity listing fees
And that’s not the only way these companies take cash away from charities – the biggest platforms Just Giving and Virgin Money Giving both charge charities to use their platforms.
Just Giving charges a monthly fee of £39 + VAT for any charity that raises £15,000 or more in a year. For those which raise less the fee drops to £15 + VAT a month.
Virgin Money Giving meanwhile has a flat, one-off fee of £150 + VAT.
Our podcast
Listen to Cash Chats, our award-winning podcast, presented by Steve Alderton and Editor James Andrews.
The alternatives to Just Giving and Virgin Money Giving
If like me, you want as much of your money to go to charity as possible, and for the charity to be able to use the platform without a charge, it makes sense to avoid the profit-making Just Giving.
It’s less clear-cut with Virgin Money Giving as though it is non-profit, the fees still make it quite expensive for smaller charities.
Fortunately, there are alternatives. Some don’t charge for anything, while a few others might have a transaction fee, but are free for the charity.
The major downside with most of these smaller platforms is just that – they are smaller. They won’t necessarily have your charity of choice on board, though it’s worth looking to see what your options are. Often it’s the smaller and local charities which need our support more than some of the giants – and they might be on the smaller platform.
If you’re fundraising, then talk to the charity, or check out its website at least, to see if they have a preferred platform.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer
Ways to maximise your donation
As well as choosing the cheapest platform for charities, you can boost the amount they get from your donation by making sure they can claim the tax back from the government.
If you donate via your paycheck – often called Payroll Giving – the taxman actually contributes some of the money. So a Basic rate taxpayer would only contribute 80p for the charity to get £1.
This is automatic and in theory an easy way for the charity to get the extra tax cash on top of your donation. Ask your HR team if they run a scheme. If they don’t seem if they will set one up.
So Payroll Giving works great for regular donations, but it won’t work for a one-off contribution. In that case, and if you are a tax-payer, you can choose to add Gift Aid to your donations, adding 25%.
You’ll see this option when you donate online. However with Gift Aid the charity has to claim this tax back. This can come with administration costs to the charity.
Both methods will mean the same amount of money goes to the charity.
Bonus requirementsTo get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
Regular saver8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
Existing customers?You can't have held a Santander account on 1 January 2026.
Here’s the real cost of a £20 donation to Just Giving, Virgin Money Giving and some of the other donation platforms. Some of the platforms will give you the choice to pay this. I’ve included the extra value of Gift Aid on top too.
These figures assume you aren’t choosing to add the fees to your initial donation. They also don’t reflect Just Giving’s monthly fee or Virgin’s set-up fee which are worth bearing in mind.
Kindlink
Kindlink has no charges for the charities to use the platform or be listed, making it one of the cheaper options.
Payment processing fee of 1.45% + 10p = 39p
Platform fee of 0% = 0p
Gift Aid fee of 0%= 0p
Total cost per £20 = 39p
Total to charity after Gift Aid = £24.61
GoFundMe
With GoFundMe you’ll be charged a similar amount to Virgin Money Giving but there’s no charge for charities to be listed.
Payment processing fee of 2.9% + 0.25p = 39p
Platform fee of 0% = 0p
Gift Aid fee of 0%= 0p
Total cost per £20 = 83p
Total to charity after Gift Aid = £24.17
Just Giving
The monthly fee that charities are charged won’t make much difference to this figure if they’re taking a lot of donations. However medium-sized charities could fee the impact more.
Payment processing fee of 1.9% + 20p = 58p
Platform fee of 0% = 0p
Gift Aid fee of 5% = 25p
Total cost per £20 = 83p
Total to charity after Gift Aid = £24.17
Virgin Money Giving
Since Virgin Money Giving has a sign-up fee the actual amount will be a little less. Though for large charities the £150 one-off fee will be negligible.
Payment processing fee of 2.5% = 50p
Platform fee of 2% = 40p
Gift Aid fee of 0% = 0p
Total cost per £20 = 90p
Total to charity after Gift Aid = £24.10
During the lockdown the platform fee will be covered by Virgin Money but it’ll return afterwards. The figures above include the platform fee.
Every Click
Another free site for charities to join, Every Click is funded from the commission paid by retailers if shoppers use the portal before making online purchases (in the same way cashback and voucher code sites work).
Payment processing fee of 4.8% = 96p
Platform fee of 0% = 0p
Gift Aid fee of 0%= 0p
Total cost per £20 = 83p
Total to charity after Gift Aid = £24.04
Givey
Givey is targeted at small and medium charities. It charges the donor 5%, so £1 for a £20 donation. But again the platform is free for charities to use. Further funding comes from businesses who can choose to match donations.
From tax avoidance to surprisingly high prices, it could pay to shop less at Amazon. Plus some alternative online retailers you could use instead.
Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.
Paid advertisement
Over the last year, I’ve been making a conscious effort to use Amazon less. In all honesty, it’s not been the easiest thing for me to do.
I’m hardwired to hunt down the lowest prices wherever they might be. And often there are some huge discounts and deal stacks at Amazon that make items super cheap.
So I’ve lapsed on a few occasions. Sometimes I’ve forgotten about my boycott and clicked without thinking – a deal for super cheap peanut butter is one I regret! It might have been 50% off the RRP, but in total it was barely a fiver saved.
And there have been a handful of times where the discount was just too tempting – last month I saved £160 on an iPhone 12 Pro (a misprice) and £85 on a Canon lens (a daily deal).
At other times the next day delivery has been a clincher – I realised I needed a case and screen protector for that new phone the day the phone arrived. There was also a gift where it was only in stock on Amazon.
I’m also a Kindle user, meaning any digital e-books I want have to come from Amazon – though I tend to only pick up 99p special offers.
But, despite these purchases, there are dozens and dozens of other items I could have got from Amazon this year where I’ve deliberately chosen to go elsewhere.
I’m willing to spend extra to buy from a different retailer, whether that’s through a higher price or factoring in delivery charges. And in many instances, the difference was minimal or non-existent.
Why am I doing this? There are a few reasons which I’ll outline below. You’ll be familiar with some of them already – but I think a few might surprise you.
Of course, I’m aware you might not care about some of the more ethical points.
You might also not have the luxury of being able to afford to care. Though I can stump up the cash to buy a book at full price, many can’t. So getting the lowest price could be more important to you.
Though personally I’ve been able to get out of the house during the pandemic and visit stores (once they reopened), I know having Amazon Prime was a lifeline for many.
And there will still sometimes be those promotions or discounts that are just so huge it’s hard to say no.
A big mistake people make with Amazon, especially if they have Prime, is to assume it’s always the cheapest. Though it can offer big savings, it can also be ridiculously expensive.
Sometimes this is just sellers putting higher prices on Amazon than elsewhere, other times it’s something called drop shipping. This is where a seller lists an item for sale at a set price. When you buy it they then order it from another retailer and get it set to you! Either way, you pay more than you need to.
Yes you might have to pay postage at Lakeland, but you only get it free with Amazon if you have Prime. Or you might also be able to just pop into a store and get it for more than half the Amazon price.
Ikea lint rollers
Head to Ikea and a refill pack of four Bastis will set you back £2.25. But over on Amazon you’ll pay £6.99.
If you don’t fancy braving the Ikea maze and decide to pay Ikea’s £4 delivery fee, you’ll pay more via Amazon – even if you have the Prime free delivery.
Stamps
A few years back I found out that some shops can charge what they like for stamps. And one place where you’ll get ripped off for for first and second class postage is Amazon.
A pack of 12 1st class would cost you £9.12 from the Post Office or supermarket. This seller has put them on Amazon for £10.49.
You’d pay £7.80 for 2nd class. But I found them on Amazon for £11.47! That’s more than the already overpriced 1st Class stamps there!
Our podcast
Listen to Cash Chats, our award-winning podcast, presented by Steve Alderton and Editor James Andrews.
Amazon Prime is very, very popular. For £79 a year you get free next-day delivery, access to special deals and sales, TV & film streaming and more.
Yes some of these can save you cash, but really the whole point behind Amazon Prime is to get you to make Amazon your number one destination. If you’ve already paid for free shipping, why would you pay again elsewhere?
it’s not just Prime. I mentioned in my introduction that I’ve got a Kindle. If I want to read books on it, I have to buy them from Amazon. Again I’m locked in. I also made the decision early on to go with Echo smart speakers. If I want more of these, or other smart devices, it can often make sense to stick with Amazon.
This essentially reduces your choice and ability to shop around – and therefore get the best price.
Prime makes you more likely to spend money
If you have Prime you’re also more likely to not just shop solely with Amazon, but spend money you hadn’t planned on parting with.
Free and fast shipping is once again the big driver here. It’s so, so easy to buy things this way that it can be addictive. Click. Click. Click.
And those special offers such as Prime Day can encourage you to buy things because of your “exclusive” discounts. If you don’t have Prime, you’re far less likely to spend that cash.
So reduce your time on Amazon and you’ll likely spend a lot less money.
Amazon hurts the high street
Amazon isn’t the only retailer accelerating the decline of the high street, but it is the biggest. During the summer it recorded a sales increase of 37%, thriving during the pandemic while others edge closer to collapse.
Every month more retailers, large and small, announce store closures and profit warnings. They struggle in normal times to compete with the scale and low overheads of Amazon.
If we want our town centres and shopping centres to survive we need to spend more of our money with them – and that probably means at the expense of Amazon.
Amazon is not an ethical company
Finally, the biggest reason to not use Amazon – and the other main motivation behind my reduction in spend.
From the treatment of workers through to tax avoidance, they have a bad rep. A really bad rep. Though others will be doing the same things and some will be worse, I don’t feel we can pretend that Amazon’s abuses of the law and trust justify low prices.
Bonus requirementsTo get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
Regular saver8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
Existing customers?You can't have held a Santander account on 1 January 2026.
Whether you want to completely cut out Amazon or just reduce how often you use it, I’ve got a few suggestions to help.
Pay for Prime only when you really need it
One way to use Amazon less is to ditch Prime. That way you won’t be tempted to get the value of your membership by using it to shop more and more.
If that’s a step too far, you have options to keep it but pay less. You don’t have to sign up for the full year of Prime. Rather than shell out £79 for 12 months you can pay £7.99 a month.
Obviously that’s more expensive over 12 months, but if you pick and choose particular months – eg ahead of Christmas or around Prime Day – you’ll pay far less.
You can also opt for a £5.99 monthly fee that is just for Prime Video. You can change your subscription in your account.
Support the retailers you love
We’ve seen so many shops disappear over recent years, I’m trying more and more to buy from the ones I’d really miss if they were to do. From small local merchants through to the likes of John Lewis and M&S.
It’s worth seeing if small shops have their own online shop or listing on social media. Or even just call them up. Many are offering click & collect services during restrictions.
For books, one new site worth checking out Bookshop.org which provides a platform for hundreds of independent book shops to earn profit from online sales.
Go to the Amazon sellers direct
You can obviously shop around to find low prices elsewhere, and price comparison sites can help with that. But there’s a trick that could get you the same or similar price to the one you find on Amazon.
When you buy something at Amazon that’s not sold by Amazon, you’ll see the name of another retailer. It’s always worth looking to see if they have their own online or high street shop.
Get the best of our money saving content every week, straight to your inbox, and exclusive £18 TopCashback bonus.
Join more than 100,000 other subscribers to get our weekly newsletter.
Get the best of our money saving content every week, straight to your inbox
Plus, new TopCashback customers get a high paying £18 welcome offer