The top reward current accounts

How to earn rewards & freebies from your bank

There are a number of reasons to change your bank, with switching bonuses and exclusive savings rates often a big draw. However, the easiest ones are often ‘reward’ accounts as they usually require very little effort to make something extra every month – and you don’t even need to switch to get them.

From free cinema tickets or weekly Greggs, to points and cashback paid to your account each month, they’re certainly better than the accounts we’re all used to which give nothing in return.

But they aren’t without some drawbacks, including fees and requirements that you set up direct debits or deposit money each month.

So whether you’re just after one account or are happy to game the system for a handful, here’s how they work and my picks of the ones to go for.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

What is a reward bank account?

What you get with these accounts varies. Some accounts offer cash or points, others offer freebies.

These benefits usually aren’t actually free! Most of the accounts charge a monthly fee. Some you can avoid by paying in a certain amount of money each month. Others you’ll need to take into account when working out how much you’ll make.

Though some will pay the reward into your account, others (NatWest or RBS) put the money in a separate rewards wallet which you have to manually withdraw. It’s a bit pointless really.

And if you’re claiming a non-cash reward then you will have to select it.

Qualifying for reward accounts

Some reward account require you to take an action to qualify. Here are the typical ones. You’re unlikely to be required to do all of them, probably just one or two.

Set up direct debits

Often banks require one or two direct debits, sometimes with a minimum value. Though ‘active’ usually means the money has to have been paid in the last year, the banks that use this only pay you the months a direct debit is paid.

It’s not such a huge issue as if you pay bills you’ve all got direct debits you could use – though they are best suited to a cashback current account.

If you are short of direct debits, new ones can easily be set up for other things too, such as credit card bills, memberships, subscriptions and charity donations. Here’s our guide to where to find additional and cheap direct debits.

Paid advertisement

Pay money in each month

Reward accounts often require a minimum deposit each month. This is to encourage you to pay your salary there. You can do that easily if you want – just tell your HR department of the new details.

But you usually don’t have to. It’s easy to transfer money in from a different current account via a standing order. You can do this as one lump sum or break it into smaller amounts over the month if that’s better for you.

And it doesn’t have to stay there either. You can transfer it back out straight away.

Spend on your debit card

A couple of accounts require you to spend on the debit card too. You can do this as part of your regular spending but it does mean you’ll miss out on cashback from a different card. Once again there are ways to get around this, as explained in this Halifax Reward hack article.

Use your internet banking or the app

You might also need to log in to your banking app or online account once a month to qualify for the reward. It’s worth setting a reminder in your calendar to do this if it’s not an account you’re using regularly.

Paid advertisement

My top reward bank accounts

Here’s my pick on the different reward accounts.

Monzo Perks account

  • What you get: an annual railcard, Uber One membership, one free Vue ticket a month, a free Greggs treat each week
  • Monthly fee: £7 (£84 a year)
  • What it’s really worth each year after the fee: around £115
  • Requirements: None
  • Maximum number of accounts: one

If you need a railcard (worth £35), go to a Vue each month (let’s say 12 times £6, so £72) and pick up a £2 Greggs treat twice a month (£52 a year) and pay for Uber One (£40 a year), you’d be well in profit versus the £7 monthly fee. Of course, that’s only good if you actually need those things!

You’ll also get access to extra budgeting features that aren’t on the standard Monzo account.

We’ve written up a full review of the Monzo Perks account so you can decide if it’s for you or not.

Club Lloyds account

  • What you get: six free cinema tickets (Vue or Odeon), a year of Disney+ with Ads, a magazine subscription OR a dining membership
  • Exclusive savings: 6.25% regular saver
  • Monthly fee: £3, though refunded if you pay in £2,000 a month
  • What it’s really worth each year: between £40 (magazine subscription) to £60 (equivalent value of six £10 cinema tickets)
  • Requirements: none
  • Maximum number of accounts: one individual and one joint

The Club Lloyd account is one of the easiest one to get. There’s no reason why you can’t just open this up (ideally via a switching bonus), set up a standing order to pay the £2,000 in (and out) each month, and keep claiming your reward.

You can have one personal and one joint account and claim the rewards on both, so that’s potentially three between a couple.

Here’s my full review of the account, where I break down which freebie “Lifestyle Benefit” I feel gives the best value.
Paid advertisement

Santander Edge

  • What you get: 1% cashback on bills
  • Exclusive savings: 6% savings account for one year
  • Monthly fee: £3
  • What it’s really worth each year: Roughly £25-£30 in cashback (based on low/medium bills) and £228 in interest (based on full £4000 balance saved)
  • Requirements: £500 monthly deposit and two direct debits
  • Maximum number of accounts: one individual and one joint

This isn’t a big earner on the cashback alone, but if you are paying the qualifying bills, it makes sense to sign up, especially as there’s regularly a decent switching deal on top. Here’s our full Satander Edge current account review.

I’m also a fan of the exclusive linked Edge Saver account that pays 6% for a year on up to £4,000 – you won’t get better rates on a small lump sum elsewhere. After a year you’ll want to close the Edge Saver and open a new one to keep getting a top rate.

You’ll also be able to open an 8% paying regular saver, though that’s available to all Santander current account holders.

If you need travel insurance and breakdown cover you might want to upgrade to the £17 a month Edge Explorer.

PayPal+

  • What you get: 1% or more cashback on spending
  • Monthly fee: £0
  • What it’s really worth each year: Spend £25,000 a year and you’ll get £300 to £375 back, plus around £300 to £330 via other offers
  • Requirements: None
  • Maximum number of accounts: one per person

Ok, so PayPal + isn’t a current account. But it is a debit card stacked with rewards, and my top pick for your spending. It provides 1 point for every £1 you spend with the card, and there are occasional offers to earn more (e.g. I got 10 points per £1 with a recent Eurostar spend).

You’ll start on the ‘blue’ tier, lets you swap one point for 1p, so it’s effectively a 1% cashback card. But if you earn 25,000 points (so spend roughly £25,000) in a calendar year you move up to ‘gold’ tier. Then the points are worth 1.2p when spent, or 1.5p if used on groceries, eating out and takeaways.

Then on top of this you can earn 1,000 points (worth £12 to £15) with a £10 spend on the first Friday of each month and £12.50 cashback a month on subscriptions.

All in, that could be £675 to £705 in your pocket over a year.

One quick warning, you’ll need to reach the new levels by 31 December each year – status won’t carry over (though the points won’t disappear).

Really big spenders (£50,000 a year), move on to a ‘black’ tier with even more extras. Here’s our full PayPal Plus review.

Other reward accounts

For completion, here are the other main reward current accounts. It might be worth looking at these if you already bank with them, or if there’s a switching offer on top.

Chase Bank

  • What you get: 2% cashback on certain purchases
  • Exclusive savings: 4.5% easy access for the first year
  • Monthly fee: None
  • What it’s really worth: Up to £20 cashback a month / £240 a year
  • Requirements: None
  • Maximum number of accounts: one

Other debit cards now beat Chase for cashback, despite it’s higher headline rate. That’s because it’s limited to groceries, restaurants, fuel and other everyday transport.

It’s a good easy access savings account for the first year.

Here’s our Chase Bank review.

Zopa Biscuit

  • What you get: 2% cashback on Direct Debits, 2% interest on bank balance
  • Exclusive savings: 7.1% six-month regular saver
  • Monthly fee: None
  • What it’s really worth each year after the fee: Up to £30 cashback
  • Requirements: None
  • Maximum number of accounts: one

The offering sounds good, but in practice it’s not much of a game changer. However it is free, and if you have spare direct debits that’s £30 extra each year you can gain relatively easily.

I’d look elsewhere for regular savers. Here’s our Zopa Biscuit review.

NatWest or RBS Reward account

  • What you get: £5 a month reward
  • Exclusive savings: 5.25% Digital Regular Saver (available to all current account holders)
  • Monthly fee: £2
  • What it’s really worth each after the fee: £36 plus interest
  • Requirements: two direct debits of at least £2 each and log into your account once a month, deposit £1,250 a month
  • Maximum number of accounts: one personal and one joint from NatWest and one personal and one joint from RBS

This account used to be a favourite of mine, but since its revamp a few years ago it’s not really worth it unless you have direct debits to spare or open it up when a switching offer is running.

The Rewards account is one where you have to log in to a separate ‘MyRewards’ account to claim your bonus. You can send it as cash to your account, donate it to charity, or top it up as an e-gift card payment.

Here’s more on how the account works. It’s the same for the Reward account offered by RBS.

Barclays Blue Rewards

  • What you get: free Apple TV+
  • Exclusive savings: 3.96% Rainy Day Saver on up to £5,000
  • Monthly fee: £5 (£60 a year)
  • What it’s really worth each year after the fee: £57.88
  • Requirements: pay in £800 each month
  • Maximum number of accounts: one

This one is no longer worth it in my opinion, though if you are committed to paying for Apple TV+ every month (which costs £8.99) then this will save you close to £58 over the year. However I think most people are better off just paying full price for Apple one or two months a year and binging the content.

If you decide you want to do that, then you’ll also get access to an easily beaten 3.96% paying savings account on balances worth up to £5,000.

Here’s our Barclays Blue Rewards review.
Paid advertisement

TSB Spend and Save Account

  • What you get: £5 cashback for the first six months
  • Exclusive savings: 6 Monthly Saver (available to all current account holders)
  • Monthly fee: £0
  • What you’ll really get each year: £30
  • Requirements: make 20 payments a month
  • Maximum number of accounts: at least one personal and one joint

TSB Spend and Save Plus Account

  • What you get: £5 cashback
  • Monthly fee: £3
  • What you’ll really get each year after the fee: £24
  • Requirements: make 20 payments a month
  • Maximum number of accounts: at least one personal and one joint

I’m not a fan of these accounts either as you’ve got to make 20 debit card payments each month to get a fiver. And the reward only lasts for the first six months. Once for completists only. You can however get an extra £30 cashback from Quidco for switching.

Like the free TSB Spend and Save account you’ll earn £5 a month, but you won’t be limited to the first six months. After the £3 monthly fee you’ll make £24 a year. However, you still have to make 3-20 card payments which I think is a stretch when there are better paying cashback cards out there.

Should you get a reward current account?

I’m a big fan of the PayPal+ rewards. Though you’ll need to use it alongside another current account, it’s winner for anyone able to spend £25,000 a year, which is an average of £2,084 a month or £481 a week.

For those that need a railcard, Uber One and regularly go to a Vue and Greggs, the £7 Monzo Perks fee is well worth it.

Then, if you’re comfortable with multiple current accounts then I’d definitely look at getting the Lloyds and Santander ones too.

After this I’d only bother with the NatWest and RBS accounts if I already had one, or get one via a switching bonus.

Even I can’t be bothered with the TSB rewards due to the faff, while the fee for Barclays just doesn’t add up for most.

Having multiple reward accounts

As I’ve said many times, there’s no reason why you only have to have one current account – and that means you can have multiple reward accounts too.

You’ll usually only be allowed one personal reward account with each bank, though it does vary, and most let you can have an extra one as a joint account too. That means you could potentially have three accounts in a household, and three times the rewards.

But the more you have, the more you have to do to be eligible. Some are easy to overcome, others might make it less worthwhile.

Recirculating your inbound payments

Most people should be able to cover the minimum deposit payments for one reward current account. And if you have more than one then it’s easy to repeat for the others by moving the same money between each account.

I actually do this via a standing order where the money automatically goes from bank to bank to hit the eligibility threshold, with it eventually coming full circle back to my original account.

Covering the fees

This is a bit of faff, but manageable. Since some of the accounts charge a fee but don’t pay the reward directly into your account, you’ll have to make sure there’s enough in there each month to cover this charge. You’ll also need to remember to transfer the reward over each month too.

Running out of direct debits

If you have multiple reward accounts then you might quickly run out of direct debits. It used to be you could set up a couple of £1 ones for charities, but the banks have cottoned on to this and made it pretty pointless.

For example, NatWest give you £2 back for each direct debit, but the DD needs to be at least £2. So if you’re setting up a new payment just to get the reward, you won’t actually be any better off.

Of course you could see it as free cash for charity – which is great – but it does require a bit of effort.

How to get the best value sun cream

Save money without sacrificing the protection you give your skin.

Is a branded suncreen any better than a supermarket’s own version? And what should you be thinking about other than the SPF number?

I’ve taken a look at how to make sure you’re not overspending but still getting the right protection.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

What makes a decent sun cream?

SPF and UVB rays

When you’re going to buy suncream there’s probably only one number you really pay attention to. The big one on the front – the SPF number. Sun Protection Factor.

This ranges from around four or five all the way through to fifty plus. The number which medical groups recommend is at least thirty.

What the SPF number specifically shows is the protection you get against Ultraviolet B rays – or UVB. These are the rays that generally will burn your skin.

Basically the higher the number is, the greater the protection, the longer the protection you’re going to get from these rays.

“Star ratings” and UVA rays

There’s actually more than one type of UV ray coming from the sun. What you should also be looking for when you’re buying your suncream is protection against UVA – Ultraviolet A – rays.

This is the stuff that’s meant to premature age you, the stuff that causes you to get those lines caused by the sun. It will hopefully say both UVA and UVB on the packet.

But how do you know how good that protection is? Because SPF isn’t anything to do with the UVA. Instead, you look for some stars. Bigger packs hopefully have it on the front, though it might be on the back of smaller ones.

You should be looking for at least four stars. That’s going to give you the protection that you need.

Paid advertisement

Is more expensive suncream better?

Now if you’ve got at least factor 30 on the UVB and then you’ve got at least four stars on the UVA then all the sun creams are pretty much the same. At least they’re doing the same thing anyway in terms of protecting you from the sun’s rays.

So whether you’re going into Aldi or Boots and you’re spending a couple of quid or whether you’re spending more than ten quid by getting some posh brands, they’re not really doing anything different.

I had a look at Which? magazine. Last year they reviewed and tested about 15 to 20 different sun creams.

The best buys were from Boots, Nivea, Sainsbury’s and Superdrug, all relatively affordable. Worryingly, some of the brands didn’t offer the protection promised – and were marked “don’t buy”. These were Asda, Morrisons and one type of Ultrasun.

Broadly, the only real difference they found between the ones that did pass the tests is that some of the cheaper ones can feel a bit greasy when you apply them to your skin. Or they smell not fantastic when you apply them, so you might want to try some different ones and pay a bit more money.

So just because it’s a brand it’s not necessarily any better than an own brand from one of the chemists or supermarkets.

Paid advertisement

How much should you buy?

One extra thing to think about when you’re buying your sun cream is the size of the bottle. In terms of getting value for money the bigger bottles will often work out cheaper per unit, usually per ml, So you’d think the bigger the bottle the better the deal.

But that’s not necessarily the case. On the back of most of your sun creams, you’ll see a little drawing of a pot. You see it on lots of cosmetics as well. This little round pot with an open lid and in there it will give a little number. If it says “12m” it stands for twelve months. Most sun creams are meant to last between 12 and 18 months. 

Time actually reduces how strong the cream is. The bottle might say thirty on the front but if it’s two or three years old it won’t be delivering that kind of protection.

And it’s worth bearing in mind that if you leave your suncream out in the sun then that’s going to make it last a shorter amount of time as well.

So will you actually use the cream up in that time? Or will you, like I have in the past, have half-used bottles sitting at the back of the cupboard until the next year?

Big families, or people spending a lot of time in the sun, are probably better off buying big bottles at the start of each summer, and then buying smaller ones as the summer ends. And people who aren’t out in the sun much might be better off just buying smaller packs. Of course, it’s important to apply the right amount – so don’t scrimp.

Paid advertisement

The cheapest ways to get Wimbledon 2026 tennis tickets

From the ballot to the queue, here’s how to get in at SW19

Wimbledon is one of the highlights of my summer, even though getting a ticket to see the tennis isn’t always cheap or easy – but you can do it on a budget.

Here are my top tips for getting a cheap ticket now the Championship is underway.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

1. Go in the first week

In terms of value for money, the best way in my experience is to go towards the end of the first week (which this year started on Monday 29 June). 

At this point, the tournament will be in the second or third round where the players will be much more evenly matched. Round one games, especially with the top seeds, can often be a whitewash. 

If you want to experience Centre Court, the cheapest tickets are for the first couple of days.

2. Try to buy last-minute tickets

If you’re looking to guarantee a ticket before heading out, such as if you live a little further afield, then last minute ticket options might be an option.

Try your luck the day before

Some tickets are typically sold a day or two before, but there’s no details on the website about them just yet. You normally need to download the official Wimbledon app to get them, so it’s worth downloading and signing up to prep. 

American Express cardholder tickets

American Express cardholders might be able to grab themselves some last-minute tickets to Centre Court during the tournament. It’s not been confirmed for 2026 yet, but if it’s running again any sales will be revealed on Amex socials this year, so give them a follow.

Last year you were able to buy tickets on the Saturday before each week started, with finals tickets appearing on the Thursday before.

Ballot tickets

You might still be able to get access to returned ballot tickets – these will be restricted to those who were unsuccessful in the ballot. Those who are eligible will get an email detailing how to access the resale. 

In previous years you needed to be quick. Several hundred tickets for Centre Court and Court 3 went on sale at 9am the day before. Returns for the same courts went on sale roughly 48 hours before the start of play, also via Ticketmaster. 

It’s a good idea to sign up for the Wimbledon newsletter to be the first to know of any extra ticket releases.

Paid advertisement

3. Join the queue

The queue is a great way to nab yourself some great tickets on the day. It’s an early start, especially if you live outside of London, but it’s quite an experience in itself – you even get a booklet on how to queue (how British!). 

It’s first-come, first… serve (sorry) so the earlier you join the queue the better. If you want a show court you’ll need to be there overnight. A limited number of tickets are available for Centre, No.1 and No.2 Courts. Only one ticket can be bought per person, so you need to be queuing together to get more than one.

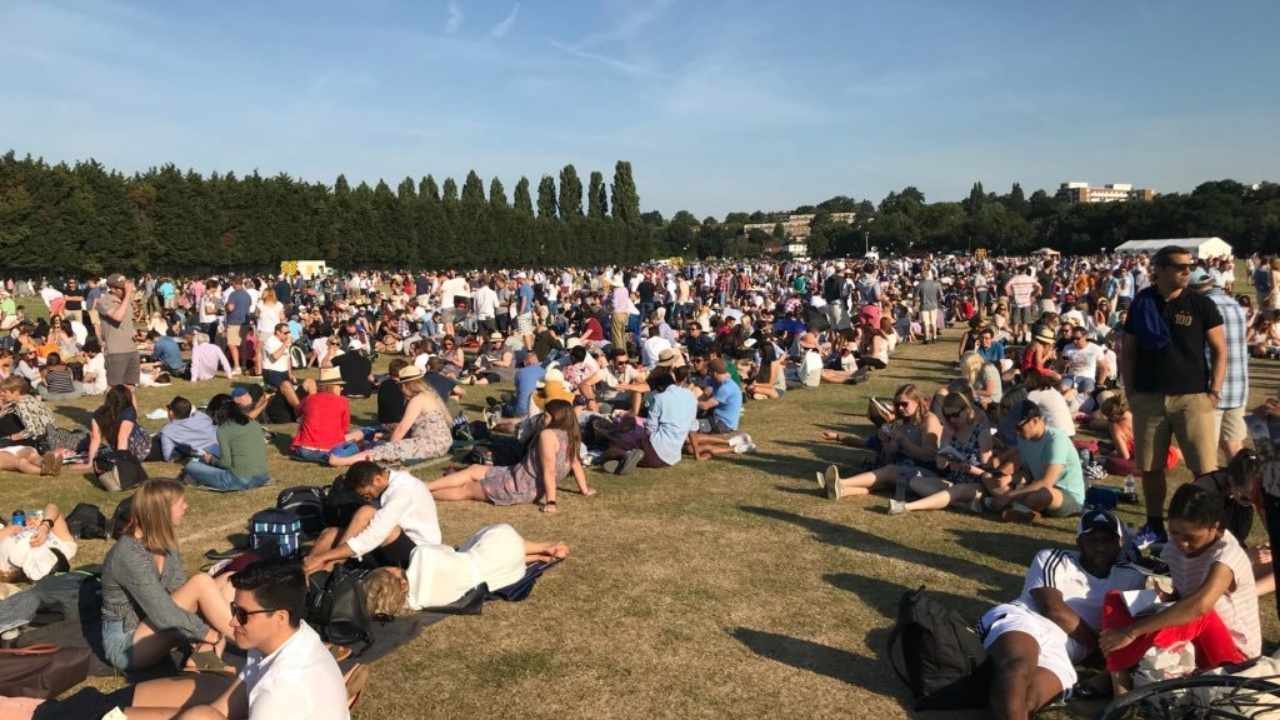
For other tickets, well the earlier the better is still the case. Historically, we’ve arrived at around 7am, and didn’t get into the grounds until just gone 1pm! But for most of that time we were just sat in the sun in a field which was actually really nice – just bring a book! There are toilets, food outlets and water refill stations.

Gates open gradually from 9.45am and play normally starts on outer courts around 11am. There’s usually a comprehensive guide to the queue on the Wimbledon website which details how it’s handled.

This year you’ll need to download the Wimbledon app and sign into a MyWimbledon account so it’s worth doing this ahead of time.

People queuing for Wimbledon
The Wimbledon queue when we arrived just after 7am

4. Get a ground pass

The best way to save money on Wimbledon is to get a Grounds Pass – these let you watch some quality tennis on the outer courts for a fraction of the price. In week two you’ll have fewer singles to watch but don’t worry, there’ll be some great doubles action if you go on a Monday or Tuesday.

If you are early (and quick) there are also some unreserved seats and standing space on Court 3. A ground pass will cost you £33 during the first week, less from the second Tuesday onwards.

5. Get £10 returns

It used to be that extra tickets went on sale from a hut inside the grounds. These became available as people left for the day and donated their ticket to be resold, with profits going to charity. But it meant more queuing!

The good news is this changed recently, and you can now do it via the Wimbledon app. You’ll need to get your phone scanned at kiosks in the grounds or the queue by 2.30pm. Then as tickets become released between 3pm and 9pm, keep an eye out for a text message saying you’ve “won” a show court seat.

You’ve 10 minutes from the text to accept it, and another 20 minutes to pay for your ticket from the resale kiosk by Court 1.

Costs in 2025 were:

  • Centre Court: £15
  • No 1 Court: £10
  • No 2 Court: £10

6. Bring your own food

Once you’re in, it gets very expensive. Check the T&Cs on your ticket and on the Wimbledon website, but to avoid paying high prices for disappointing burgers, bring a picnic. The same is the case with drinks. You’re allowed to bring your own booze – though not spirits – and there are (fairly generous) limits per person. Remember to bring along a corkscrew to avoid taking a bottle of wine on a day trip (speaking from experience).

Don’t forget a bottle of water – there are fountains where you can refill  – and bring along sun cream, or risk paying over the odds for it in the shop. You’ll save near on £20 this way, if not more.

Amex cardholders are usually able to get a discount on purchases in the Amex lounge while last year Barclays customers got free strawberries and cream – so keep an eye out for anything like this.

7. Go there after work

If the sun is shining, there’s every chance play will carry on until 8 or 9pm. Possibly even later now there’s a roof on Court One as well as Centre.

When I went a few years ago there was a discounted cost after 5pm – entrance to the grounds was £14 after during week one, less in week two, so I’d expect it to be not too much more this year. 

However, you can only buy these tickets if people have left the grounds as it’s one-in, one-out. 

8. Look for people leaving show courts

If people look like they’re calling it a night, just ask politely if they mind giving you their ticket. This is the best way to get yourself into Centre Court. It’s worth a shot!

I used to do this as a kid, and managed it again at the French Open a few years ago (using some very poor GCSE French!).

A couple of years ago one bloke a few feet away just shouted out if anyone wanted his tickets as he was on his way out. We just missed out!

9. Ask if you can take empty seats.

Late on, you’ll see many seats empty as corporate guests head home. The likelihood is they won’t hand their tickets in to be resold so there’s no official way to fill the seats.

So a young ‘un, I used to just be a bit cheeky and ask if I could nip into one of the empty seats at the back – and I often got onto Centre or No. 1. It might not work, but you’ve nothing to lose.

10. Get a refund if it rains

We all hope it won’t happen, but there’s rarely a year when play doesn’t get rained off. If you see less than an hour of play due to rain you can claim a full refund. If it’s more than an hour but less than two, you’re entitled to 50% back.

Our podcast

Listen to Cash Chats, our award-winning podcast, presented by Steve Alderton and Editor James Andrews.

Episodes every Monday.

Paid advertisement

11. Watch it on the big screen

If you don’t fancy getting up really early, or get there too late, then there are a load of big screens across London, and no doubt other big cities too. They often have deck chairs and a nearby bar! 

A great one is the free open air screen from the canal side steps on Granary Square in King’s Cross. The steps are covered in AstroTurf and there’s usually beanbags and cushions. Nip to a nearby shop to pick up a can of Pimm’s and you’re good to go.

12. The Wimbledon Ballot for next year

Most of the tickets for the show courts are sold through a public ballot which generally opens in September, with the results announced in February. Members of some tennis clubs and the LTA also get access to another ballot.

If you miss out there are often additional sales opportunities for returns in the spring, but you need to have entered the initial ballot.

Theatre deals and discounts

Tickets to shows may be pricey, but there are ways to save

Looking for cheap deals and discounts for theatre tickets in the West End and elsewhere? We’ll post regular sales or decent offers here.

Don’t forget to read our guide to getting cheap theatre tickets.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

Annual sales and offers

London Theatre Direct: summer sale

London Theatre Direct’s Big Summer Event is live, with tickets for as low as £19.

Shows include:

The sale runs until 13 July 2026.

Kids Theatre Week (July to August)

Kids Theatre Week runs every summer, and is available from Monday 20 July to Monday 31 August . Tickets will go on sale at 10am on Tuesday 9 June, and they tend to sell out fast, but more tend to be released to coincide with the start of the summer holidays.

You can get one free child’s ticket (and two more at half-price) at a series of West End shows when you buy one full-paying adult ticket. It’s for shows from 20 July to 31 August, not just one week. A child is anyone 17 years old and under.

Tickets are limited with big shows quickly selling out, but there are plenty of options in the past including Hamilton, Harry Potter And The Cursed Child, Mamma Mia and kids’ shows The Lion King, Matilda The Musical and Alice in Wonderland. And keep an eye out, as more seats might be released for those popular productions.

The only thing I’d say is the adult tickets are full price so you might be better off looking at other deals if more than one adult is attending.

Official London Theatre New Year Sale (November 2025 to March 2026)

Official London Theatre holds a New Year sale semi-regularly, with some big shows at least 20% off. Last year, it started on 25 November 2025.

Tickets are either £10, £20, £30, £40 or £50, with no booking fees.

This year, it’s running from 10 am on 18 November for performances until February. It’s often extended into March.

Here’s what you can get tickets to:

  • Arthur 
  • Back To The Future – The Musical 
  • Black Is The Color Of My Voice 
  • The Boy At The Back Of The Class 
  • Cabaret 
  • A Christmas Carol – A Ghost Story 
  • Daniel’s Husband  
  • The Devil Wears Prada 
  • Disney’s Hercules 
  • Disney’s The Lion King 
  • The Firework Maker’s Daughter 
  • Hadestown 
  • Hamilton 
  • Harry Potter And The Cursed Child 
  • High Noon 
  • The Hitchhiker’s Guide To The Galaxy 
  • Hooray For Hollywood 
  • Into The Woods 
  • Just For One Day – The Live Aid Musical 
  • Kinky Boots 
  • Lost Atoms 
  • Lucie Jones: Live At The London Palladium 
  • Magic Mike Live 
  • Mamma Mia! 
  • RSC’s Matilda The Musical 
  • Les Misérables 
  • MJ The Musical 
  • Monopoly Lifesized 
  • The Mousetrap 
  • My Neighbour Totoro 
  • Oh, Mary! 
  • Oliver! 
  • Opera Locus 
    Othello 
  • The Paddington Bear Experience 
  • The Phantom Of The Opera 
  • The Play That Goes Wrong 
  • Potted Panto 
  • The Producers 
  • The Rapping Princess 
  • The Red Shoes 
  • Showstopper! The Improvised Musical  
  • Six 
  • The Snowman 
  • The Spy Who Came In From The Cold 
  • Starlight Express 
  • Stranger Things: The First Shadow 
  • Sunny Afternoon 
  • Titanique 
  • Top Hat 
  • Tutu 
  • RSC’s Twelfth Night 
  • Wicked 
  • Witness For The Prosecution 
Paid advertisement

London Theatre Week (February and September)

Twice a year, TodayTix and other sites offer discounts at a decent number of West End shows in an event called London Theatre Week. It runs in February and September.

During these dates, you can book to visit the theatre in the coming months for heavy discounts — prices are either £15, £25 or £35.

The dates you can get discounts on vary massively between productions, but for a lot of them, you can book for a couple of months. There are tickets to The Great Gatsby, My Neighbour Totoro, Hamilton and Hercules included in the promotion.

It’ll likely return again in August 2026.

Flash promotions & sales

Central Tickets: Get 10% extra credit with your first top-up

If you top up your Central Tickets account for the first time, you can get 10% added by Central Tickets, up to the value of £10. 

The credit in your account is used as payment for seat filling bookings you make through Central Tickets. It can’t be used on West End offer tickets (listed in a separate tab on their site).

You won’t be able to get a refund on it, and it won’t be protected if Central Tickets were to go bust, so make sure you’ll make use of the money you top up before you do so. 

Central Tickets will add up to £10, so you could get £110 worth of credit for £100. 

TodayTix: up to 50% off in Boxing Day sale (ended)

TodayTix tends to run sales throughout the year and the latest is offering up to 50% off tickets in their Boxing Day sale. There’s no end date published, but I’d expect it to be until the end of January, if not early December (though the actual performances can be after these dates).

Paid advertisement

Theatre Tokens gift card discounts

There are occasionally discounts such as save 10% on Theatre Tokens – the official theatre gift card that’s valid at hundreds of locations nationwide and the TKTs Booth in the West End. We’ll add them here when we spot them.

Theatre Tokens: 10% off

If you buy a Theatre Tokens gift card and use the code Tfl then you can get 10% off your purchase. These gift cards can be redeemed at over 300 theatres nationwide and don’t have an expiry date.

You can order a total of £500 worth of gift cards per household, which would get you a £50 discount.

Previous offers

TodayTix: 25 shows for £25 each (expired)

Until 4 June you can book £25 tickets at 25 different West End shows via TodayTix. This includes Book of Mormon, We Will Rock You, Wizard of Oz and Punchdrunk’s Burnt City.

Food and drink deals

The best deals right now for some free or cheap food and drink

From lunch discounts and vouchers to free samples and deals, read on for the best food and drink deals currently available.

We’ve split the supermarket special offers and tea and coffee shop deals over to separate deals pages as there are just so many!

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

Online offers

Coffee Friend: up to 50% off coffee beans

If you love an at-home cup of coffee, Coffee Friend has a sale on, offering up to 50% off coffee beans and 30% off coffee capsules.

You can get the largest discount when you purchase multiple bags.

Shop deals

Morrisons: free doughnuts for Dads

For Father’s Day weekend, you can get a free doughnut in-store at Morrisons if you’re a dad or father figure. No purchase or More card is necessary — just rock up and ask for one at the Cafe.

Hotel Chocolat: free treat on your birthday

If you sign up to Hotel Chocolat’s VIP ME scheme you’ll get a free gift on your birthday (I got a free £5 voucher to spend), as well as other offers through the year such as 15% off your next purchase. You can only sign up in-stores.

Krispy Kreme: free doughnuts

Download the Krispy Kreme Rewards app to get a free Original Glazed doughnut when joining and another on your birthday. You’ll also get points every time you spend that can be spent in-store.

25% off Krispy Kreme

You’ll be able to get 25% off your doughnuts Sunday to Thursday if you have Meerkat Meals from Compare the Market. There’s a hack that’ll get you access to this for a year for £1, as well as 2-4-1 movies.

Recipe box discounts

We’ve written about recipe boxes in detail here, but below are some special offers.

Gousto: up to 75% off first box via Quidco

There are often voucher codes for Gousto, but if you’re new to Gousto and go via a cashback site you can save even more.

The deals seem to change fairly regularly and switch between TopCashback and Quidco, so it’s best to check both to see which is best.

At the time of writing, going via Quidco can get 50% off your first box, and up to £12 cashback on top.

So the most expensive box (four meals per box for four people) would normally cost £47.85, but the discount brings it down to £23.93. Add in the cashback and you’ll get the recipe box for £11.93 instead!

If you’re also new to Quidco, then you can get an additional new customer cashback bonus.

Hello Fresh: up to 66% off first box via TopCashback

If you go via TopCashback (this one also switches between the two cashback sites, so check Quidco too) for HelloFresh then you can get 50% off your first box and £10.20 cashback on top. When you order the largest box (five recipes a week for four people), it brings the total down to £21.30.

Here you can nab a new customer bonus for the cashback sites too if you’re new to either site.

Hello Fresh: free delivery with Amazon Prime

You can now get free delivery on your Hello Fresh deliveries for a year with an Amazon Prime membership. Delivery usually costs £4.99, so this could save you £20 a month if you get a box every week.

You’ve got to go here and sign in to your Amazon account where you can connect it with your Hello Fresh account. This works if you already use Hello Fresh. You get free delivery for a year if you keep your Prime membership.

[Skimlinks]

Energy price cap to rise by 13% from July 2026

The average household will pay £1,862 a year, mostly as a result of the price of gas

The energy price cap is rising by a huge 13%, going up by £221 per year for the average household. This will increase bills by around £18 per month. This only applies to those who are on a standard tariff, so if you have a fixed rate, you’ll be locked in at the price you fixed at.

Here’s what you need to know about the cap and how much you’ll pay.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

How the energy cap works

The energy price cap is a limit set every three months by Ofgem, the government’s energy regulator. It restricts how much an energy company can charge customers.

The cap applies to the price of your gas and electricity on your energy company’s default or standard variable rates. These basically can go up and down whenever the energy company likes. With the cap, the energy companies have to make sure their tariffs aren’t higher than the set rate.

Despite its name, it’s not a maximum amount that you can pay for your energy. Instead, the prices set on the cap are the maximum price per unit of energy you use. Ofgem announces the figure as an annual price, as you probably don’t have a clue how many kWh of energy your family uses. 

Because of this, the quoted “cap” (£1,862) is an annual price based on a typical household. If you use more energy, you’ll pay more than the cap every year. Use less, and you’ll pay less.

There are separate caps for gas and electricity, and each cap is also made up of a standing charge (a set amount each day, regardless of whether you use any energy) and a usage charge. 

The cap will also vary depending on where you live in the UK. Prepayment caps used to always be a little higher, although this recently changed. The new energy price cap also applies to those with a prepayment meter. 

Crucially, if you’re on a fixed-rate deal, then the cap doesn’t apply and the price you pay won’t change until that fix ends.

What is the new energy price cap?

The latest announcement is a rise to the price cap from 1 July until 30 September 2026.

The new cap for a “household with average use” is £1,862 a year. This is up by about £220, or 13% from the current rate.

If you break it down to each actual unit cost, the average caps are:

 Energy price cap per unit and standing charge 1 April to 30 June 2026Energy price cap per unit and standing charge 1 July to 30 September 2026
Electricity24.67 pence per kWh
57.21 pence daily standing charge
26.11 pence per kWh
57.19 pence daily standing charge
Gas5.74 pence per kWh
29.09 pence daily standing charge
7.33 pence per kWh
29.04 pence daily standing charge
Source: Ofgem

This does vary based on where you live, though the Ofgem website has a full breakdown of the regional caps for all standing charges and units.

What is the new average monthly energy bill?

Despite Ofgem attempting to present the information in a way we understand, the total annual cap figure isn’t always the easiest to comprehend – especially since our energy use changes throughout the year, but this cap only applies to three months.

At the same time, it’s not a flat increase to all bills as there could be different percentage changes to standing charges and unit rates.

So we think it’s easier to understand the price cap when you view it as a monthly direct debit. Your energy company calculates this by taking the predicted cost for a year based on your previous energy usage and dividing it by 12. It’s not 100% accurate, but it’s a handy comparison.

As the cap is up by £220 per year, that makes it around £18 more each month. The average monthly bill will be £155.

What is the current energy price cap?

The current price cap (1 April to 30 June) is £1,641 a year, based on the average household. This is with the newer typical use figures.

When will the new prices start?

This new energy price cap will come into play on 1 July 2026 and will remain in place until 30 September 2026.

How much will you pay under the new energy price cap?

Remember, the price cap figures are based on average use. If you use more than this average, you’ll pay more; if you use less, you’ll pay less. Plus, it can vary regionally, so you’ll need to check where you live to see exactly what it’ll be for you.

If you want to get a rough, quick idea, you can add 13% to what you pay at the moment. This doesn’t take into account the balance between unit and standing charges, or whether you’ve got an accurate direct debit set-up, but it could give you a sense of how much it’ll be.

Will you pay more or less money with the new energy price cap?

If you’re on a variable tariff

Broadly, anyone on a standard tariff will be charged less per unit of energy from 1 July 2026. Of course, the bill itself will be based on your actual energy use. 

If you’re on a prepayment meter

There is no longer a significant premium for those with prepayment meters. You can see the cap for your region on the Ofgem website.

If you’re already on a fixed tariff

If you’re fixed on a tariff, your prices usually don’t change when the price cap changes. That’s because you’ve already agreed on a price per unit of energy for a fixed length of time with your energy supplier, usually 12 months.

For April’s price cap change, the prices fell for everyone due to an end of funding for the Energy Company Obligation scheme and removing 75% of costs for the Renewables Obligation scheme from energy bills. This time, they’ll only go up for those not on a fixed tariff.

Should you fix your energy?

We’ve seen more fixed deals returning to the market in the last couple of years, and right now, the cheapest 12-month fix is around 4% less than the current April price cap. The price of these tariffs depends on where you live, but it’s still worth checking them out to see if you’ll save.

You’ll be comparing prices based on the price cap now, rather than the July one, so make sure you consider that.

If you go for one of these, bear in mind that some will charge an exit fee if you want to swap suppliers before the end of the term.

There are also some tariffs that track at below the cap, so you’ll always pay less – but not necessarily less than a fix.

Of course, these can change, so it’s worth using a comparison site to see what rates are available.

Will bills go up again?

This rise is pretty staggering, but it may not be the end of rises. The current predictions suggest that the price cap could see another rise in October, but a lot can change in that time.  

When is the next price cap change?

The price cap is reviewed every three months (before October 2022, it was every six months).

The price cap will next change on 1 October 2026, and will be announced by 26 August 2026. After this, it’ll change again on 1 January 2027, a change that will be announced in November 2026.

How you can reduce your bill

Paying by direct debit will reduce your bills, so it’s well worth doing this.

Otherwise, it’s hard to do much to reduce what you spend on energy other than by using less energy. The standing charges will still apply, and bills will still be sky-high, but cutting back on gas and electricity will mean you pay less.

It’s worth giving accurate meter readings if you’re not on a smart meter. This will mean you’re more likely to have an accurate direct debit on current use, rather than what you used last year, and it stops you from falling into debt on your energy account. Your energy firm will probably not change this automatically, so you might need to ask.

Don’t forget, a direct debit averages the spend out over the year, so you should hope to overpay in the summer and underpay in the winter to help even out your bills.

How has the price cap changed?

As you can see, the really big changes have happened since October 2021. Before this, the average direct debit was under £100, so even with recent cuts, we’re still paying more, and even more on top if you had been saving with a lower fixed-rate deal.

These are the energy price caps going back to 2019, we’ve roughly adjusted them for the new typical use figures. You can see the historical price caps with the old figures below.

DateCost per year with new typical use figuresEPG & grantsAverage monthly billChange (+/-)
July to September 2026£1,862N/A£155+13%
April to June 2026£1,641N/A£137-7%
January to March 2026£1758N/A£146+0.2%
October to December 2025£1755N/A£146+2%
July to September 2025£1,720N/A£143-7%
April to June 2025£1,849N/A£154+6.4%
January to April 2025 £1,738N/A£145+1.2%
October to December 2024£1,717N/A£143+9.5%
July to September 2024£1,568N/A£131-7.2%
April to June 2024£1,690£3,000 EPG£141-12.34%
January to March 2024£1,928£3,000 EPG£161+5.13%
October to December 2023£1,834£3,000 EPG£153-7.95%
July to September 2023£1,992£3,000 EPG£166-17.04%
April to June 2023£3,151£2,402 EPG£200+50.33%
January to March 2023£4,110£2,402 EPG & £67/m grant£1330.00%
October to December 2022£3,409£2,402 EPG & £67/m grant£133-15.62%
April to September 2022£1,893£158+54.35%
October 2021 to March 2022£1,227£102+12.21%
April to September 2021£1,093£91+9.21%
October 2020 to March 2021£1,001£83-7.46%
April to September 2020£1,082£90-4.50%
October 2019 to March 2020£1,133£94-5.98%
April to September 2019£1,205£100+10.29%
January to March 2019£1,092£91
Estimated costs, due to the change in the typical domestic consumption

Historical energy price caps

These are the energy price caps from before the typical use figures changed. This change made it difficult for us to compare new caps with the old ones, so we’ve converted the old price caps into ones with the new typical figures above.

DateMax annual bill for a typical householdAverage monthly direct debitChange +/-
October to December 2023£1,923 price cap / (£3,000 EPG)£160.25-7%
July to September 2023£2,074 price cap / (£3,000 EPG)£173– 17%
April to June 2023£2,500 EPG / (£3,280 price cap)£208 (£273.33 without EPG)+ 19% (-23.3%)
January to March 2023£2,100 (£2,500 EPG – £400 grant) / (£4,279 price cap)£175 (£356.58 without EPG and grant)+ 0% (20.5%)
October to December 2022£2,100 (£2,500 EPG – £400 grant) / (£3,549 price cap)£175 (£295.75 without EPG)+ 8%(+80%)
April to September 2022£1,971 price cap£162.25+54%
October 2021 to March 2022£1,277 price cap£106.42+12%
April to September 2021£1,138 price cap£94.83+9%
October 2020 to March 2021£1,042 price cap£86.83-7.5%
April to September 2020£1,126 price cap£93.83-4.5%
October 2019 to March 2020£1,179 price cap£98.25-6%
April to September 2019£1,254 price cap£104.50+10.2%
January to March 2019£1,137 price cap£94.75

Travel money: Find the best currency exchange rates

Here’s how to get the most euros, dollars and more for your pounds when you’re getting travel cash for your holiday

Looking for the best ways to get your currency? Well, coins and notes aren’t going to be the best way to pay, and I rarely use them. In fact, when I go overseas the bulk of my spending is with a debit or credit card (a fee-free one naturally).

But from giving a tip through to buying from street vendors, not everywhere takes cards – and ATMS can charge per withdrawal. So having some cash with you makes sense, and here are the five ways you can get the best exchange rates.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

1. Ignore “0% commission” signs

One of the most misleading signs on the high street is the one that says “0% commission”. It makes you think that you’re not getting charged anything to change your cash – but you will be.

Rather than add a commission on top of your swap, the bureau de change will simply set their own exchange rate! You can read more about this in our “Why 0% currency commission is a lie” article.

2. Don’t get travel money at the airport

Since bureaus and banks are allowed to set their own exchange rates, it makes sense that the worst rates around will be at the airport. Once you’re there, and particularly once you’re through security, there is nowhere else you could go to get travel money than the bureaus in the departure lounge. 

The only workaround if you really have left it too late to go elsewhere is you can order in advance online to collect at the airport, and you’ll get a better rate than just walking up to the booth. You will often need three or four hours notice though.

Paid advertisement

3. Compare for the best exchange rates

Instead of just popping to your bank or the Post Office as many do, it’s better to compare all the different rates available in your area. The tool I use for this is Money Saving Expert’s Travel Money Max. You can choose between collection, delivery and even airport collection, and you’ll be shown the best rates.

Your choice will increase massively if you live in London, but you’ll still get a decent range of options elsewhere. Do check whether you need to order in advance to get the rate you see – some will charge you a worse rate if you don’t.

4. Don’t use a credit card to swap your cash

Once you know where you’ll get your cash, you want to avoid any extra charges on your swap. This means paying with cash or a debit card. That’s because using a credit card is what’s known as a “cash advance“.

With this you’re effectively taking money off your card as cash and then using the cash to make the transaction – even if you don’t actually get your hands on any physical notes and coins to hand over.

Featured deal
Customer rating 3.9/5
  • Switch bonus
    £240
  • Perks
    8% regular saver
  • Monthly fee
    0
  • Offer ends
    Unknown
  • FSCS Protected? Yes
  • Bonus requirements To get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
  • Regular saver 8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
  • Existing customers? You can't have held a Santander account on 1 January 2026.

5. Get a specialist card for extra cash machine withdrawals overseas

Don’t take too much cash with you. Apart from the risks of losing it, if you don’t spend all of it you’ll get a poor rate when you try to swap it back to sterling. So instead I’d recommend you only take out enough to cover essentials for the first few days – depending on the infrastructure at your destination of course.

Then, if you need more cash, you can use an ATM. Though some of these will have local fees set by the bank you use, you won’t have any charges on the exchange rate at all if you use a specialist card such as Chase or Starling.

Cut the cost of using your mobile phone abroad

Don’t blow your holiday budget on your mobile bill

Since Brexit, most major mobile networks have reintroduced roaming charges. And with the constant desire to stay connected, and use your phone to get around, you can end up with a huge bill.

Here’s what you need to know about roaming charges for the major networks, and a few tricks to help you keep costs down.

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

Can you get free roaming?

Until the end of 2020, you were able to use your inclusive data, calls and texts when travelling in Europe. And some mobile companies, such as Three, offered the same deal in countries further afield, including the USA and Australia. O2 is the only major network to carry on offering this — here are the rules for each of the networks.

O2 & Virgin Mobile – free roaming continues

The only major network to retain free roaming is O2, with extra benefits if you also get Virgin Broadband. You can call and text UK numbers from abroad and use your data up to the limits in your monthly allowance or 25GB, whichever is lower.

This only applies in European countries, and you’ll be capped at 25GB of data a month if your normal allowance is above this.

For travel outside of Europe, you can buy an O2 Travel Bolt On for £7 a day which covers 27 worldwide destinations (full list here). You’ll get unlimited data each day, plus 120 minutes of talk time and texts to UK numbers. Some more expensive packages include this, usually those with 30GB of data or more.

If you’re on Pay As You Go, you can get the O2 Travel Bolt On for £1.99 a day in selected destinations.

Or, if you’re with Virgin Media for your broadband then you can link your accounts to get this Bolt On added to your phone tariff for free.

Vodafone

General roaming charges now apply to anyone who took out a Vodafone contract after 11 August 2021. There’s no change for contracts taken out before this.

However, pay monthly plans and Pay As You Go include roaming in the Republic of Ireland, Isle of Man, Iceland and Norway.

Some more expensive contracts will include roaming in the EU and beyond, but if you’re on a basic plan you’ll pay £2.57 a day if you’re travelling in Europe. You can reduce this with an eight-day pass for £16 or a 15-day pass for £21.

Paid advertisement

EE

Your roaming charges will depend on your plan and where you’re travelling.

For example, if you pay monthly for your EE phone contract, you’ll be charged £2.72 a day or £16.50 for seven days if you’re travelling in Europe.

Then there are zones for the rest of the world. If you’re visiting the USA, China, India and a few others in Zone 1, it’ll cost £6 a day or £30 for seven days. The most you’ll pay is £16 a day if you’re going to Zone 4 countries including Nepal and the Maldives.

If you’re on PAYG, you’ll need to pay £2.50 for a day or £10 for seven days to use your allowances in Europe.

If you’re on EE’s Full Works plan, you’ll get its EU and Roam Further Pass included, although this is one of the more expensive contacts.

Three

The Go Roam benefit offered free roaming outside the EU, but all included roaming ended for anyone who took out a new contract or renewed a contract after 1 October 2021.

Now Three offers roaming in Europe for £2 for a day, £5 three days, or £12 for a week.

It’ll cost you £5 a day for the rest of the world to use your existing allowances, with three days costing £12.50 and a week set at £30.

There’s also a £7 a day Data Passport which offers unlimited data abroad.

However, it’s free in the EU if you use (or buy) a Three Pay-as-you-go SIM.

Other networks

Here’s what some of the other networks are doing:

  • BT Mobile – free European roaming remains
  • Giffgaff – free European roaming remains
  • ID Mobile – free European roaming remains
  • Lebara – free European roaming remains
  • Sky Mobile – free roaming ended in May 2022
  • Smarty – free European roaming remains
  • Tesco Mobile – free European roaming remains
  • Voxi – free roaming ended in May 2022
Paid advertisement

New rules to cut roaming fees

Mobile network providers must tell you if you’re going to be charged for roaming when you’re abroad under new proposals from Ofcom (the UK’s communications regulator). The provider has to tell you the costs, fair use limits and any relevant time limits. They should also inform you of how to set a limit on your spending.

These rules were introduced on 1 October 2024.

How to reduce your phone charges abroad

Check your destination

Even if you have roaming included or there’s the option to set a daily price cap – check that the country you’re going to is part of that deal. If it’s excluded then you’ll need to look at some of these other tips.

Switch to a different mobile network

As well as O2 and Virgin Media, many smaller networks are keeping EU roaming. These could well be cheaper than the major networks back home, too.

If you don’t fancy doing this permanently, you could look at Three’s PAYG SIM or sign up for just one month of one of the smaller networks.

Get an eSIM

An eSIM is a handy way to get service while you’re abroad. It’s essentially a digital SIM card that you can load onto your phone to use local network providers. You can get ones that are just data, or you can get one with a local phone number to also make calls and send texts.

We have a full guide on eSIMs here where we explain how they work, the benefits and the savings you can make.

Cap your charges

If you don’t want to switch, you should find out what your network will charge where you are going.

It’s worth seeing if your network has a cap on overseas charges, particularly for data. This will stop your bill getting out of control – but don’t assume you’ll get this. You often have to ask for this to be implemented.

Get a bolt-on

Another option is to buy add-on packages that give you a pre-agreed amount of minutes, texts or data to use when abroad.

Get Volt via O2 and Virgin Media

Worldwide roaming is included if you have both a mobile with O2 and broadband from Virgin Media. Though only go down this route if the prices for both are decent.

Turn off your data and use Wi-Fi instead

Another option is to simply not use data at all. You need to do this before you get on the plane, train or boat. Go to your settings and turn off data roaming or mobile data – and keep it off until you’re back in the UK.

This also means the apps on your phone won’t automatically access data behind the scenes. It also protects against accidentally opening your email — yep, you’d get charged, even if it’s just a few seconds.

If you’re in a destination where roaming is included, check your limits. There may be a reduction in how much of your regular allowance you can use.

With data turned off, the only way to connect to the web will be using Wi-Fi. You might get lucky and get it for free at your hotel. If not, look for coffee shops and public spaces that don’t charge. You can research in advance too, using the Wi-Fi Finder app.

However, be careful using unsecured Wi-Fi with banking apps or online shopping. Don’t enter login or password details.

Write shorter texts

If your text is longer than 160 characters, it’ll count as two texts (or more), so try to watch your words. It’s also worth not sending picture messages via text (at home and abroad) as they’ll be charged extra. Use messaging apps instead (when you’re on Wi-Fi).

Our podcast

Listen to Cash Chats, our award-winning podcast, presented by Steve Alderton and Editor James Andrews.

Episodes every Monday.

Paid advertisement

Be careful when making local calls

Unless you’ve got a specific add-on which allows it, any calls you make to numbers at your destination or texts messages to local mobiles aren’t included in roaming. You might be better off getting a local SIM or calling card if you’re going to make a lot of these calls.

Don’t answer calls and turn off voicemail

Outside inclusive roaming counties you’ll often be charged to answer a call, so don’t answer unless you need to. You won’t be charged to get a text message though, so tell mates back home that’s the best way to communicate with you while you’re away.

Some networks – with EE the worst – will also charge you for receiving a voicemail when abroad, even if you don’t access it. I always used to call my provider and turn voicemail off before I left to avoid any unnecessary charges.

Use apps to make calls and send messages

When you’re connected to Wi-Fi, you’ll also be able to use apps like WhatsApp to make free calls and send messages, including photos.

This cuts out the costs of making and receiving calls overseas. However, if the Wi-Fi signal is weak, it can be a very frustrating phone call!

LTV & the remortgaging tricks that’ll save you thousands

Don’t miss out on even better deals when looking for a new mortgage offer.

If you’re on a fixed mortgage deal, you might just see remortgaging as something you need to do to avoid moving on to a more expensive standard variable rate. Of course, doing that will save you money but it’s possible to use remortgaging to reduce how much you pay over the term even more.

I’m not going to go through everything you need to do when you remortgage here – things like check your credit report for errors, get paperwork together and watch your spending and credit applications in the run-up to your application.

This is all very important stuff and could well have changed since you last got a mortgage. So do read up on all of that.

Instead, I’m going to focus here on a few simple things you can do that could make a big difference to the monthly and total cost of your mortgage. And the main one involves something called “Loan to Value”.

Watch this video or keep reading (or both)

Some articles on the site contain affiliate links, which provide a small commission to help fund our work. However, they won’t affect the price you pay or our editorial independence. Read more here.

Paid advertisement

What is Loan to Value?

Loan to Value, or LTV, is essentially how much you have borrowed compared to the value of your home. So if you originally bought a £300,000 house with a £30,000 deposit you would have had an LTV of 90%. That’s a mortgage loan of £270,000.

So why does this matter to remortgaging? Well, LTV is measured in bands. They generally start at 95% (meaning you’ve put down a 5% deposit) and drop in 5% increments down to 60%, though sometimes the gaps between tiers are larger (eg 75% and then 60%).

Mortgage interest rates tend to then drop for each band you move down. And obviously the lower the interest rate you get, the less you’ll pay.

For example, at the time of writing, the lowest available five-year fix is 4.48%. This is based on taking out a 25-year mortgage term with a 60% LTV. At 80% LTV, the lowest five-year fix available is 4.68%, at 90% that rises again to 4.84%.

And over time there’s a good chance your LTV will have changed, thanks to prices rising as well as you paying off some of your loan, meaning you might get a better deal when it comes around to remortgaging.

There are two key changes that could have affected your LTV since you agreed to your last mortgage deal.

Tembo Mortgage

Try our mortgage calculator

Our mortgage calculator helps simplify things by giving you an idea of how much you could borrow and your likely monthly repayments.

How your LTV could have changed

First, unless you’re on an interest-only mortgage, you’ve been paying into your mortgage every single month, building up equity.

Say you’ve knocked £15,000 off the mortgage in equity payments (don’t forget some of your monthly repayments will have gone towards interest charges), then you have added an extra 5% to what you own. This means your LTV would now be 85% and you can apply for the next tier of mortgages.

And second, your property value could have increased. Let’s say it’s now worth 5% more at £315,000. That’s an extra £15k. Alongside your initial deposit and the £15k in repayments, it would give you £60,000 of equity – roughly 19% of the total value. That means the LTV is now 81%. 

However, in the example above, the repayments and extra value might give an LTV of 81% but it would still only mean getting access to deals in the 85% LTV bracket, rather than 80%.

When you’re really close to a new tier, finding some extra cash from savings or cutting back ahead of remortgaging would be well worth it. Here an extra £3,000 might seem a huge amount but the drop down to the 80% band could be a big saver over time.

Using our example mortgage size, a 0.45% difference between 85% and 80% LTV tiers over five years would be just £2,000, but over 25 years that variation in rate would be worth £15,000.

It’s worth having a go on our mortgage calculator to find out what effect things like different rates have on payments, so it’s worth taking a look at playing around.

How to get a new valuation for LTV

You can get a sense of price changes using a site like Zoopla. You put your postcode in and you’ll get an estimate as to the current value of your property. It’ll be shown in a range which can be quite broad. When I looked, for example, it suggested my house had gone up by £20k to £79k in value since we paid for it two years ago.

You can also get an idea from Zoopla and RightMove as to what the list prices were for other similar properties that have sold recently. Have a nose at the listings online so you can see if it’s a similar layout and standard inside. Remember these are just asking prices, so the actual deal could be different.

For a more accurate idea you could invite an estate agent over to give you their input – there’s no commitment for you to list the house if you do this. You can then put a figure on your application. 

The mortgage lender will then want to do their own valuation (and charge you for it!). This could just be a drive-by looking at the outside of the property, or they might want to come into the house. You probably won’t know which one it is, so make sure everything looks good inside just in case. 

This won’t happen though until you’re already quite a decent way through your application process so if you don’t get what you want to bear in mind you’ll start all over again with another lender. 

Shop around for the lowest rate

Once you’ve checked the LTV you could just remortgage with your existing lender. That might be the quickest option, and it could mean you don’t need to go through as many hoops and cut out some fees. But it could also mean you’re missing out on some much lower deals. 

You can find the best remortgage rates on our comparison tables, which are updated in real time and are really handy to get an idea of what’s out there.

You can also talk to a mortgage advisor, who will be able to give you a much better idea of what you could be offered based on your individual circumstances, and even ways to boost your affordability.

A few extras to bear in mind when comparing different rates:

Find out if you are able to overpay 

It’s really worth looking to see what the rules are in terms of overpayment. Some won’t let you do it at all, while others might have annual limits. Best is complete freedom to pay what you want each month and the ability to clear it completely before the term ends.

Even if you don’t think you’ll be able to overpay by much, if at all, right now, you never know how things could change. It’s really useful to have that flexibility.

And overpaying can save you a fortune in interest charges as well as help you clear the debt earlier. There’s more on whether you should pay your mortgage off early here.

Tembo Mortgage

Compare mortgage rates and deals

Looking for a mortgage? Find the top rates from over 200,000 deals and 100+ lenders with our live tables.

Watch out for fees

You’ll get charged all sorts of different fees with different mortgages, and they can make good looking deals actually worse than ones with higher interest.

The main ones are the arrangement and booking fees. These facilitate the deal and could be non-refundable. You need to factor in these to the total cost of the mortgage deal.

Do this over the length of the deal (eg three years) to work out what you’ll actually be paying over time, and compare it to one with higher rates and lower fees.

Consider if you want to fix for longer

If interest rates are going to shoot up in the coming years, you might want to look beyond the usual two-year fixes. There are often five and 10-year options available, though you may pay a higher rate for these.

Check how much you’ve left to pay

One reason not to remortgage is when you’ve almost cleared your debt. That’s because the fees that are added to new deals could well wipe out the savings you’ll make by sticking put – even if it’s at a higher interest rate! So work out how much you’ll be paying by sticking put just in case it works out cheaper.

Featured deal
Customer rating 3.9/5
  • Switch bonus
    £240
  • Perks
    8% regular saver
  • Monthly fee
    0
  • Offer ends
    Unknown
  • FSCS Protected? Yes
  • Bonus requirements To get the £240 switch offer, you need to complete a full switch with the Current Account Switching Service. Then, within 60 days of your initial switch request, you need to set up two active direct debits, deposit £1,500 into the current account, set up a Santander Regular Saver, and deposit £200 into it.
  • Regular saver 8% (variable) regular savings account. Includes 5% (variable) bonus for 12 months
  • Existing customers? You can't have held a Santander account on 1 January 2026.

When to remortgage

It’s worth looking for new deals around six months before your deal ends as it can take time to get the process approved.

Saying that, you can remortgage at any time, though if you do it before your deal ends you may get hit with exit fees – usually known as early repayment fees.

So generally it’s best not to do it early but you might want to keep an eye on any potential base rate changes by the Bank of England.

If it looks like there’s going to be a significant rise you might want to switch your deal early to get hold of lower price deals – but of course you need to factor in any early repayment charge as well as any changes to LTV.

Important

*Your home may be repossessed if you do not keep up repayments on your mortgage. Be Clever With Your Cash may receive a payment from Tembo Money if you complete a mortgage through the link provided. This will not affect the amount you pay for the service.

This broker fee discount of up to £499 is applicable for standard mortgages and remortgages only, more complex cases including guarantor, buy-to-let, adverse credit, and equity transfer may be liable for a fee. The fee you are required to pay will be clearly outlined by your adviser prior to an application being submitted on your behalf. The offer does not cover any other potential fees that may arise during the mortgage process.

Tembo Money Limited (12631312) is a company registered in England and Wales with its registered office at 18 Crucifix Lane, London, SE1 3JW. Tembo is authorised and regulated by the Financial Conduct Authority under the registration number 952652. Tembo Money was awarded Best Mortgage Broker at the British bank awards in 2022, 2023, 2024 and 2025. Rates are not guaranteed and may change by the time you come to apply. Eligibility criteria may vary by lender.

Our calculator is only an estimate of how much you are able to borrow and does not constitute mortgage advice