
















TSB axes Classic Plus account and cuts 1.5% interest to 0%

It’s replaced by a “Spend & Save” account.

Pretty much every major high street bank has made big changes to it’s rewards in 2020, and now it’s the turn of TSB.

From December 2nd the interest rate will drop from 1.5% (on balances up to £1,500) to zero. ZERO. Following on from the NS&I cut which will take place in late November it’s a huge blow to savers.

Existing Classic Plus customers will be able to keep their accounts, but it’s now been closed to new applicants. It’s been replaced by a TSB Spend & Save account.

Here’s more on the new account, and what to do if you currently have a TSB Classic Plus.

TSB’s Spend and Save account

Right, let’s take a look at the replacement for the Classic Plus. The name gives away the intent – Spend and Save. To get the benefits you need to use it as your main account.

The spend aspect rewards you with £5 cashback each month – though only for the first six months. The save element brings in some of the auto-savings and top-up features we’ve seen at banks like Monzo and Starling.

Here’s more:

Features

Savings pots

Those with Monzo will be familiar with this idea. You essentially separate your money into sub-accounts and name them for different goals or expenses. So you could have one for holidays, one for Christmas, one for emergencies and so on.

If your main account balance gets too low (you set the level), money can automatically be moved out of the pots to avoid you going overdrawn or missing payments. You need to activate this “Auto Balancer” feature.

Save the Pennies

This roundup feature takes each debit card transaction and tops it up to the nearest pound. That extra doesn’t go to the merchant though. Instead it’s moved to one of your savings pots.

Introductory cashback

For the first six months you can earn £5 cashback a month, so a total of £30. However to get this you need to make 30 debit card payments a month.

You can get this offer when you open the account up, or if you switch an existing TSB account over – but NOT a Classic account.

Is it any good?

Frankly no. Though the budgeting features are good, you’re better off going to Monzo or Starling as you’ll get more features.

And the cashback is ridiculous. Asking someone to make 30 transaction a month right now – at a time when we’ve been asked once again to go out less – just isn’t practical. And since it’s not ongoing, it’s hardly worth opening a new account just for six months.

So all-in-all not an account you want to bother with.

What to do with your Classic Plus accounts

Your next move depends a little on why you’ve got the account. Is it, like me, just for savings? Or is it your main current account?

With both it makes sense to switch away. Here are a few options:

If it’s mainly for savings

It’s another frustration for savers this week. I’m particularly peeved as Becky and I have six Classic Plus accounts between us (back when you could have two personal accounts and two joint accounts each). So we, and many others will now be looking to move that cash.

You can wait until the rate drops in December and keep earning that 1.5% until that date. Do this and there’s the risk that other rates will fall and you’ll miss out.

If you haven’t had one already, the best account is the Nationwide FlexDirect offering 2% for one year on £1,500. It’s only for new customers, but one workaround is to open an additional joint account. And since it’s a current account you can move your money in and out, even though the rate is guaranteed for 12 months.

Alternatively, and if you’re able to fix, then it might make sense to open another a savings account now rather than in December. At the time of writing a one-year 1.3% fix was available with Tandem – but that could be gone any day!. And I’d say it’s unlikely you’ll see an account with a higher rate any time soon.

If you need easy access it might also make sense to move now to a new account, even though they come with variable rates as there’s the chance they could be pulled from the market. Virgin Money’s current account offers 2.02% on up to £1,000. However, there’s no guarantee the rate there or elsewhere won’t drop – just as we saw with NS&I.

Here’s my regularly updated guide to the best easy-access cash savings and regular savings accounts

If it’s mainly for banking

If savings aren’t an issue (or once you’ve moved them) then you’ve got quite a few options, and while there are bank switch bonuses available I’d say you should look to nab some of those while you can.

At the time of writing you can choose between £100 from Lloyds or RBS, £125 from HSBC, and possibly £50 from Metro. You could even get hold of more than one – perhaps even all four.

But when you’re thinking of which bank is best for you in the long run as your main account there are other things to think of.

In my latest podcast episode I’ve looked at the most ethical accounts, and Nationwide, Co-op, Starling and Monzo all come out well. The winner though is Triodos – but that does come with a £3 a month fee.

As mentioned above new Nationwide customers can earn interest for the first year, while Monzo and Starling are also great for budgeting.

I’ve listed all the different switching bonuses, rewards and features from high street banks here.

M&S Bank to close all current accounts

What to do if you have a Marks & Spencer Bank current or savings account.

In August, all existing current accounts at M&S Bank will close, and the linked monthly savings account will also shut. The accounts are already closed to new customers.

All 29 in-store branches will also close at the start of July, though the bank will carry on providing credit cards, loans, insurance and other savings accounts.

The retailer says it’s “evolving” to reflect the way customers use their bank, with the branch closures a reflection of the move to online banking.

So if you’re an M&S Bank customer, what do you need to do?

Your current account

If you do nothing, the account will be frozen in August and you’ll have to contact the bank in order to access any money left in there. So it’s important you either withdraw your money and close the account or switch your account. I favour the latter.

Switching your M&S Bank account

It’s really easy to to do this via the Current Account Switch Service (CASS), and comes with a guarantee that all payments in and out will be moved to your new account. Plus, if you switch you’ll also be able to nab a freebie from a different bank keen to get your business.

If you’re overdrawn there’s no guarantee a new bank will also offer you an overdraft, so it might be worth looking at options to clear that if it’s a worry.

Switching takes seven working days, so there’s no rush to move. You’ve got time to wait and see what switching offers come along, but there are some you can get if you want to switch right away.

HSBC Advance Account: Free £125

You’ll only be able to switch to this account for the bonus if you opened your M&S Bank account prior to 1st January 2018.

If you are eligible you’ll need to transfer over two direct debits or two standing orders. The latter are really easy to set up. You’ll get the payment within 20 days of the switch completing.

First Direct: Free £100

As with the HSBC switch, you’ll need to have opened the M&S account before 1st Jan 2018. You need to pay in £1,000 within three months, and the money will be paid within 28 days of this happening.

This is a good option if you want to keep the £250 0% overdraft buffer, and First Direct is the only other bank to offer it.

Virgin Money: Free wine & charity donation

This account from Virgin Money will give you 12 bottles of Virgin Wine and a £50 charity donation via Virgin Giving.

You need to transfer or set up two direct debits and put £1,000 into the linked easy-access saver and keep both active until you’ve got your free wine.

More on these and other bank rewards and offers in my ultimate bank account guide.

Closing your M&S Bank account

You can do this by contacting M&S Bank, though you’ll need to have a zero balance first. If you don’t do this it’ll automatically be closed in August.

You will still be able to see the balance online or via the app after this date – but to access any cash left in there you’ll need to contact the bank.

Statements

You won’t be able to access old statements once the account is closed, so it’s worth downloading these.

Your monthly saver

On hearing the news I’m sure a lot of customers will be frustrated about this linked regular saver closing – it will have been the reason for lots of people to open the account in the first place.

Though the most recently opened monthly savers were only paying 1%, many will still be part way through a year set at 2.75%.

The good news is you’ll get the interest for the full year, no matter how long left you have to save. The bank will assume you’ve paid in the maximum £250 a month and add interest accordingly.

If you want to get the best rate for your savings once you withdraw it from the monthly saver, or find a new regular saver, here’s my updated list of the top paying accounts.

Be Clever With Your Cash is Seven!

The highlights for me and the blog over the last 12 months.

As has now become tradition, I use Be Clever With Your Cash’s birthday as a chance to share with you the good and the bad from the last year.

I rarely write about “blogging” itself or the challenges of running my own business, so also it’s a good opportunity for me to reflect on how things have gone and give you a bit of an insight into what happens behind the scenes.

Plus, I’d really appreciate it if you can fill in my annual survey so I can get your feedback on everything I do.  You’ll also be in with the chance of winning a £25 John Lewis voucher or an hour long video chat with me.

The blog

It’s been a rollercoaster year here on the blog. My biggest concern was that a huge raft of content on the blog was suddenly of no use to anyone thanks to lockdown. From the best travel credit cards to cinema deals, a lot of my regular traffic disappeared.

And as the pandemic dominated the headlines in March and April, my monthly traffic was the lowest it had been in a long time.

But new articles grew to replace that traffic, including my guide to paying a cheque in with your phone and how to find the best savings accounts.

In fact, January 2021 was the best ever month with 217,000 views, and along with October, November, December and February, formed part of five of my six best ever months.

And obviously that all adds up. In late January Be Clever With Your Cash was visited by its 5th million person since it launched. When I started the blog I never imagined I could help this many people. 

It’s also been four years since the last redesign, so a big project that has dominated a lot of my time is a new look and improved UX (user experience design) for the blog, and rebranding for all my channels.

It’s looking really good and I hope there’s something I can share with you in the next month!

YouTube

The biggest success this year has to be my YouTube channel. Hoping lockdown would be just a few months I prerecorded a 12 part series in March, mainly because I knew I wouldn’t get a haircut for ages.

But it was only in June when I finished publishing all of these, and came to terms with how bad my lockdown hair was, that I started to knock out content that seemed to work on YouTube.

As a result videos have been viewed 400,000 times and subscribers have jumped from 800 odd a year ago, to just under 7,000 today.

The last couple of months have been particularly good, with four of my all-time most watched videos released since January.

The channel is also now earning me some money via adverts. It’s not a huge amount, and doesn’t cover the work I put in, but I hope that’ll grow.

If you haven’t already, please do subscribe, and hit the thumbs up button or comment on any videos you watch – it all helps.

The podcast

It was a good year for Cash Chats too. The rhythm I found in late 2019 continued into 2020 and as a result, there was a lot of growth.

It surpassed 200,000 all-time downloads in November 2020, at the same time as releasing the 150th full episode (in reality the bonus episodes mean I’ve made more).

I started this year with a new regular second episode looking back at the last seven days of money news which I’m really enjoying too.

If you’ve not listened to Cash Chats before you can stream or download it here.

Media & Recognition

Sadly some TV projects I was booked for were cancelled due to the pandemic, but I’m hopeful they’ll come back! I did consult on a new Channel 4 series which should air soon. I carried on popping up on BBC Radio, including a couple of spots on BBC 5Live Drive during the first lockdown.

Elsewhere, while I know awards don’t make a huge amount of real difference, when you’re working for yourself it’s nice to get acknowledgment from your peers for your efforts! There were no wins, this year, but I received a few nominations.

The blog was once again a finalist at the Headlinemoney Awards and is currently in the running for best online finance influencer at the British Bank Awards (you can vote for me here!).

My TV and podcast work was also recognised at Headlinemoney as a finalist in the Broadcast Journalist of the Year category.

The business

With TV work cancelled and Moneywise magazine closing down I didn’t chase a huge amount of freelance work. Instead, I worked almost exclusively on my own projects. And somehow I was busier than ever!

A year ago I wrote how I was struggling with essentially on my own in my basement office five days a week – but it turned out it was great training for lockdown.

Once more the weekly video chats with some of my fellow money bloggers from my UK Money Bloggers community was a vital connection to people who are in effect virtual colleagues. 

I’m a little worried about how I’ll continue producing as much as I do right now when restrictions finally (hopefully) end, so once again I’ll be looking at ways to improve my productivity.

My annual survey

It’s so important to me that any content I produce for you is what you actually want to read, hear or watch. So please do take a few minutes to answer this short survey. 

If you also enter your email address at the end of the form you’ll also be in with a shot of winning a £25 John Lewis voucher or an hour long video chat with me. This prize draw ends 30th March 2021 and one response will be randomly selected and asked whether they want the voucher or money chat. Open to UK followers only.

HSBC to close 82 branches

Find out if your local branch is affected, and what you can do if it is.

Starting in April 2021 and continuing until September, a total of 82 HSBC branches will be closed.

We’ve seen this happen more and more in recent years as people turn to online and digital banking, reducing the need to ever bank in person.

Even without the pandemic, HSBC says 90% off all customers use phone, internet or app banking, and branch use has dropped by a third in the last five years.

Other HSBC branches could also change and no longer provide “full service” banking. It’ll also potentially impact First Direct and M&S Bank customers who are able to use HSBC branches to pay in cheques or withdraw cash.

These latest closures will mean a total of 3,836 branches across all banks have shut since 2015, according to Which?.

There’s a full list of which branches are going and when below, but first some tips for you if you are affected.

What to do if your branch closes

If you bank with HSBC and your local branch closes you’ve got a few options. It depends on whether you think you need to have a branch near you or not.

Those not bothered about losing a local branch don’t need to do anything and you can do most banking online. However, I’d say you’d be better off looking for a better digital bank, such as Monzo or Starling. I think it’s also worth considering that HSBC scores poorly when ethical banking is taken into account.

If you do need some services, HSBC claims 81 of the branches going are less than a mile from a Post Office and two-thirds are within five miles of another HSBC.

But if it’s important that you have a branch near you then you might want to consider switching to a new bank. The risk is future branch closures could see your new location disappear too, but until that happens it’s not worth worrying about.

If you are thinking of changing your bank, make sure you see what options are available to you, such as freebies, overdrafts and switching bonuses.

Full list of HSBC branches closing in 2021

23rd April:

  • Edinburgh, Princess St

7th May: Brighton,

  • Ditchling Road; Hull,
  • Merit House; Wednesbury;
  • Sutton Coldfield, Four Oaks

14th May:

  • Hull, Holderness Road;
  • Pontyclun, Talbot Green;
  • London, Fleet Street;
  • London, Fenchurch Street

21st May:

  • London, Old Broad Street;
  • London, Charing Cross;
  • Sheffield, Darnall;
  • Oxford, Summertown

28th May:

  • Leeds, Chapel Allerton;
  • Cardiff, Rumney;
  • Torquay, Strand;
  • Staines

4th June:

  • Plymouth, Forder House;
  • Belper, King Street;
  • Colchester;
  • London, Whitechapel

11th June:

  • London, Marylebone;
  • London, Streatham Hill;
  • Falkirk High Street;
  • Fleet, Fleet Road

18th June:

  • Reading, Woodley;
  • Oxford, Headington;
  • Swansea, Gorseinon;
  • Wigston, Leicester Road

25th June:

  • Tavistock, Bedford Square;
  • Bristol, Nailsea;
  • Leeds, Cross Gates;
  • Yate, North Walk

2nd July:

  • London, Kingsbury Road;
  • Cleckheaton, Bradford Road
  • Bexleyheath, Broadway
  • London, South Woodford

9th July:

  • Birmingham, Erdington;
  • Goole, Wesley Square;
  • Congleton, High Street;
  • Formby, Chapel Lane

16th July:

  • Gillingham, Kent;
  • Dunstable, West Street;
  • Chorley, Market Street;
  • Pontypridd, Taff Street

23rd July:

  • Felixstowe, Hamilton Road;
  • Godalming, High Street;
  • Prestatyn, High Street;
  • London, Southgate

30th July:

  • Tewkesbury, High Street;
  • Maldon, High Street;
  • Hatfield;
  • Herts;
  • Huntingdon, High Street

6th August:

  • Stockport, Bramhall;
  • London, Russell Square;
  • Richmond, Market Place

13th August:

  • Loughton, High Road
  • Rustington, The Street
  • Exmouth, Chapel Street

20th August:

  • Bournemouth, Winton;
  • Liverpool, University;
  • Cleveleys, Victoria Square;
  • Clevedon, Triangle

27th August:

  • Northallerton, High Street;
  • Walton-on-Thames, High Street;
  • London, High Holborn

3rd September:

  • Barry, Holton Road;
  • Aldershot, Wellington Street;
  • Eastcote, Field End Road;
  • London, Edgware Road

10th September:

  • Ramsgate, High Street;
  • Manchester, Chorlton-Cum-Hardy;
  • Letchworth, Station Place;
  • London, Hackney

17th September:

  • Barnet, High Street;
  • Deal, High Street;
  • Cheshunt, Turners Hill;
  • Swadlincote, High Street

24th September:

  • Dorking, West Street;
  • Welshpool, Broad Street;
  • London, Surrey Quays;
  • Worksop, Bridge Street

For those wanting to move away from HSBC, here’s my look at the best bank accounts in the UK.

How to cut the cost of your overdraft

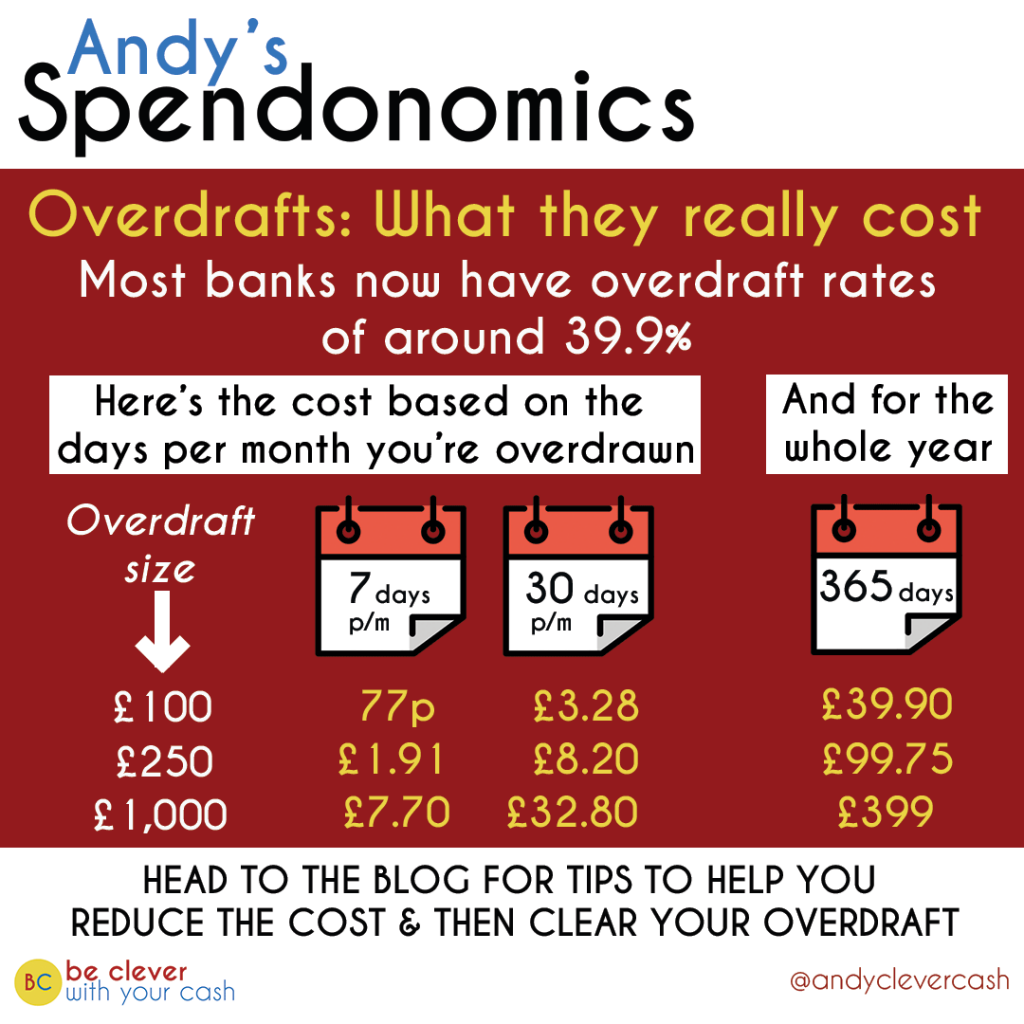
You could be paying as much as 40% interest each time you dip into your overdraft.

Last year the banks were made to bring in a simplified single interest rate charge for overdrafts. The hope was this would make it easier for people to work out how the cost the existing mix of daily fees, interest and other charges.

Well, it’s certainly a lot clearer – but sadly it’s not necessarily going to be any cheaper to go overdrawn. The banks pretty much all decided to charge around 40%.

For those that only rarely use an overdraft it’ll actually be cheaper. But for people who “live in their overdraft” it’ll probably cost a lot more.

In fact, at 40%, an overdraft is now one of the most expensive ways to borrow money! So if you regularly use one the best way to beat these costs is to clear the overdraft and get your bank balance back in the black.

Reducing the cost of your overdraft

Of course, wiping out hundreds or thousands of pounds isn’t going to be quick – so don’t wait. Every day you’re in an expensive overdraft it’s costing you cash.  You want to first of all find a way to reduce the interest that gets added.

I’ve shared a few tips in this video, or keep reading.

You can watch more videos over on my YouTube channel. If you found this useful, please click through and like / comment on the video

Move to a cheaper overdraft

You can switch bank accounts even if you have an overdraft – though the new bank has to agree to offer you a new overdraft. This can be dependent on how large your overdraft is and on your wider credit report.

The best overdrafts are obviously 0% ones. These tend to be quite small. M&S Bank has a £250 0% overdraft, but there aren’t many others out there (First Direct account are still closed to new aplicants).

For a larger interest free overdraft you can apply for a Nationwide FlexDirect account. New customers who’ve not had the account before can get a one year 0% overdraft, giving you more time to pay it off. The size of the overdraft will be dependant on your credit report.

You can check out the best overdraft deals at the banks here.

Ask for a £500 interest-free buffer

One of the support measures introduced during lockdown was a £500 interest-free overdraft for all banks. It was set to last just three months, but you can ask for a further three months.

This ended with most banks last year, but a handful extended this. You have until 31st January 2021 with Halifax, Lloyds and Bank of Scotland to make your initial or extension request. At Santander it’s until 4th May 2021.

If £500 isn’t enough to cover your debt, or you’re with a differen bank, then ask for other ways they can help you. This could be temporarily reducing or waiving the rate you’re charged, or perhaps looking at a loan to help you clear it at a lower rate.

Failing that you might look at Monzo or Starling which have cheaper overdrafts for some customers.

Get a 0% Money Transfer credit card

These credit cards work like a balance transfer credit card but instead using a new credit card to clear a credit card debt, you’re using one to clear your overdraft. So you’ll still owe the cash, but it’ll be on a 0% deal for a set amount of time, usually 18 months or more.

There’s normally a fee to transfer the money from the new credit card over to your bank account, and of course you need to make the minimum repayment on the new card (at least) each month.

Here’s more on how Money Transfer credit cards work.

Get a loan

For large amounts, you could look to a cheaper loan to clear your overdraft. You’ll obviously need to make sure you pay that loan off. The best rates will depend on your credit file.

How to clear your overdraft

Once you’ve reduced the cost of the overdraft you need to start paying off the money you owe.

Use savings

If you have savings, you’re better off using them to clear your overdraft. The interest you’re earning on them will be far, far worse than what you’re being charged. If are worried about what would happen if you have an emergency later on having cleared out your savings, you can then look to borrow money. But there’s no point borrowing, and being charged for it, when you don’t need to.

Open a new bank account

The big tip from Sara Williams at Debt Camel when she guested on my podcast was to open a separate account for day to day spending – essentially starting afresh.

This helps you split out the overdraft you owe and the money you have coming in. So the old account would now work more like any other debt you have. You can see the balance owed going down as you clear it rather than see it reduce you get paid and increase as you pay the bills.

Ideally set up a set amount to transfer over to the debt each month, and top it up with more cash when it’s available.

Use the money that would have been interest payments

If you’re now paying 0% interest, you’ll be saving the cash that would previously have gone on those overdraft charges. Make sure that money is still going towards the debt to help clear it faster.

Have some leaner months

If the overdraft isn’t huge, then it might not take long to clear it by drastically cutting back your spending over a few months. Once it’s back to zero, make sure you don’t dip back into it.

You can also look to earn extra cash, such as selling unwanted and unused items online or taking on extra work.

Three reasons to check your final bill when you switch

Companies are happy to take our cash, but when they owe us, it’s a different matter – especially if we’ve moved our business elsewhere. The problem is, if you don’t check your final bill you might never realise they’ve kept your money.

We’re in a switching society. It’s so easy to change supplier, whether mobile phone or pay TV. Great! But there’s something about switching that’s not so simple – and it could end up costing you cash.

I’ve found most times I switch it takes a while to get the final bill – and when it does, it’s usually not what I expected.

Here are three things to look out for on your final bill.

1. Have you been overcharged?

Last month I left Three and moved to SMARTY, as part of my search for the perfect lockdown SIM. Well, the final mobile bill arrived this week – and they owe me money! £2.42 in total! Ok, so it isn’t much, but it is still my money.

The same has happened when I’ve left other providers including Sky, TalkTalk, NPower and other utility providers. Each had a positive credit left on the account where I’d overpaid. This is quite normal as you usually pay a little in advance.

The issue with each of them is I had to phone them to get a refund. Yes, they were happy to take my cash, but less inclined to automatically give it back to me.

Some have got better and will process the payment – but as my bill from Three showed, some will still ask you to claim.

Yet how many people bother to check their bills to see the final totals? I’m sure there’s a ton of cash sitting with Three and other companies that by right doesn’t belong to them

So if you don’t check your final bill, or chase the company after leaving, that money will just sit there. Go check your old accounts and make sure you aren’t owed money too.

> More ways to get money back that you’re owed

The same thing happened to me when I left Three a previous time (back in 2017), as I spoke about in this short video

2. Have you underpaid?

Of course, there’s also a chance you end up owing the old company. This is most likely with energy bills as they’re estimated each month, but it could easily happen if you buy extras through your mobile network or rent movies via your TV provider.

This happened to us a few years ago when we switched from EOn to EDF. It turned out our direct debits had been VERY low, and our final bill was £100. We had enough to cover this, but if you didn’t expect it and that money just disappeared from your bank account (they’re still happy to take this money), you could get hit with overdraft charges.

You can mitigate this, with energy bills at least, by providing regular meter readings. Or in theory smart meters will mean bills are accurate and not estimated.

3. Are you still paying?

Sometimes when you think you’ve cancelled, you haven’t. Direct debits and standing orders could keep coming out, and if you don’t check you won’t know.

The main offenders are subscription services you stopped using or forgot you had, things like Netflix or Spotify. The monthly cost is pretty low so you might not notice them on your bank statement – but over a year they can add up, especially if you are signed up to multiple ones.

My advice with streaming services is to cancel every month as soon as you sign up. It won’t take long to sign up again in 30 days time if you want to keep using the service – you might even get a discount to come back!

Of course, mistakes can be made too that mean bigger bills keep getting charged, especially if you’ve just stopped your contract rather than switched. It’s not uncommon for old mobile phone accounts to still be running along even though the phone is buried in a drawer and you thought you had cancelled.

Plus, watch out for some of the biggest bills you probably didn’t even remember you had. Annual insurance policies on your car, home or travel can be very expensive and often roll over if you don’t stop them.

The easy way to check this is to get your bank statements or open your banking app and look for the standing orders and direct debits. If there are any regular payments coming out, check they are things you should be paying for.

I always did this with the families I helped as part of Channel 5’s Shop Smart Save Money and in one episode I spotted the household was paying two lots of Council Tax! They’d moved three months before but hadn’t told the previous council about it. They were able to get a refund, but that won’t always be the case.

Premium Bonds: Are they better than savings accounts?

Will you get £1million, or will you get nothing?

With interest rates so low there’s been a huge increase in the amount of money invested in Premium Bonds as people hope to get a better return on their cash.

But hope is the key here. Though there’s a chance you could win £1 million, there’s no guarantee you’ll get anything.

Here’s what you need to know about Premium Bonds, and how they compare to other savings products.

Keep reading or watch this video (or both)

What is a Premium Bond?

A Premium Bond is essentially a government savings account you buy from National Savings & Investments.

Rather than earn interest on the money invested as you would with a normal savings account (if it’s offered of course), you’ll be entered into a monthly prize draw. And this will keep happening for as long as you keep the Premium Bond.

Each bond costs £1, though there’s a minimum purchase of £25, which would give you 25 entries into that draw. The most you can have are 50,000 bonds, which means there’s a cap of £50,000 you can save.

Any money you win is tax-free and your savings are protected by the Treasury, and that initial investment can’t lose value.

The money is easy-access and you can cash them in whenever you want – though it can take up to eight working days to reach your linked current account.

How much could you win?

The top prize is £1 million, and there are two of these available each month. So in theory you could win £24 million a year! But of course you won’t.

The current prize rate with Premium Bonds is 1.4% (it was 1% from December 2020 to May 2022, and could change again). This doesn’t mean you’ll get a 1.4% return on your savings. Instead on average £1.40 is paid out for each bond. On average.

But most bonds win nothing. Zero.

And that’s because all the money paid out to all the winners is made out of prizes ranging from £25 up to that £1 million. So it’s impossible for every bond to get that quid.

Here are all the prizes on offer for June 2022

Prize valueNumber of prizes each month
£1,000,0002
£100,00010
£50,00019
£25,00040
£10,00098
£5,000196
£1,0002,764
£5008,292
£10037,922
£5037,922
£254,747,097
Prizes for the May 2022 draw. You can see monthly updates on the NS&I website

So though you’re more likely to get a £25 prize than any of the larger ones, it still leaves 100 billion bonds winning nothing each month!!

And while each bond has an equal chance of winning any of the prizes, the more bonds you have the greater the chance is that you’ll win something.

Money Saving Expert has a calculator which works out what you’d get with a typical amount of luck which is helpful to get a closer idea of a more realistic return – though of course since it’s all random it’s no guarantee. You can also see how lucky you are compared to others.

Premium Bonds vs savings accounts

* The following tables are based on a 1% prize rate and will be updated in June 2022 *

I’ve used MSE’s calculator to work out those potential winnings (based on average luck) over a year and therefore what interest rate you’d need to get the same amount from a savings account.

Amount savedAverage winningsEquivalent interest rate
£10000%
£1,00000%
£10,000£750.75%
£25,000£2000.8%
£50,000£4500.9%

Of course you can still win a prize with just £25 worth of Premium Bonds, it’s just incredibly unlikely. The calculator also says you’ll likely win £50 with £5,000 saved, which is 1%, but that seems to be a bit of a blip. Having fewer bonds will mean you’ll win less, so I’ve not put it in this table.

Right so how do these rates compare?

Well the best easy-access account right now pays 0.5%. So you’re likely to beat this with Premium Bonds for savings above £5,000.

But as I frequently share, you can get higher rates on some of your cash. Here are my top picks:

AccountInterest rateMax depositInterest earned in a year
Virgin Money M Plus Account2.02%£1,000£20.20
Chip+11.25%£2,000£25
Club Lloyds Current Account0.78%*£5,000£39
Club Lloyds Monthly Saver 1.5%£400 a month£38.91
Marcus Easy Access 0.5%(£4,800 fed into the above monthly saver)£11
* 0.6% on first £4,000, 1.5% on next £1,000

As you can see, each of these accounts will get you a guaranteed better return than the average chance of luck does with Premium Bonds with the same amounts.

Though that rate is much closer with the £5,000 amount in Lloyds, remember that interest is guaranteed – plus you get freebies on top such as monthly movie rentals or cinema tickets.

If you use all these accounts listed above you’ll save a total of £12,800, making a total of £134.11 in interest over a year, which is the equivalent of 1.05%.

(N.B This calculation was before Marcus dropped its rate to 0.4%. on 16th March, but the difference is £2 less in a year).

Read more about my top three savings accounts

How much you need in savings to make Premium Bonds worth it

If you’ve got savings up to and including £12,800, I’d focus my attention on The Virgin M, Chip+1, Club Lloyds and a leading easy-access accounts.

Where you put further savings depends on how much more money you have. Less than £5,000 and you will probably be better off putting more into that Marcus account (or equivalent) and probably drip-feeding it into another regular saver.

But if you have £5,000 or more, the average luck rates suggest that you could instead move on to Premium Bonds. However, there’s an important upper limit.

Though you can put £50,000 into Premium Bonds, you don’t have to. And you probably shouldn’t.

That’s because you don’t want to have too much saved in easy-access accounts. Really you only need to have enough cash to cover one of two things – an expected expense or an emergency.

When you’re saving for a specific purchase – from a house deposit or wedding through to a holiday or new phone – you’ll know much you need access to.

The general rule of thumb for emergency savings is three to six months of essential expenses – the costs you would have to cover if you lost your income. Following the pandemic you might want to make that last a little longer.

But beyond this, with interest rates so very low in general you are better off thinking about putting any remaining cash aside for the long term, whether that’s topping up your pension, paying off your mortgage or investing in the stock market.

So, going back to that initial £12,800 in the top savings accounts, and the minimum £5,000 Premium Bonds needed to beat the best easy-access account… we’re now at a total of £17,800.

How long would that last you in an emergency? I’d imagine six months easily, probably more.

So really I think Premium Bonds only become worth a look for most people if you need to have more than £17,800 in easy-access savings.

(Update 16/3/21- the upper limit on the balance you can earn interest on with the Chip+1 account has been increased from £5,000 to £10,000. After fees this gives the equivalent interest rate on the full £10k saved as 1.06%. That is a guaranteed rate and higher than the potential return with Premium Bonds. Here’s my full analysis.)

It’s different for additional rate taxpayers

A quick note that the situation changes if you are an additional rate taxpayer (meaning you earn more than £150,000 a year). If this is you, then you won’t have a Personal Savings Allowance, which means you’ll pay tax on your interest.

The Cash ISA limit is £20,000 (and that’s shared with Stocks and Shares ISAs), so Premium Bonds can work out as the most tax-efficient way to have cash savings.

What if you fancy your chances?

Of course, you might think that it’s too much hassle spreading your cash around multiple accounts for minimal returns. And you might not be wrong there.

Let’s say you’ve got £5,000. Put it in that easy access account paying 0.5% and you’ll make £25 interest in a year.

Would you spend £25 a year on Lotto tickets or scratch cards? Well, maybe Premium Bonds is a better alternative. You might win, you might not, but you’ll keep that initial investment.

When to save with Premium Bonds

So in summary, Premium Bonds could be a good option for you if:

  • You need more than £17,400 in easy-access savings
  • You are an additional rate taxpayer
  • You just fancy a flutter
  • You’re ok with the idea of getting nothing

How to get Premium Bonds

You have to be over 16 years old to buy Premium Bonds for yourself. If you are buying them for children, the account will be held by the parents/legal guardians until the child reaches 16.

The easiest way to buy them is via the NS&I website, though you can also get them via post or on the phone.

When to buy Premium Bonds

The Premium Bond draws take place at the start of each month, but you’re only eligible for each draw on bonds that have been invested for a full month.

This means you’re better off buying them at the end of a calendar month than at any other point.

How to check Premium Bond winners

You will need to enter your account number (called a Holder Number) into the NS&I Premium Bond prize checker.

If you’ve won you’ll see just how much, and you can use the same tool to see any previous wins you might not have known about.

You can listen to me talking to Money Saving Expert’s Helen Saxon about Premium Bonds in this episode of my Cash Chats podcast.

Slow broadband? How to leave penalty free

New rules should make it easier for you to get the broadband you’re paying for. Though it won’t solve wi-fi issues.

[box]

Contents

Some articles on the blog contain affiliate links, which provide a small commission to help fund the blog. However, they won’t affect the price you pay or the blog’s independence. Read more here.

[/box]


There’s little more frustrating in modern life that bad broadband. My work is mainly online, so a decent connection is essential, and most of the time it’s sufficient. But when it comes to streaming films and TV, I’ve had to give up when dropped connections and slow speeds cause constant buffering. So some new rules this month are more than welcome.

Your new rights

There are a few parts to the ‘code of practice’. Although participation is voluntary, BT, Virgin, TalkTalk, Sky, EE and Plusnet have all signed up – which amounts to 95% of the market. Here’s what you can expect as a consumer:

Companies have 30 days to fix speed problems or let you leave fee-free

When I’ve had speed and connection issues my major frustration has been the cycle of deferment to get anything done. Most recently it took three or four calls to get an engineer booked to take a look at my Virgin connection. Hopefully this new rule will make providers act faster.

If they don’t you can cancel and take your business elsewhere. There are likely to be some great new customer deals for you to take advantage of. Though ask neighbours who they are with and what speeds they get – it could be a case of better the devil you know.

You can cancel TV and phone contracts at the same time

One major issue with bundled telecoms is you’re often tied into the other parts of your package even if you can leave one. Now, as long as you took out the additional services at the same time as your broadband, you can cancel them all without penalties if the speed issue isn’t fixed within 30 days.

You’ll be told the minimum speed you’ll get at peak times

This only really applies to new customers – though if you’re a keen money saver then this could be you every 12 to 18 months. Now when you sign up, you’ll be told the minimum guaranteed speed at peak times, which Ofcom says are 8pm to 10pm. It’s these hours, when more people are at home and more devices are being used that more strain is put on the broadband infrastructure, and speeds drop as a result.

This applies to all connections

Until now cable wasn’t included in fairness rules. These changes cover all connection types, whether copper, fibre or cable – as long as the provider is signed up.

Ofcom broadband rules graphic
Ofcom’s guide to the new rules

What it doesn’t cover

I’ve noticed more and more when I contact Virgin about low speeds that they try to fob the issues off as wi-fi problems.  So if the problem with speeds is actually down to the size of your house, positioning of walls or placement of the router, it won’t be something the code of practice covers. I think this will be the excuse used to get around the rules – though in fairness, the speeds advertised are only into the home via a connection.

How to improve bad wi-fi signal

You can try wi-fi boosters to help improve your signal. These include powerline adaptors you put plug sockets so the signal is transferred via the electrical wiring. You plug one into a socket near your router and connect them via a cable. Then you put your other adaptors in sockets in rooms the signal can’t reach. I installed a set similar to this at my parent’s house and it works well to give them coverage in a black spot.

However they didn’t work for me at my house, possible because the wiring was on different circuits. So I tried instead a wireless extender. This acts as a relay point and works well.  They can cost more though – this is the one I got on offer last Prime Day to make it more affordable.  and

Or if this doesn’t work, you can try very expensive “mesh” systems” (like this one from BT) which create a new network for you. Or something. 

How to check your internet speed

Ideally you should connect your computer or laptop to the router via a cable to get the most accurate speeds – and those are the figures the broadband companies will use as a benchmark. But you can test on wi-fi too to get an idea. I tend to use Speedtest.net on my devices (there’s an app for phones and tablets too), and Ofcom has it’s own checker too.

How to get cheaper broadband

I’ve written a few guides to help you cut what you pay for your internet connection. Take a read off the following articles to learn more:

How to cut the cost of your broadband and landline bills

How to beat broadband price hikes

The seven levels of Talk Talk hell

Are your debts a problem?

Seven questions to help you decide if your debts are worse than you think.

The average total debt per UK household is currently £59,261 according to the Money Charity’s latest figures. That’s a mix of credit cards, loans and other types of borrowing such as mortgages. But take out mortgages and the average consumer credit debt stands at £7,863 per adult. The interest costs alone on that amount are going to be huge.

Those figures are averages. You could have more or you could have less. And they might be perfectly affordable for you. But there’s a risk, whatever the amount of the money you owe, that these debts are or soon could become a problem.

I’ve got seven questions for you. Have a think if they relate to you and your debts. Make a quick mental note of whether it’s “yes” or “no”.

1. Are you unsure of how much debt you have?

I’m not saying to the nearest penny, but could you say within £50 or £100? If not, total up the debt. This can be quite sobering.

2. Are you spending more than you earn?

I imagine for lots of people the answer is probably “I don’t know”. To find out you need to do a budget, something I wrote about here.

3. Do you need to use credit for everyday essentials?

By the end of the month, do you need to use a credit card or overdraft to get food from the supermarket or pay some bills?

4. Have you been rejected for credit?

This could be anything from a mortgage or credit card, down to a mobile phone contract.

5. Are you ashamed or worried about your debts?

This could manifest itself through hiding debts from your partner, losing sleep or being scared to open up bills.

6. Are you behind on repayments?

This isn’t just being behind or late on paying your bills. It could be you’re only making minimum repayments. Or you find direct debits or standing orders are bouncing.

7. Are you borrowing to pay your other debts?

This could be taking out payday loans or cash advances on credit cards just to clear other debts.

What do your answers mean?

Each of these, just on its own, is likely a sign you need to take action to avoid bigger problems. Hopefully you can sort this yourself by bringing down the cost of your borrowing and finding as much money as possible to clear the debts as fast as you can. I’ve shared a few ways to better manage your debts here.

But if you answered yes to a fair few, then it there’s a chance the situation is past a DIY resolution already. This means you need to get help. Don’t pay for this. There are lots of free and independent advice lines run by charities such as StepChange, Citizens Advice or NationalDebtLine. They’ll help you work out what’s best to do. This guest post from top debt blogger Debtcamel takes you through some of the steps you can take.

Want to read more?

What can you do if your debts are getting too big?

How to quickly clear your credit card debt

How to quickly clear your credit card debt
